
What Is Harper Insurance?
Harper suits hard-to-place businesses such as contractors, care providers, manufacturers and transportation firms; standard small businesses seeking direct quotes should compare online carriers. Its workers’ compensation service helps classify payroll for audits.
Harper is a commercial insurance brokerage: it helps businesses find insurance from other companies and arrange the purchase. You can request a quote online or speak with a specialist, who gathers information, approaches insurers and explains the options. 3,10Current buyer-facing brokerage description. This does not establish insurer status, universal market access or an independently tested purchasing outcome.
Businesses in hard-to-place industries can ask Harper for broker help; its listed specialties include contracting, restaurants, auto, care, manufacturing and transportation. 9,14Examples of advertised appetite, not a verified customer census or eligibility guarantee.
What Are the Pros and Cons of Harper?
Pros
- Pro: A focus on difficult commercial risks. Harper markets to businesses that can be harder to place, including security operations and other specialized industries. Its offering combines a broad coverage menu with brokers who approach insurers for the applicant. 14 9 12
- Pro: AI assists the brokerage team with routine work. Harper describes extracting document information, drafting messages and organizing follow-ups, while licensed professionals and carriers review final eligibility and binding decisions. That gives buyers a more concrete explanation of the service than the AI label alone. 4
- Pro: Help beyond the initial quote. Its published services include annual coverage reviews, policy administration and claims advocacy. The customer portal advertises access to certificates, policy documents, payments and application status. 18 17
- Pro: An option for referrals from another agent. Harper Partners explains the commission split and assigns quoting, placement, service and renewals to Harper. Buyers introduced through that program can identify which agency is meant to handle the ongoing account. 16
Cons
- Con: Buyer-paid fees are not set out in a public schedule. The referral program explains payments between agencies, but it does not establish your account's commission or total charges. An itemized quote is needed to distinguish premium, fees and financing costs. 16 18
- Con: Specialty-market authority needs proposal-level confirmation. Harper advertises wholesale access and binding authority on selected programs without identifying the full insurer, product and state scope. Its underwriter-network count does not show how many distinct insurers will quote a particular business. 15 14
- Con: Its disclosed AI data use deserves attention before uploading files. Harper says customer communications and policy information help train its own models. That is separate from its enterprise vendors' statements about not training their foundation models on customer data. 4
- Con: A quick conversation is not binding confirmation or an urgent claims channel. Harper's terms prohibit binding or changing coverage by text and warn against relying on texts for time-sensitive matters. Customers need written coverage confirmation and policy-specific claims instructions. 3
How Does Harper Work?
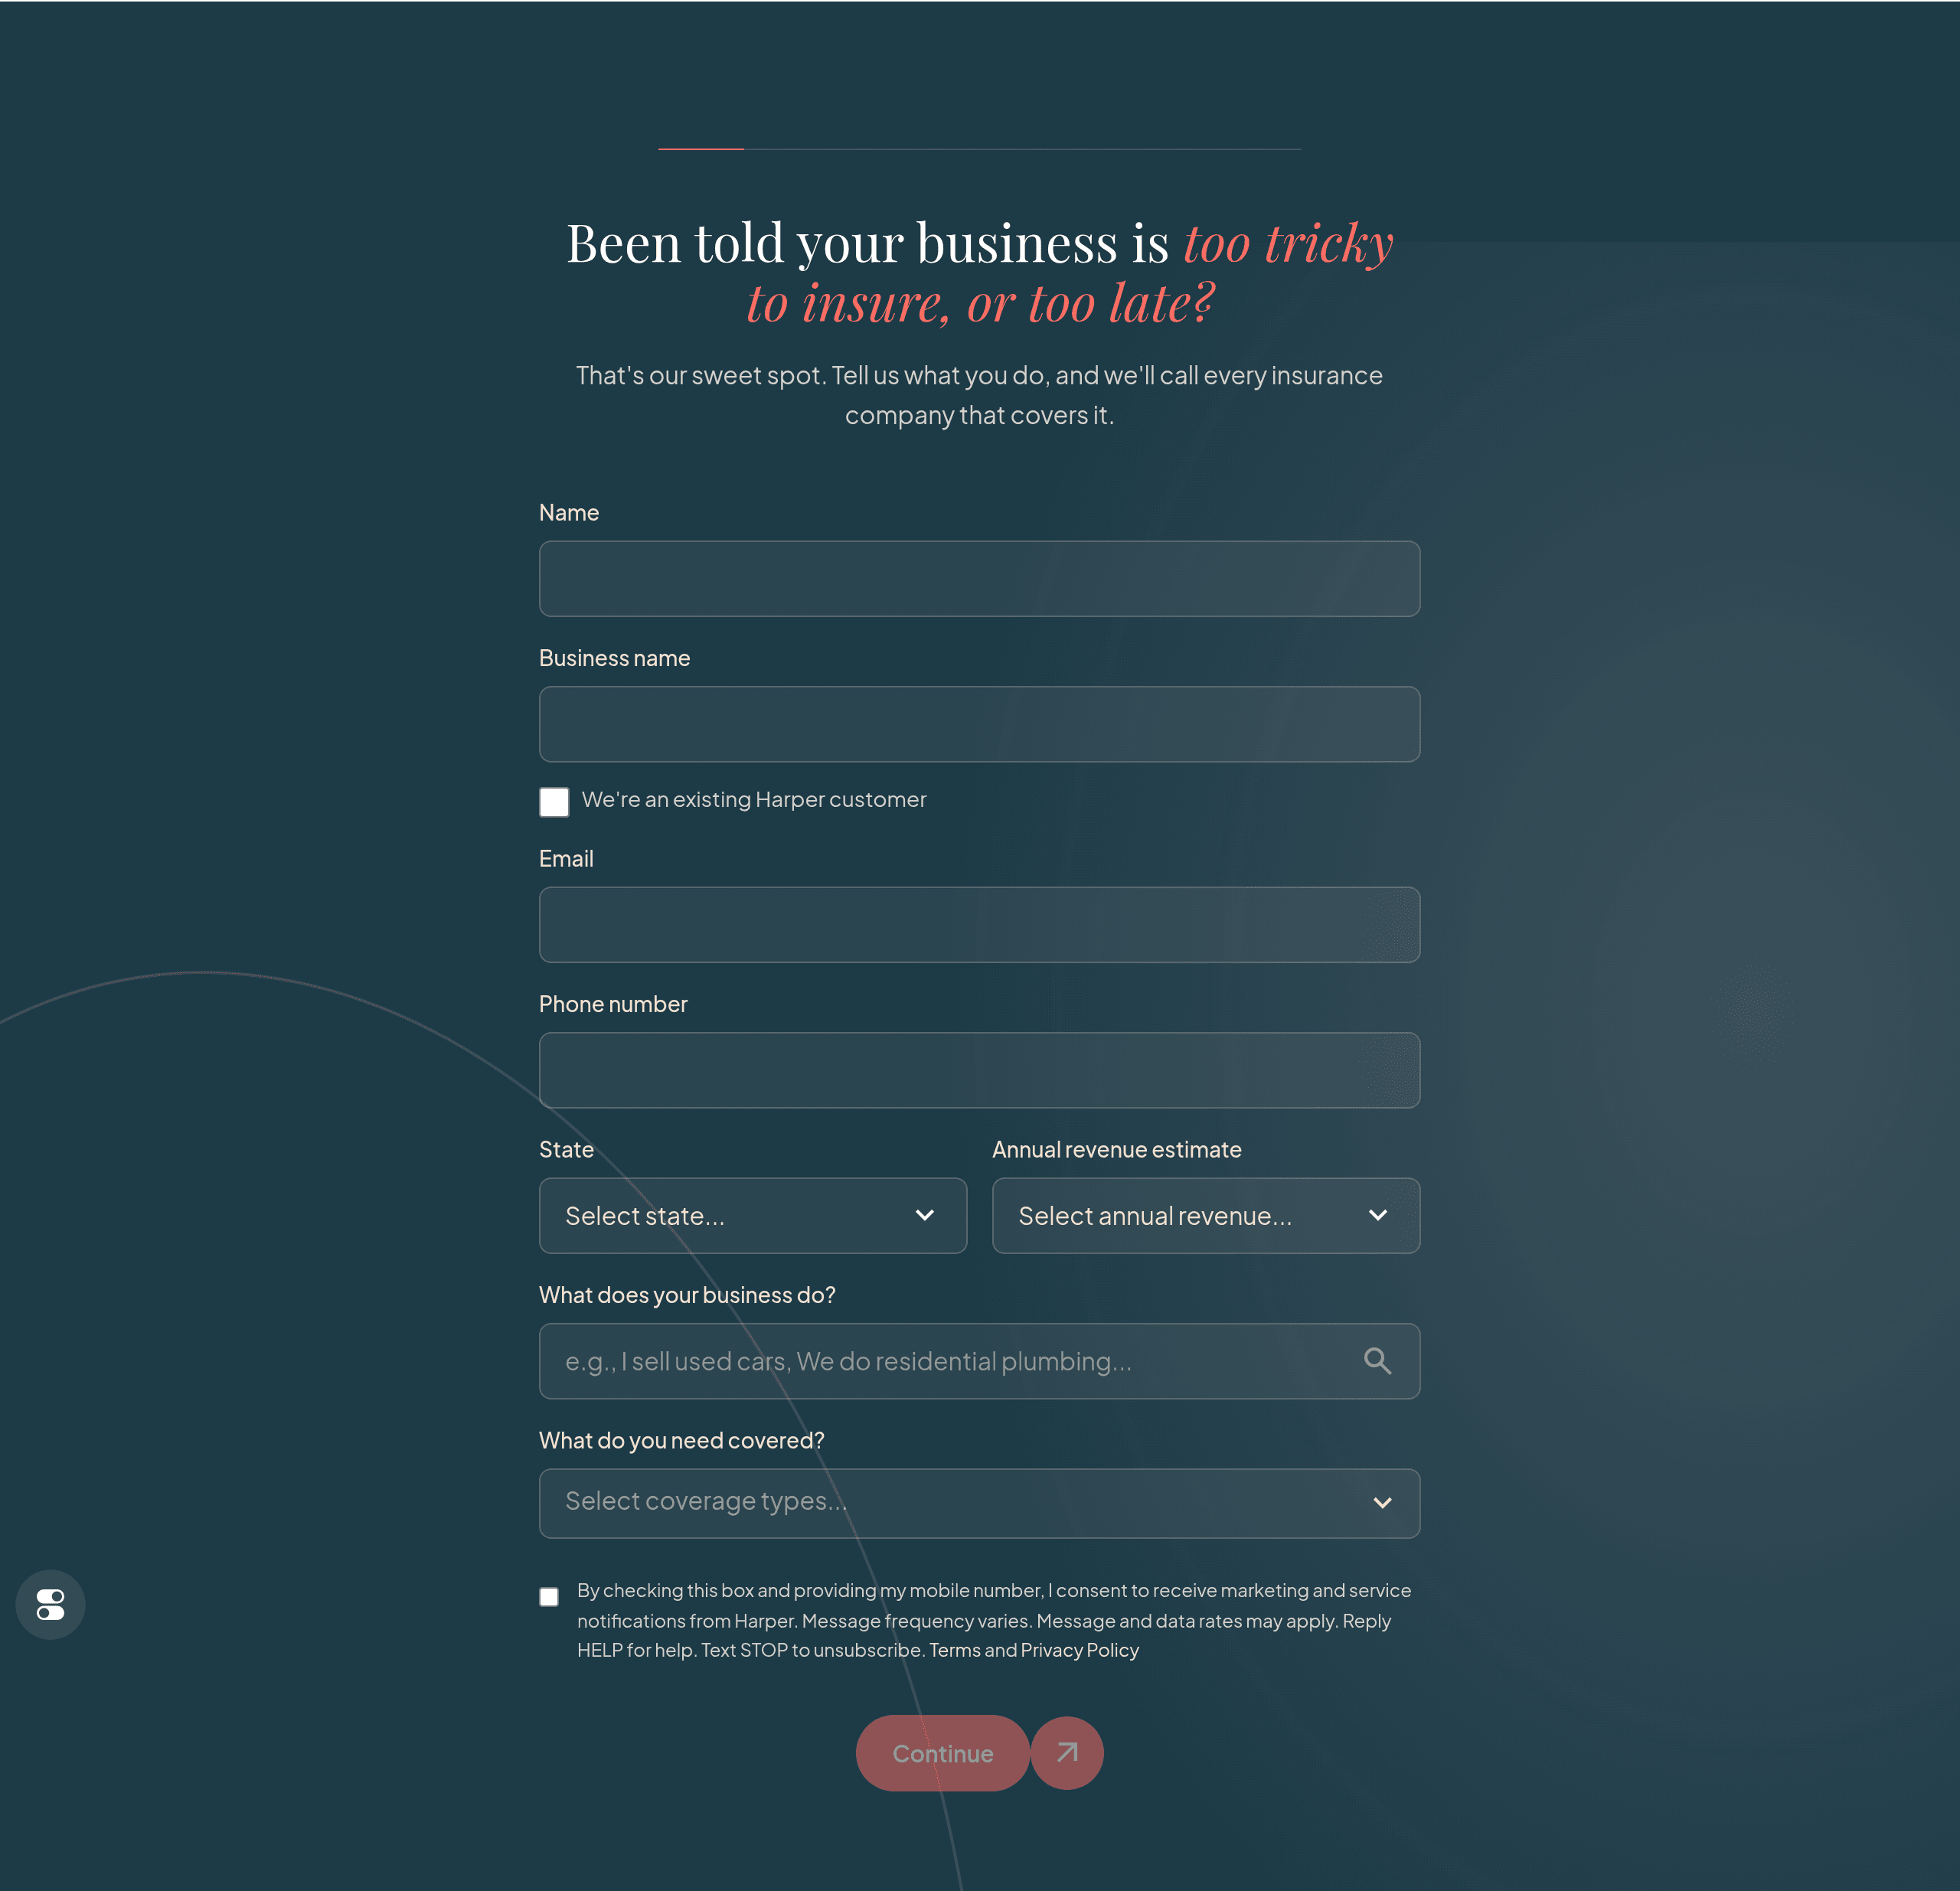
You can request a quote by providing business, revenue, state, operations and coverage details; the form starts an inquiry and does not show a premium or issued policy. 2Browser inspection of the blank homepage footer form. No data entered or submitted, so later application, quote, payment and binding screens were not tested.
What the AI Does
Harper says its internal Hub software helps staff complete forms, identify markets and manage client communication; the launch announcement describes greater automation as a future direction. 7Founder-authored description hosted by the accelerator; not independent verification of automation quality or a buyer-facing software subscription.
Harper says AI extracts document details, drafts messages and organizes follow-up, while licensed staff and carriers review eligibility and binding decisions; automated marketing does not mean a machine approves coverage alone. 4Privacy sections 3 and 8; stated controls only. No audit of model accuracy, staff review or underwriting delegation.
Before uploading sensitive records, understand how Harper uses them: its privacy policy says applications and loss data help train Harper’s models, while enterprise AI vendors say they do not train foundation models on customer data. 4Sections 2, 7 and 8. Company-reported data handling, not an independent privacy or security certification.
From a Quote to Active Coverage
Harper advertises a 24–48-hour placement time, but it is a company estimate rather than a deadline; ask what approvals and documents remain before relying on a start date. 14February 26, 2026 marketing claim, not independently measured. Current homepage refers to same-week answers, a different milestone; neither is a binding service-level guarantee.
Do not rely on a text message to start or change coverage: Harper’s terms require written confirmation from Harper and the insurer, and text quotes remain subject to underwriting. 3Section 11, effective August 24, 2026. Does not establish a particular insurer’s required payment or signing sequence.
Agency and Insurers
Harper Global Enterprises Inc., doing business as Harper Global Insurance Agency, is the licensed agency. In a 9 December 2025 federal filing, that company identified Harper Group Corp. as its corporate parent. Harper still does not publish terms saying which company contracts with you or how you are charged. 1,4,3Parent relationship from the federal docket entry. The DBA is company-disclosed. No terms of service were found naming the contracting party.
If Georgia placement is relevant, a regulator-linked lookup showed Harper Global Enterprises Inc. active as a resident agency for property, casualty and life when checked Sept. 15, 2026; this is producer authority, not insurer status. 5Actual Sircon consumer inquiry for Georgia, Agency, license 237101; NPN 21740058. The result text and screenshot were inspected. Georgia only; qualification does not establish an offered product.
If you need life or health insurance, look elsewhere for now: Harper’s privacy policy says it does not currently offer either, and its Georgia life qualification does not establish a life product. 4,5Privacy section 2, information not intentionally collected; Georgia agency qualification independently checked. Distinguishes licensing authority from the company’s current product offering.
Confirm the state and line for each location before proceeding: Harper serves US commercial businesses and displays California license 6017784, but the license is not independently verified and no complete product-state availability list was established. 4,2,6California lookup was not available; no adverse licensing inference. Historical state counts in founder marketing are not current regulatory verification.
Market Access and Binding Authority
Harper advertises a network including Progressive, Kinsale, USLI, Atlantic Casualty, James River, GEICO, AIG and Hiscox, plus 165+ underwriters; that count does not mean every insurer will quote your risk. 2,14Marketing logos and dated company statement. No direct appointments or live quoting access independently confirmed; no assignment of an insurer to a product.
Other brokers can ask Harper about wholesale and non-admitted-market access, but its page does not identify the delegated insurers, products, states or limits; this does not make Harper the insurer. 15Selective authority expressly claimed by company, not inferred from AI. No delegation contract or named binding program obtained. Non-admitted means the insurer is not licensed as an admitted insurer in the state of placement.
For a proposal using a non-admitted insurer, ask which broker places the coverage and what disclosures apply in your state. In California, the insurance department explains that surplus-line policies do not receive protection from the state’s insurance guaranty association. 19
Ask for the insurer named on your quote and its current rating: an older Harper article says it uses AAA-rated carriers without naming the rating agency, companies or dated rating records. 18Page dated January 21, 2025, carrier-network assertions. Rating claim withheld as a finding; no rating assigned to Harper or any displayed insurer.
What Coverage Does Harper Offer, and Where?
Businesses can ask Harper about general and professional liability, property, auto, cyber, garage, umbrella, bonds, workers’ compensation, equipment, liquor, malpractice, product liability and BOP; the BOP may combine property and liability. 2,8Advertised product categories across the current homepage, directory and intake. No conclusion that all lines are available together, from one insurer, or in every jurisdiction.
Details That Depend on Your Operation
Security firms can ask about liability for guard actions or professional negligence plus equipment and vehicles; Harper’s page does not name the insurer or policy wording for a specific operation. 12Company industry appetite. No adoption of the page’s broad claims about standard-policy exclusions or satisfaction of licensing requirements.
For a security business, ask whether the proposed wording covers your actual duties, including armed work or use-of-force incidents. 12
Harper says it can classify payroll by employees’ duties and prepare premium-audit information for workers’ compensation; audits can change the premium, and this is not a guarantee that cost stays fixed. 11,19Public payroll and audit service description; not independently tested, and state employee thresholds are deliberately not generalized.
Businesses needing license, permit, contract, dealer, court or fiduciary bonds can approach Harper; review the indemnity agreement because the buyer may have to repay the bond company for claims it pays. 13Company product description. No blanket interpretation of a specific bond or personal guarantee.
Ask for the insurer-specific forms and endorsements before comparing prices; reviewed product pages are summaries and do not establish shared limits, deductibles or exclusions. 8,10,12Scoped search of current coverage directory and representative product/industry pages. No issued policy or private quote reviewed. Absence of a specimen in these sources is not absence of available coverage.
Fees and Referrals
A licensed referral agent may receive 50% of Harper’s commission 60 days after settlement, according to Harper Partners; this is a share of commission, not a discount on your premium. 16Current licensed-agent referral program only. Illustrative dollar amounts not treated as fee quotes; cancellation/nonpayment clawbacks apply. No implication that Spot participates.
If another agent refers you, confirm who will be your ongoing contact: Harper says it owns the account and handles placement, service, renewals and claims, while the referring agent has no service duties. 16,15Distinct advertised programs; not assumed contradictory or contractually identical. Account ownership is the program’s language, not a finding that a buyer cannot change brokers.
Get premium, taxes, fees and financing charges itemized because reviewed Harper pages do not disclose buyer fees or account-specific commission rates; a free partner signup does not mean insurance is fee-free. 16,18,10,3Reviewed referral terms, pricing-transparency article, GL cost FAQ and messaging terms. No hidden fees is marketing, not a zero-fee promise; SMS cost statement applies only to messages.
A useful comparison holds the coverage, limits, deductibles and policy period constant, then separates the insurance price from the cost of arranging or financing it. 19 16
Service, Renewals and Claims
Harper’s portal advertises policy, certificate, payment and application-status access; customers need an invitation and should ask support about features available after sign-in. 17Public entry page viewed and captured without authenticating, requesting an invitation or supplying contact information.
Harper describes policy reviews and renewal reminders, but not a guaranteed renewal price or a commitment to shop every policy; agree on the renewal plan with your team. 18,3Company service statements; no customer service agreement or renewal proposal inspected.
Harper says brokers help with claims documents and carrier communication, but the insurer decides covered losses and payment; advocacy does not guarantee a claim is paid. 18,19Company support description plus CDI glossary insurer definition. No claims file, administrator agreement or independent claims-quality evidence reviewed.
Get the policy-specific notice address and after-hours instructions before coverage starts: reviewed sources do not establish a dedicated claims procedure, and Harper says texts are not for urgent matters. 18,17,3Scoped public-source unknown, not a finding that claims support is unavailable. No assumption that a text to an agent constitutes timely policy notice.
What Should You Confirm in Harper Quotes?
Use the proposal to resolve the details that the public pages leave open:
- Who is arranging and insuring it? Ask for the agency and issuing insurer’s legal names for each coverage, the insurer’s status in your state, and any rating your contract requires. A producer license and an insurer’s financial strength answer different questions. 5 19
- Which markets actually considered your business? Ask which insurers were approached, which returned quotes, and whether placement uses Harper’s direct appointment, a wholesaler or a delegated program. The public marketing does not map those relationships to your account. 14 15
- Does the wording fit the work? Request the forms, limits, deductibles and exclusions. For security operations, confirm the duties covered; for workers’ compensation, confirm payroll and job classifications; for bonds, confirm repayment obligations. 12 11 13
- What is the total cost? Separate premium, taxes, broker or service fees, financing charges and producer compensation. If you came through another agent, ask who receives compensation and who will service the account. 16 19
- What starts coverage, and who handles the next request? Obtain written coverage confirmation, the service contact, renewal responsibilities and policy-specific claims instructions. Do not treat a text exchange or a portal invitation as confirmation that coverage has begun. 3 17
Harper Review Scores for 2026
These averages can combine ratings for different products, locations, and customer groups, including approximate BBB grade conversions. Read each review for its sources, what it covers and how the score is calculated.
Harper Review Score
Review Score
No reviews found
We found no customer star rating for Harper. Its Trustpilot page has 0 reviews, and BBB shows 0 customer reviews and 2 complaints.
Read Harper reviewsHarper Reliability Scores for 2026
Broker. Limited to the licensed agency Harper Global Enterprises Inc., doing business as Harper Global Insurance Agency, acting as a commercial insurance broker. Harper Group Corp., its parent, is described but not separately assessed. A December 2025 federal disclosure links the two.
Harper Broker Reliability Score
This partial Broker Reliability Score covers licensing and authority and how clearly it explains its terms. Those factors make up 45% of the full score, normalized to a ten-point scale. Anything without enough evidence is left out, not scored as zero.
Scored entity unavailable
Sources for Harper
What Are the Closest Alternatives to Harper?
Other providers that list the same coverage lines as Harper.


 5.5/ 10