Spot for Startups

Get quotes from 50+ startup insurance providers with Spot

We get you ready for the customer contract, lease or new hire in front of you, from the first quote to the certificate.

  • Ready when the customer, landlord or investor asks
  • Tech E&O, cyber and liability compared together
  • Keep your broker or switch, with no commissions on premiums
Two founders and an investor talk around a small table with a laptop.

How Spot helps Startups

Send us the insurance request

Forward the customer contract, lease or investor request. Spot reads the insurance clause, compares it with what you carry and tells you what’s missing.

General liability insurance

Orbit Software · Policy review

Policy wording
Coverage limits
Compare with
Contract requirements

Confirm with your broker

Limits, exclusions, and endorsements

Tell us what your company does

Your Spot team collects what you do, where employees work, what data or property you hold and what the customer asked for, and prepares the submission.

Orbit SoftwareOrganized by Spot
Travelers
The Hartford
Chubb

See how each quote handles real problems

Spot runs the same scenarios through every proposal brokers bring back: a missed deliverable, a data incident, downtime and a claim against management.

Chubb
The Hartford
TravelersQuote request

General liability insurance

Coverage limits · Policy terms

Orbit Software

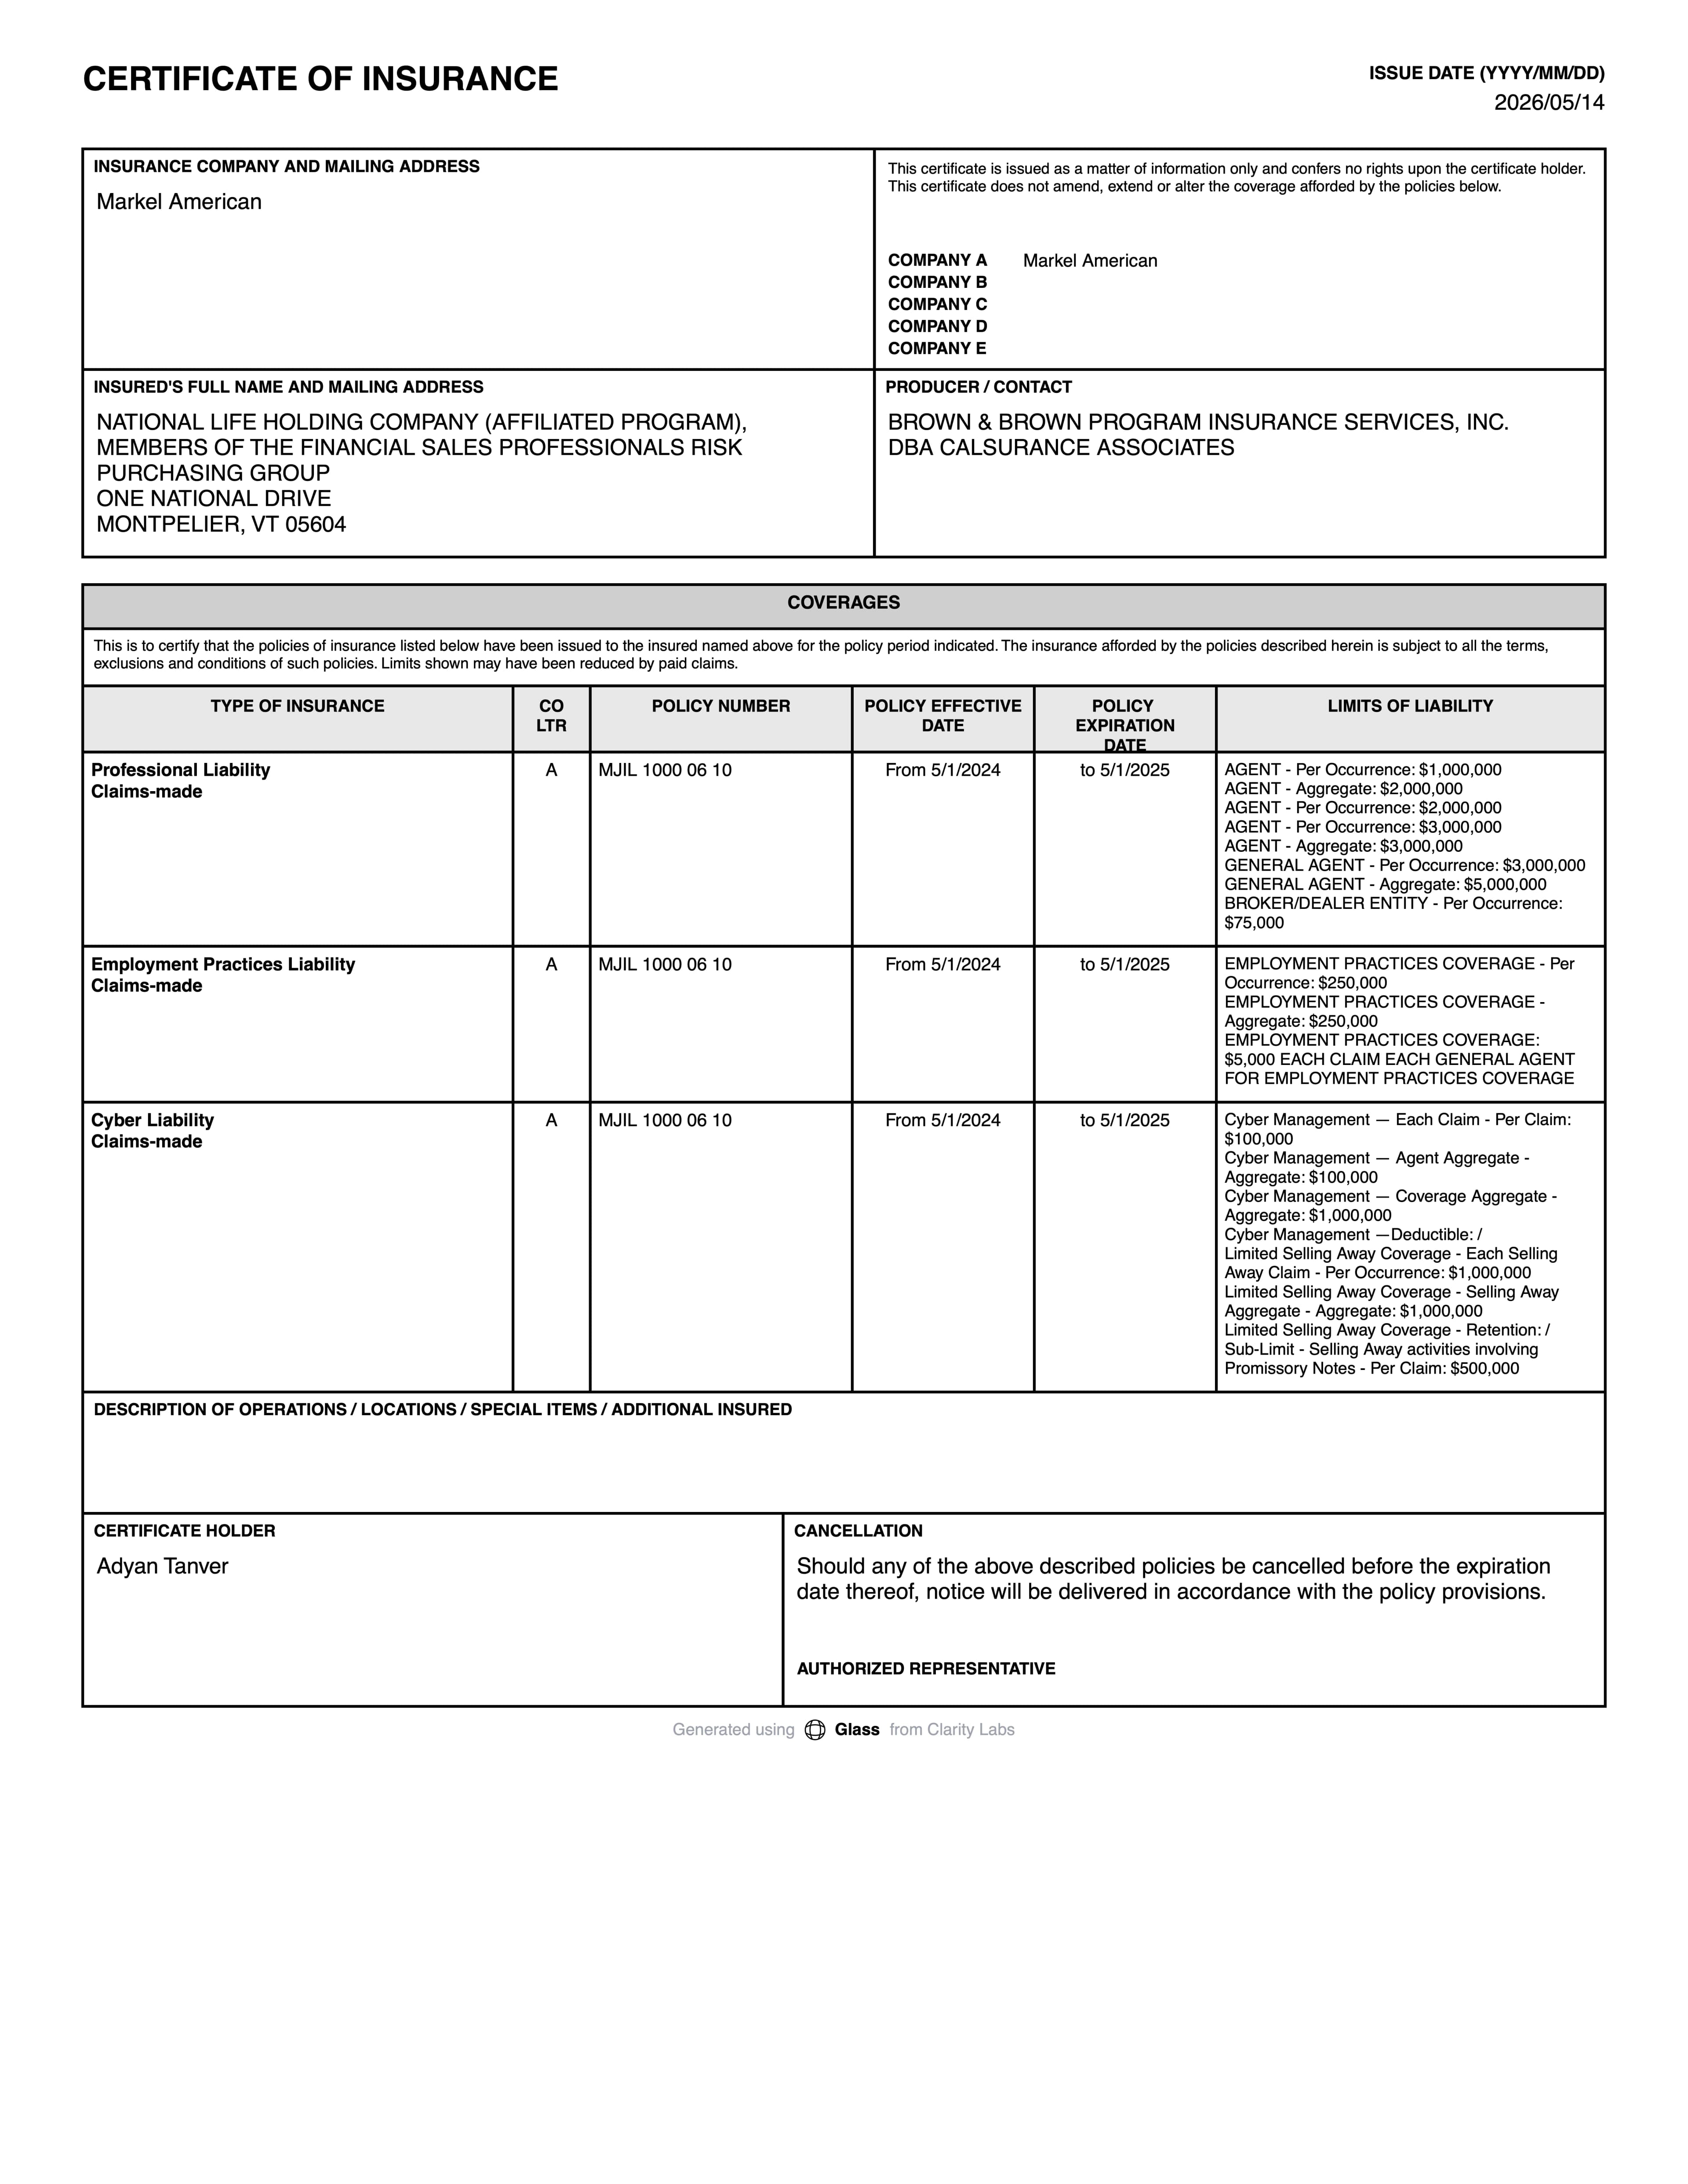
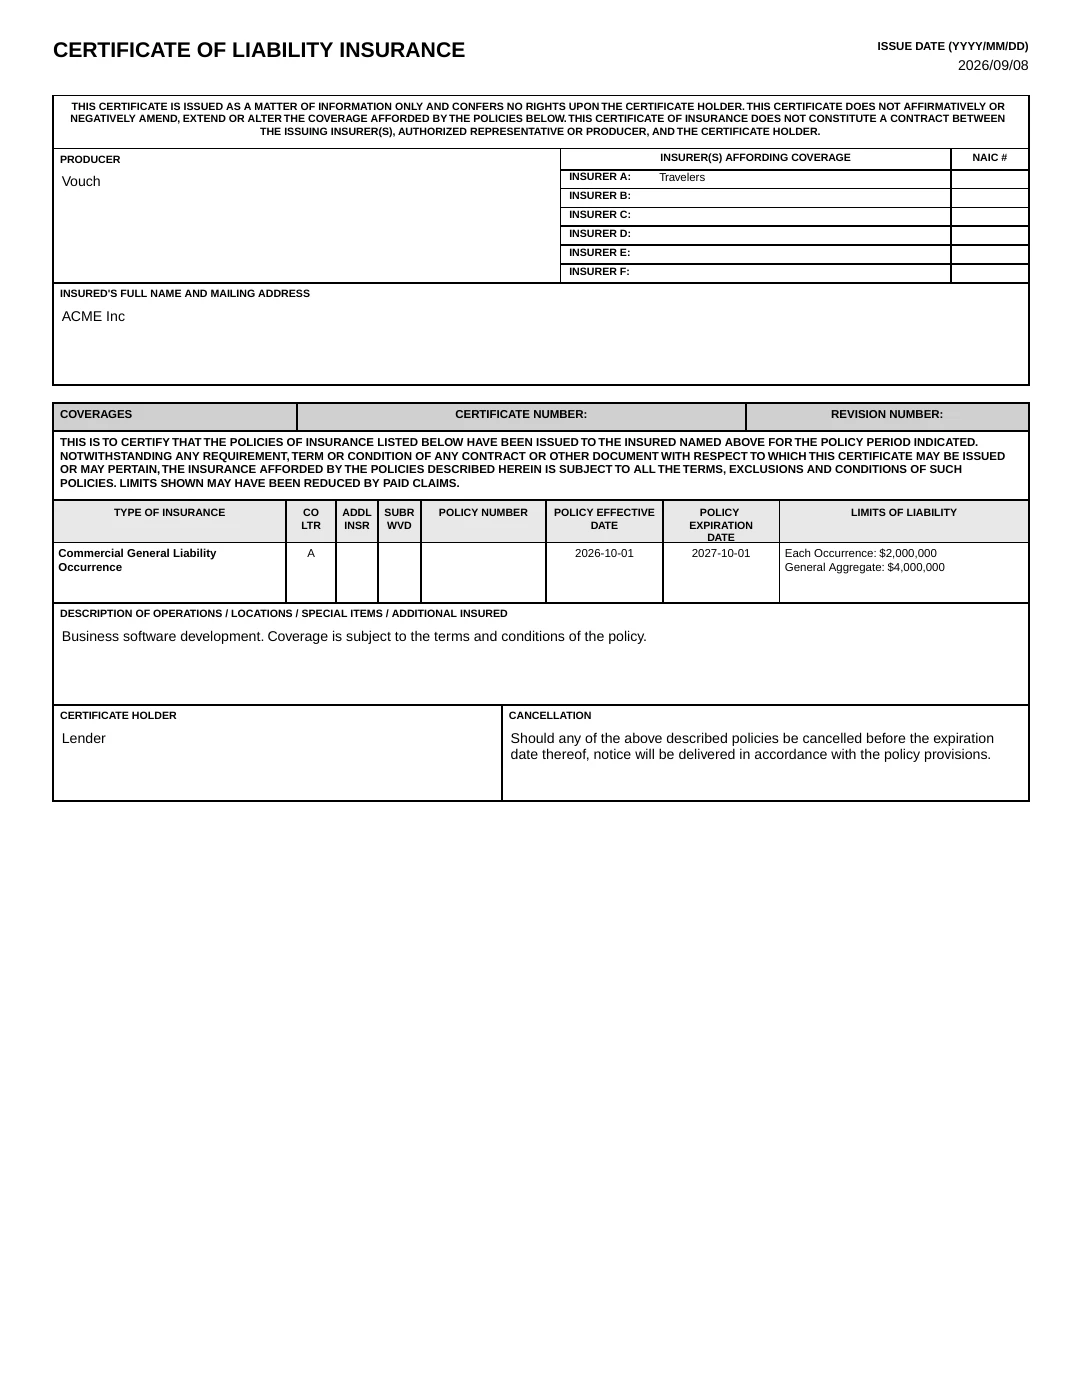
Get your certificate when a customer asks

Post the customer’s request in your shared Slack channel. We get the certificate of insurance ready and, if the customer wants to be named on your policy, ask your broker for the endorsement.

TaylorOrbit Software

Can you help prepare proof of our general liability insurance?

Certificate of insurance

Orbit Software

Ready for your review

How buying insurance works for Startups

  1. 01

    Tell us about your business

    Share what you do, where you work, the policies you have and any contracts that ask for insurance.

  2. 02

    We write up your application

    Spot turns it into an application that describes your business the way insurers need to see it.

  3. 03

    We get quotes from insurers

    Spot handles the procurement, sending it to the insurers and markets that cover businesses like yours and chasing every quote.

  4. 04

    Compare your quotes

    We put the quotes side by side on limits, exclusions and terms as well as price.

  5. 05

    Buy your policy and get certificates

    You choose. Spot places the policy for you, and certificates are ready when a customer or landlord asks.

Startups we help

  • Software and SaaS startups

    An enterprise customer asks for tech E&O and cyber before kickoff.

  • Hardware and product startups

    Pilots, leases and shipped units bring property and liability questions.

  • Remote-first teams

    A hire in a new state raises workers’ compensation questions there.

  • Founders raising money

    A financing discussion or board change brings D&O into view, and if the company depends on one founder, key person life insurance may come up too.

  • Startups offering benefits

    Group health coverage is its own decision, separate from liability insurance, with plan costs and networks to compare.

Insurance Startups usually carry

The policies companies like yours are usually asked for, and when each one comes up.

  • General liability

    Customers or other visitors come to your workspace, or your team performs work at a customer site.

  • Technology errors and omissions (E&O)

    A software, hosted service, integration, or implementation error could cause a customer financial loss.

  • Cyber liability

    Your company holds customer or employee data, depends on its network, or could incur costs after a cyber incident.

  • Directors and officers

    A financing discussion, board change, or investor request raises questions about claims alleging management decisions.

  • Workers’ compensation

    You hire an employee who works remotely or in a state where the company has not operated before.

  • Commercial property

    You sign a lease, keep equipment or inventory at a site, or hold property belonging to someone else.

  • Employee health and benefits

    Employer health benefits give eligible staff access to medical care through a group plan or another employer arrangement. When setting a budget or renewing, compare eligibility, provider networks, employee contributions and total cost.

  • Key person

    Key person insurance pays the business, not the person’s family, when a founder, partner or employee it relies on dies. Disability, overhead expense and buyout funding are separate products to discuss on their own.

Insurers that quote Startups

Get quotes from 50+ startup insurance providers with Spot.

  • AIG
  • Alliance Risk
  • Amelia Risk
  • Aon
  • At-Bay
  • Beazley
  • Berkshire Hathaway Specialty Insurance
  • And many more

When Startups need insurance

  • 01

    A remote customer asks for insurance paperwork

    Match each item in their clause, from entity and coverage to limits and dates, to your policies before you tell them the request is met.

  • 02

    You’re launching a software or hosted service

    Ask how technology E&O defines your services and what it says about missed deliverables and downtime.

  • 03

    You hold customer or employee data

    Ask whether cyber terms address your cloud vendors, response vendors, interruption and waiting periods.

  • 04

    You’re signing a lease or buying equipment

    Schedule the site, improvements, equipment, inventory and property of others at accurate values.

  • 05

    Your first remote hire lives in another state

    Workers’ compensation depends on where each employee works, their duties and payroll, not only where the company was formed.

  • 06

    A financing round or board change is coming

    Ask who would qualify as an insured person and which management claims the D&O form names.

Questions from Startups

Also known as startup business insurance, startup company insurance, tech startup insurance, insurance for startups, venture-backed startup insurance and early-stage startup insurance.

Is there one startup insurance package?

Not really. Most tech startups combine general liability, tech E&O, cyber and workers’ compensation, often with D&O, and add property, benefits or key person cover as they grow. Spot helps you buy what the next contract, hire or round asks for.

When should a startup buy business insurance?

Review it whenever you add a customer, product, lease, asset or employee, and weigh the likely losses against what the company could pay itself. A contract or lease often forces the question, and Spot reads that request with you.

How are tech E&O and cyber different?

Tech E&O addresses service or product errors that cause a customer financial loss; cyber addresses data and system incidents. Spot compares both in one process.

Does fundraising mean I need D&O?

Fundraising alone doesn’t settle it. Check whether the investor, board or financing documents ask for D&O, then ask insurers who would be covered and which management claims apply.

We set up our first policies through a broker. Does Spot replace them?

No. Spot works with that broker as you add coverage for new customers, hires and leases, takes no commissions on premiums, and can help you switch if you outgrow them.

Get insurance off your to-do list.

Get quotes from 50+ startup insurance providers with Spot. Keep your broker or switch, with no commissions on premiums.

Get Started