Spot for Commercial Property Insurance

Get quotes from 40+ commercial property insurance providers with Spot

We get your property quotes, check how each one values your building and stock, and help you buy well before renewal.

  • Valuation, coinsurance and deductibles compared across proposals
  • Flood, earth movement and wear exclusions flagged up front
  • Keep your broker or switch, with no commissions on premiums
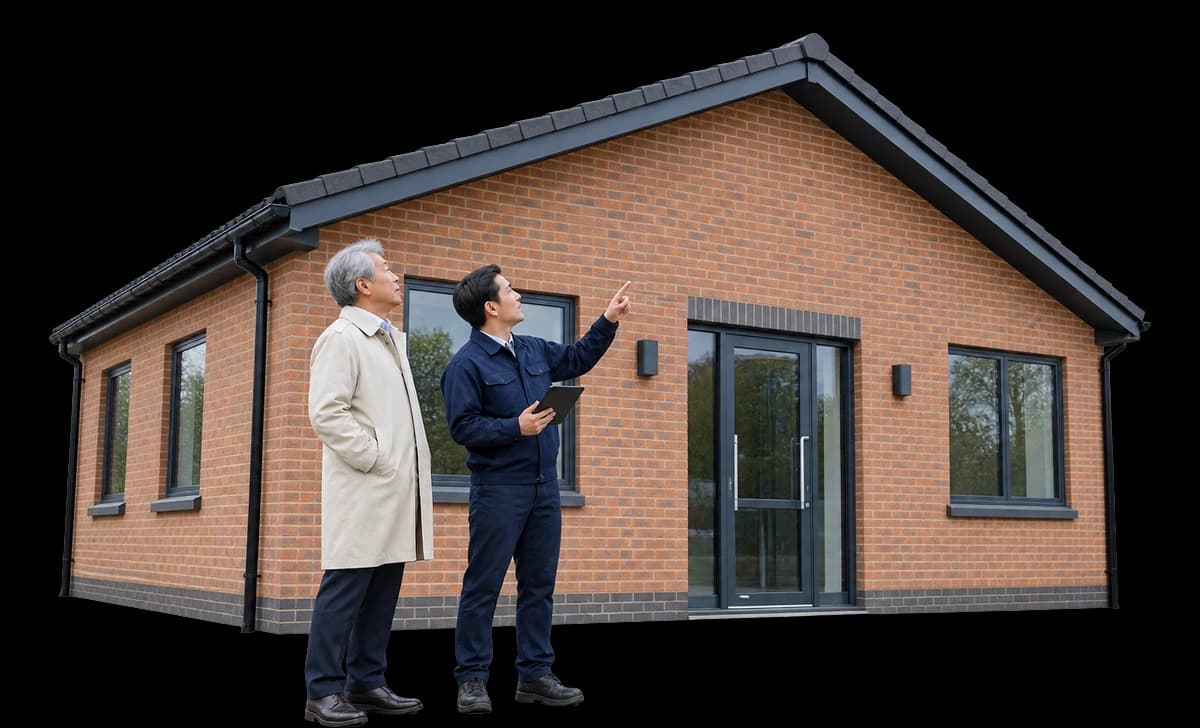
A building owner and a facilities manager look up at the roofline of a small brick commercial building.

How Spot helps you buy Commercial Property Insurance

List every location and what’s in it

Your Spot team collects each worksite, how the business operates, the building and installed equipment, movable items and property held for others, along with your safety, security and maintenance practices.

Juniper PropertiesOrganized by Spot
Travelers
The Hartford
Chubb

See what each quote would pay after a loss

When proposals come back from the market, we line up replacement cost against actual cash value, coinsurance conditions and deductibles, so a lower premium doesn’t hide a smaller payout.

Chubb
The Hartford
TravelersQuote request

Commercial property insurance

Buildings · Business personal property

Juniper Properties

Find out what’s excluded before you buy

Spot checks whether each quote leaves out flood, earth movement or wear and tear, and asks how lost income is treated, since property and business interruption are separate coverages.

Commercial property insurance

Juniper Properties · Policy review

Policy wording
Valuation clause
Compare with
Declared values

Confirm with your broker

Replacement cost or actual cash value?

Update your property values before renewal

Your Spot team keeps your policy and schedules together, brings renewals forward and asks you to update values first, since underinsurance can reduce what a claim pays.

TaylorJuniper Properties

What do we need to request commercial property insurance quotes?

Let’s prepare the information for your broker and compare the terms, not just the price.

Commercial property insurance policy

Valuation · Deductibles

How buying Commercial Property Insurance works with Spot

  1. 01

    Tell us about your business

    Share what you do, where you work, the policies you have and any contracts that ask for insurance.

  2. 02

    We write up your application

    Spot turns it into an application that describes your business the way insurers need to see it.

  3. 03

    We get quotes from insurers

    Spot handles the procurement, sending it to the insurers and markets that cover businesses like yours and chasing every quote.

  4. 04

    Compare your quotes

    We put the quotes side by side on limits, exclusions and terms as well as price.

  5. 05

    Buy your policy and get certificates

    You choose. Spot places the policy for you, and certificates are ready when a customer or landlord asks.

Is Commercial Property Insurance right for you?

  • Building owners

    Your building and the equipment installed in it need to be listed apart from everything that moves.

  • Tenants with equipment and inventory

    Furniture, computers, tools and stock are listed apart from the building, and property you hold for customers has to be identified too.

  • Multi-location businesses

    List every worksite in the submission, not only headquarters, so each proposal shows which locations it insures.

  • Businesses with equipment that travels

    Property that moves between sites may need inland marine or floater coverage, which is a separate conversation from your premises policy.

How Spot helps different industries with Commercial Property Insurance

What each industry usually faces, and where Spot fits in.

  • Agriculture

    You lease a lab, workshop, storage site, or keep company-owned equipment and inventory at a farm.

  • Analytics

    You lease an office or buy servers, test devices, or other analytics equipment.

  • Apparel and Cosmetics

    Seasonal stock, samples, packaging, or production equipment accumulates at a studio or warehouse.

  • Aviation and Space

    You lease a lab, hangar, or integration facility with installed equipment, prototypes, or customer-owned property.

  • B2B

    You sign a lease or buy equipment, inventory, computers, or other property the company could not readily replace.

  • Climate

    You own equipment or inventory at a site, or need to understand flood protection for a business building or its contents.

  • Construction

    You lease a shop or storage space, own a building, or keep tools, materials, or inventory at a scheduled location.

  • Consumer Electronics

    Prototypes become finished stock, test rigs, tooling, or equipment at a lab or warehouse.

  • Consumer Brands

    You lease space or keep stock, fixtures, production equipment, or samples at a business location.

  • Media and Content

    You lease a studio or keep editing equipment, archive media, or production property at a business location.

  • Defense

    A prototype or test unit remains at your lab, moves to a customer site, or is held alongside customer- or government-furnished property.

  • Diagnostics

    You lease a lab, install analyzers or freezers, or keep samples, inventory, or customer property at a site.

All industries

Insurers we get Commercial Property Insurance quotes from

Get quotes from 40+ commercial property insurance providers with Spot.

  • AIG
  • Alliance Risk
  • Aon
  • Beazley
  • Berkshire Hathaway Specialty Insurance
  • CFC
  • Chubb
  • And many more

When to get Commercial Property Insurance

  • 01

    You bought or leased a building

    Read the lease to see whether you or the landlord insures the building, then set your building and contents limits to match.

  • 02

    You bought expensive equipment

    Update its value, and if it travels between sites, ask separately about inland marine or floater coverage.

  • 03

    You added a location

    Tell your Spot team before you move in, so the new worksite and what’s in it can be added to your schedule.

  • 04

    Your rebuilding costs went up

    Underinsurance can reduce what the policy pays. Check your values against any coinsurance condition before a loss tests them.

  • 05

    Your property renewal arrived with last year’s values

    Update the values first, then compare valuation terms and deductibles across the market.

Commercial Property Insurance questions

Also known as business property insurance, commercial building insurance and commercial real estate insurance.

Our broker has placed our property for years. Can we keep them?

Yes. Spot works with your existing broker on the schedule and the proposals, and takes no commissions on premiums. If you want a broker who places more property like yours, we can help you switch.

What does commercial property insurance cover?

Business property insurance can protect your buildings, equipment, furniture and inventory against physical damage from covered events. What it pays turns on the covered property, the covered causes of loss and the policy’s exclusions and endorsements.

Does property insurance replace lost income?

Not by itself. Property coverage addresses physical assets, while business interruption addresses lost income after a covered event, so ask for income coverage if you need it.

What is coinsurance?

It’s a condition in some property policies under which underinsurance can reduce what the policy pays. Spot asks whether your values meet it before you bind.

What do I need to get a property quote?

Your Spot team needs each worksite, how your business operates, your building, installed equipment and contents, any property you hold for others, your safety and maintenance practices, and your current policy if you have one.

Get insurance off your to-do list.

Get quotes from 40+ commercial property insurance providers with Spot. Keep your broker or switch, with no commissions on premiums.

Get Started