What Is Coverdash Insurance?
Coverdash’s coverage options, carrier access, buying process, policy fees and automatic-renewal terms explained.
Coverdash is an insurance brokerage and online platform for small businesses, startups and e-commerce sellers. You can compare quotes, buy policies and manage coverage through its website or a partner’s embedded insurance service. 4,8,2
Its offerings range from general liability and property insurance to technology errors and omissions (E&O), management liability and specialty products for transactions, transport and other business risks. 3
Pros And Cons
Pros
- Multiple-carrier shopping with an advisor available. Coverdash describes side-by-side quotes and access to an advisor during purchasing and policy management. That gives buyers a way to compare available placements and ask for help interpreting them. The advertised carrier panel is broader than the set any one applicant is guaranteed to see. 1 8
- Coverage beyond a basic small-business package. The catalogue separately lists technology E&O, directors and officers (D&O) Side A, fiduciary liability, product recall and transactional risk. A growing business can ask about those specialized needs alongside its ordinary liability and property policies. 3
- Useful certificate tools for recurring requests. The documented workflow can combine multiple policies in a certificate and offers an e-commerce marketplace template. Those features matter when customers, landlords or marketplaces repeatedly ask for proof of insurance. 13
- Policy information and service share an account. Coverdash’s public login page describes access to applications, policy details, certificates, billing requests and an account manager. This gives buyers a documented place to return after purchase. 11
Cons
- A purchased policy carries an additional, nonrefundable technology fee. Free quoting or software access does not mean a fee-free purchase. Coverdash does not publish the Technology Access Fee amount in its compensation disclosure, so the total needs to be checked at checkout. 5
- Automatic renewal can include a higher premium without fresh consent. Eligible policies can renew with increases of up to 20% when material coverage terms stay the same. Buyers who require approval for every renewal need to use the opt-out process. 6
- The public pages leave important policy details to the quote. The reviewed product pages do not identify a complete insurer/form schedule. A coverage name or the number of available carriers cannot settle exclusions, deductibles or contract compliance. 3 16 17
- Assisted certificates may require lead time. The certificate guide allows up to two business days for an agent-assisted request. A buyer with an urgent contract deadline should distinguish that route from self-service generation. 13
How It Works
Applying And Buying
Coverdash’s public application begins with an email-address field. Its FAQ says to have your business name, address, industry, annual revenue and employee count ready; it describes online quote comparison and purchasing, with same-day coverage for most policies. 10,4
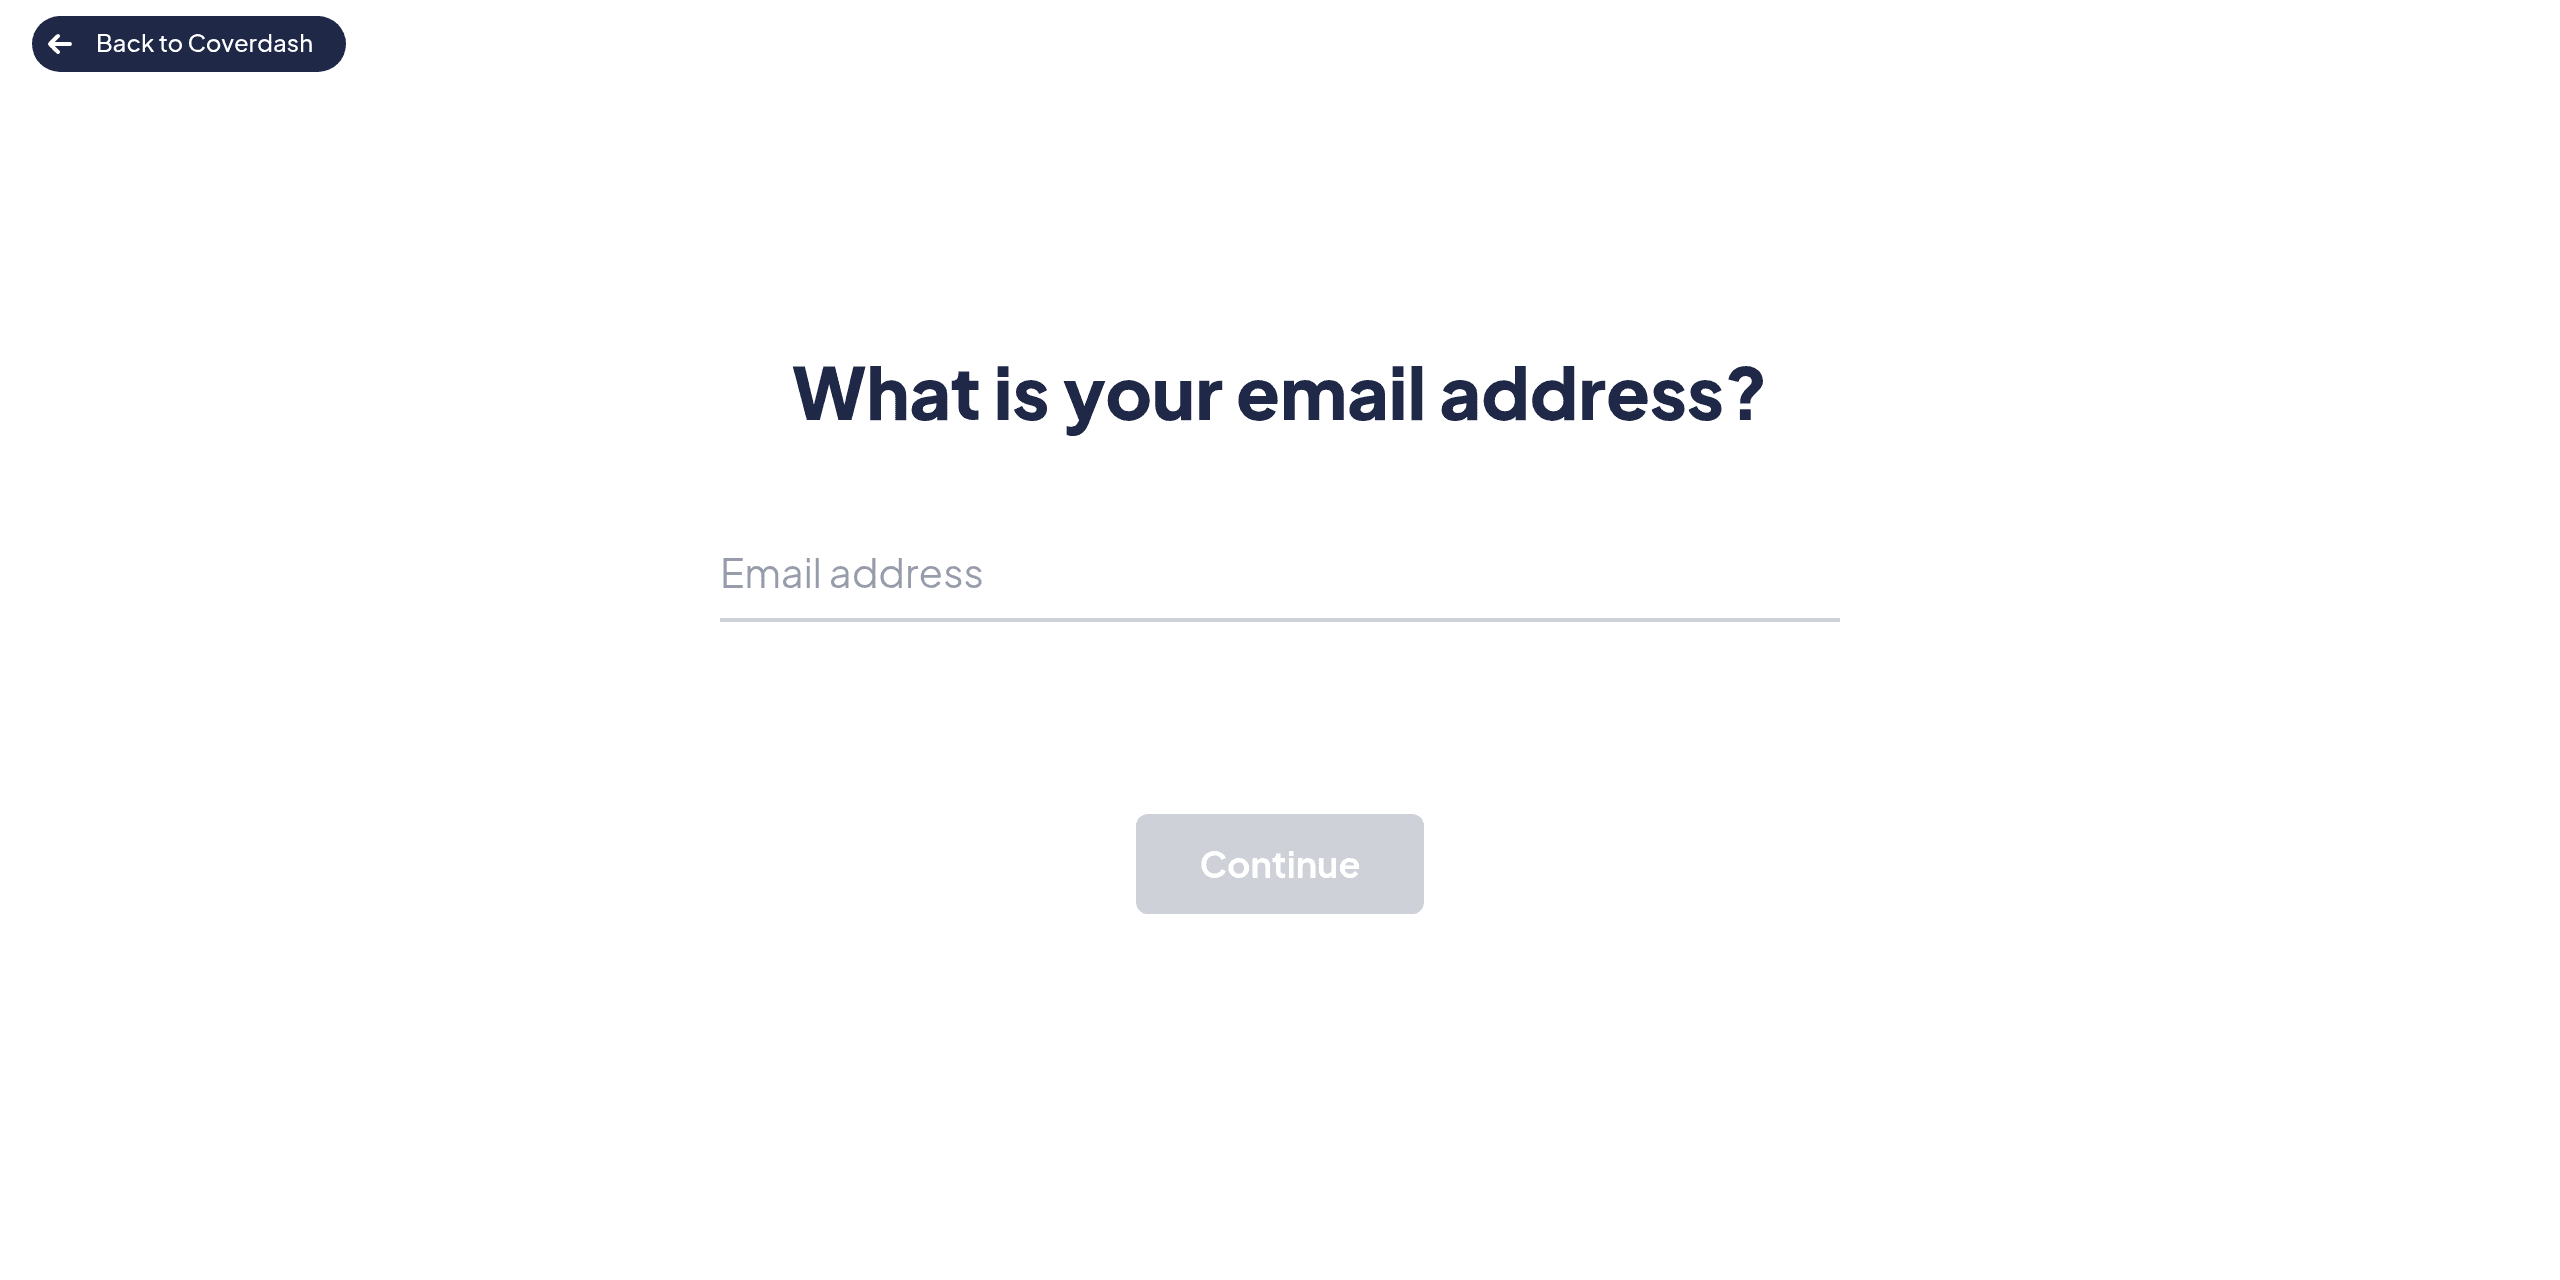
The first question in Coverdash’s quote application
The FAQ says payment follows choosing and binding a policy, but the terms allow collecting payment before binding and later insurer rejection or repricing. Confirm the effective date and binding confirmation before relying on coverage. 4,2
Using the brokerage service means appointing Coverdash as broker or agent of record and working exclusively with it for those services unless otherwise agreed. 2
For an existing policy, clarify which placements a broker-of-record change covers before authorizing it. That designation is part of the brokerage relationship described in the terms. 2
The Broker, The Platform And The Insurer
Coverdash’s terms name Coverdash, Inc. and Coverdash Insurance Services, LLC; the LLC provides the insurance brokerage service. It arranges coverage with insurance companies and says it does not underwrite policies. 2
A partner can put Coverdash’s quote and policy-management experience inside its own website or software. Coverdash’s terms assign insurance solicitation and service to Coverdash rather than the host platform. 9,2
Coverdash advertises access to more than 40 carriers and displays names including Chubb, Travelers, Hiscox and Nationwide. It does not promise that every applicant will receive quotes from that entire panel. 1,8
Nationwide’s own agency directory lists Coverdash Insurance Services and links to coverdash.com, independently supporting that carrier relationship. The listing does not identify the insurer or terms for a particular Coverdash quote. 15
Ask which insurance company will actually issue each policy. The carrier names shown on a website do not identify the legal insurer on your particular placement; Coverdash’s terms say coverage is provided by various insurance companies under the applicable policy. 2
Coverage And Availability
The Full Coverage Catalogue
The following are marketed offerings, including specialist options. They are choices to investigate with Coverdash, not a list of protections included in every policy. 3
Coverdash’s core catalogue lists general liability, business owner’s policies, commercial property and workers’ compensation. 3
Professional and management offerings include professional E&O, technology E&O, lawyers professional liability, management liability, directors and officers, standalone D&O Side A, a D&O and employment-practices bundle, employment practices, fiduciary liability, media liability and transactional risk. 3
The cyber and crime group lists cyber insurance, commercial crime, and kidnap and ransom. 3
Property specialties include inland marine, equipment breakdown, builders risk, flood, wind and hail, earthquake, property difference-in-conditions insurance and terrorism. 3
Transport offerings include commercial auto, automobile physical damage, garagekeepers, motor truck cargo, non-trucking liability and ocean marine. 3
Coverdash also markets umbrella, excess liability, product liability, product recall, pollution, liquor liability, special-event, abuse and molestation, workplace violence, global-package, business travel accident and surety products. 3
Its bond page lists license and permit, contract, court, and fidelity bonds. It describes fidelity protection for client losses caused by employee dishonesty. 21
How The Coverage Pieces Fit Together
Coverdash describes a business owner’s policy as combining general liability, property and business-interruption protection. Its FAQ says eligibility depends on industry, location and premises, and some higher-risk businesses may need separate policies. 16
For a business with premises or stock, the distinction is whether you are arranging liability alone or also insuring your own assets and lost income. Ask what event must cause the interruption, and which property and locations the proposal actually includes. 16
Coverdash separately markets technology E&O for financial harm alleged from technology work and cyber insurance for breaches and attacks. Its Tech E&O FAQ says cyber is bundled in some policies, but not all. 17,22
For a software business, check both the client’s loss from a failed service and your own costs of responding to a breach. The same incident can raise both questions; a combined product label does not answer them. 17 22
Coverdash describes D&O as the core of management liability, with options for employment practices, fiduciary and crime protection. It also markets standalone Side A for individual directors and officers when the company cannot indemnify them—pay their defense or liability costs. 18,19
Its transactional-risk offering includes representations and warranties insurance for acquisition-related breaches, plus tax and contingent-liability products. 20
The auto and transport names also describe different exposures. Coverdash’s garagekeepers page concerns customer vehicles left in your care; its cargo page concerns transported goods; non-trucking liability concerns truck use outside dispatch. Ask for the applicable combination instead of treating all three as commercial auto. 26 24 25
Availability And Policy Wording
Coverdash publishes producer-license numbers for all 50 states and Washington, D.C. Current regulator status was not independently established in this research, and the list does not establish availability of each product in each state. 7,2
The reviewed product catalogue does not provide a complete product-by-state eligibility table. Its global-package page markets coverage for international operations without a country-by-country placement schedule. 3,27
No insurer-specific specimen forms or complete carrier-by-product schedule were found in the reviewed coverage pages. The product descriptions do not establish your exclusions, deductibles, limits or claims-reporting requirements. 3,16,17,18,2
Service And Compensation
Managing Coverage And Certificates
The public sign-in page describes resuming applications, reviewing policies and billing requests, downloading certificates and contacting an account manager. Coverdash’s FAQ directs customers through their account to request coverage changes or cancellation. 11,4
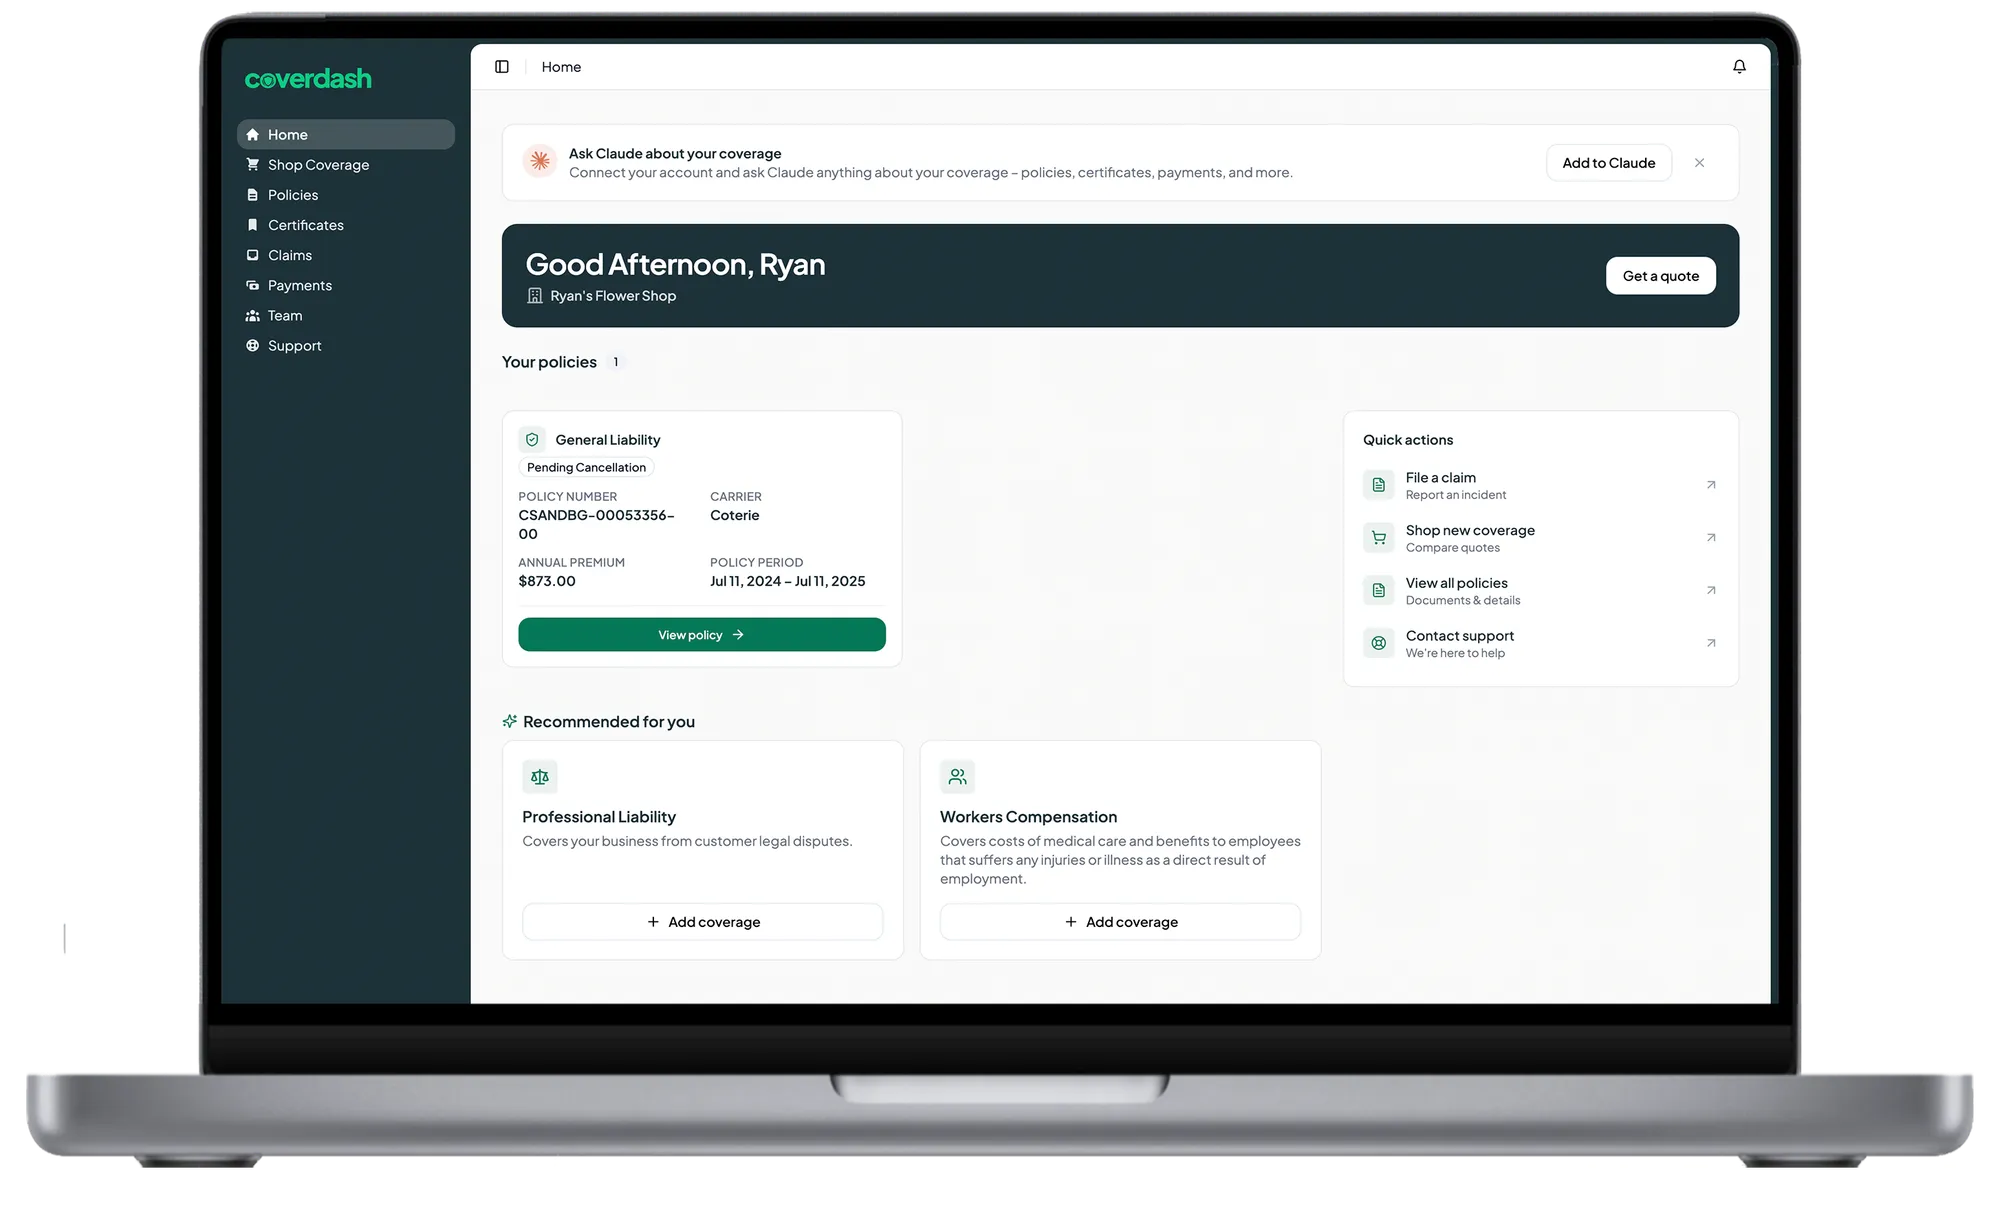
Coverdash’s dashboard demonstration, using sample policy information.
Coverdash’s certificate guide describes self-service PDF certificates, selection of multiple policies and an e-commerce marketplace template. It says requests for agent assistance can take up to two business days. 13
For additional-insured requests, distinguish the certificate from the actual policy change. Coverdash’s terms say a certificate itself neither creates coverage nor makes its holder an additional insured. Ask whether the needed endorsement—the document changing the policy—has been issued. 2
Fees And Payment Plans
Coverdash discloses a Technology Access Fee on each purchased policy, in addition to policy charges, and calls it fully earned and nonrefundable. The disclosure does not give its amount. 5
Coverdash may receive insurer or payment-servicer commissions, performance-related contingent or supplemental commissions, and negotiated client fees. It also discloses affinity-referral and administrative-service income. 5
Ask for an itemized total separating premium, taxes, policy fees and financing costs. A commission paid to the broker and a fee charged directly to you are different parts of that discussion. Coverdash invites customers to ask their agent about compensation for their placement. 5
Coverdash’s help center identifies Ascend as its payment and premium-finance partner. It explains that financing pays the annual premium upfront while the customer repays in installments. Confirm the current lender, interest and fees in the payment agreement. 12,6
Monthly financing spreads payment of an annual policy; it is not evidence of a month-to-month insurance contract. Ask about the total repayment, cancellation balance and any refund calculation before selecting installments. 12
Automatic Renewals
For policies whose billing and premium payment it facilitates, Coverdash’s renewal authorization permits automatic renewal with a premium increase of up to 20% if no material coverage terms change. Larger increases or material changes require renewed consent. 6
The authorization permits necessary renewal paperwork, including a new premium-finance agreement. Customers can opt out or request cancellation through the dashboard, with processing time; the insurer still decides whether to renew. 6
The 20% threshold is a consent rule, not a ceiling on the insurer’s renewal price. Check the renewal offer even if the current payment method will carry forward. 6
Reporting A Claim
Coverdash says customers can start a claim through their account or support team, which connects them with the insurer and guides the process. Its help article directs customers to Claims, then New Claim. 4,14
This describes help reporting and following a claim, not a promise that Coverdash pays it. Obtain the insurer’s notice instructions and applicable deadlines with the policy, including any emergency cyber-response contact. 2 22
What To Confirm In A Quote
- Markets approached and issuing insurers. Which carriers actually considered your business, which declined, and which legal insurer appears on each proposed policy? If a contract requires a particular rating or admitted insurer, verify that requirement against the proposed entity. 1 15
- The actual forms and coverage combination. Request the forms and endorsements, limits, deductibles or retentions, exclusions and reporting terms. For Tech E&O, confirm whether cyber is included; for management liability, confirm which optional parts and Side A protection are present. 17 18 19
- Locations and eligibility. Confirm the proposed product for each state, business activity and overseas exposure. A producer-license list and a global-package description do not provide those account-specific answers. 7 27
- Total cost and exit cost. What is the Technology Access Fee per policy, what other charges apply, and what remains payable after cancellation? If financing is offered, request its separate agreement and repayment schedule. 5 12
- Renewal control. Does Coverdash facilitate billing on this policy, does automatic renewal apply, and how will an opt-out be acknowledged before the term ends? 6
- Proof and service deadlines. For an urgent certificate, can the request be completed through self-service, or does an agent need to handle it? Confirm policy changes separately from the certificate and keep the insurer’s claims-notice instructions. 13 14
Sources
Coverdash official website
- Business Insurance Online Instantly. Coverdash; Who do we insure?; How it works; carrier-logo strip; Our product policy and certificate demonstrations. Accessed 2026-09-15.
- Terms And Conditions. Coverdash; Sections 1–2 (entities, broker-of-record and exclusivity), 10 (policy controls coverage), 12–13 (producer role and payment before binding), 15–17 (no underwriting; certificates; summaries), 32 (automatic payments). Accessed 2026-09-15.
- Coverage Hub. Coverdash; Core Business; Professional & Management; Cyber & Crime; Property & Catastrophe; Auto & Transport; Excess & Specialty. Accessed 2026-09-15.
- Frequently Asked Questions. Coverdash; Getting a quote & buying coverage; Claims & certificates; Billing & managing your policy; About Coverdash. Accessed 2026-09-15.
- Compensation Disclosure. Coverdash; Commissions; Contingent Commissions; Technology Access Fee; Supplemental Commissions; Client Fees; Affinity Partner Revenue; Other Compensation. No numerical Technology Access Fee schedule. Accessed 2026-09-15.
- Policy Auto-Renewal Authorization. Coverdash; Automatic Renewal; Renewal Documentation; Renewal Pricing Conditions (20% threshold); Payment; Right to Opt Out or Cancel; No Guarantee of Coverage. Accessed 2026-09-15.
- Licenses. Coverdash; AK–WY license list, including DC and separate NY broker/agent entries. Accessed 2026-09-15.
- About Us. Coverdash; How Coverdash Works: direct and embedded channels; Our Investors. Accessed 2026-09-15.
- Partner With Coverdash. Coverdash; How It Works; What’s Included (white-labeled UI); The Product. Describes embedded quoting, binding and policy management. Accessed 2026-09-15.
- Get A Quote. Coverdash; Embedded quote application, first question after Get Started: email address. Accessed 2026-09-15.
- Customer Sign In. Coverdash; Customer Access and Customer Sign In panels. Accessed 2026-09-15.
- What Is A Premium Finance Agreement? Who Is Ascend?. Coverdash Help Center; 17 January 2023 article: premium financing and Ascend payment collection. Accessed 2026-09-15.
- How Do I Get A COI?. Coverdash Help Center; Article dated 18 July 2024, steps 2–8: Certificates tab, self-service versus agent request (up to two business days), marketplace template, policy selection and PDF download. Accessed 2026-09-15.
- How Can I File A Claim?. Coverdash Help Center; 17 January 2023 article: Claims tab and New Claim instructions. Accessed 2026-09-15.
- Coverdash Insurance Services Agency Listing. Nationwide; Agency Website; Products; Our Insurance Products: Business Insurance. Accessed 2026-09-15.
- Business Owner’s Policy. Coverdash; Product introduction and coverage cards; FAQ: BOP versus general liability and Who qualifies (industry, location and premises). Accessed 2026-09-15.
- Tech E&O Insurance. Coverdash; Product introduction; FAQ Does Tech E&O include cyber coverage?. Accessed 2026-09-15.
- Management Liability. Coverdash; Introduction: D&O core with optional employment, fiduciary and crime protection; Types of Coverage. Accessed 2026-09-15.
- Directors & Officers Side A. Coverdash; Introduction; Non-indemnifiable claims; FAQs distinguishing standalone Side A from other D&O. Accessed 2026-09-15.
- Transactional Risk Insurance. Coverdash; Introduction; Reps and warranties, tax liability and contingent liability offering cards. Accessed 2026-09-15.
- Surety Bonds. Coverdash; Types of Coverage: license/permit, contract, court and fidelity bonds; FAQ on reimbursement to surety. Accessed 2026-09-15.
- Cyber Insurance. Coverdash; Product introduction, Types of Coverage and Cyber Insurance FAQs. Accessed 2026-09-15.
- Commercial Auto. Coverdash; Product introduction and four coverage cards; hired and non-owned auto appears as optional coverage in FAQ, not a separately catalogued product. Accessed 2026-09-15.
- Motor Truck Cargo. Coverdash; Product introduction; Types of Coverage describes freight in transit. Accessed 2026-09-15.
- Non-Trucking Liability. Coverdash; Product introduction and FAQs concerning personal use outside dispatch. Accessed 2026-09-15.
- Garage Keeper’s Liability. Coverdash; Product introduction; Types of Coverage: customer vehicle damage. Accessed 2026-09-15.
- Global Package. Coverdash; Product introduction; Types of Coverage: international liability, foreign property, business travel and local compliance. Accessed 2026-09-15.