What Is Pie Insurance?
Pie Insurance’s coverage, carrier roles, quote process, payment fees, premium audits and claims service explained.
Pie Insurance is a small-business commercial insurance group whose producer, Pie Insurance Services, sells and administers policies. Its affiliated carriers write workers’ compensation, while selected other products are offered through outside carrier partners. 2,5,3,7,8,9,10
Workers’ compensation is Pie’s core public offering. The current catalogue also supports requests for a business owner’s policy (BOP), cyber, general liability and professional liability/errors and omissions (E&O), although those products use outside carrier partners and carry less public detail about insurers and state availability. 3 5 8
Pros And Cons
Pros
- Businesses can start directly or use an agent. Pie offers a public workers’ compensation quote flow and separately supports appointed agencies. That gives a buyer a self-service starting point without removing the option to work through an insurance professional. 2 6
- The account covers recurring policy tasks. Pie documents online access to policy details, forms, state posters, endorsements and certificates, including instant and custom certificate routes. Those tools can help when a customer, landlord or regulator asks for proof or documents after purchase. 15
- Several payment schedules are published. Annual, semi-annual, quarterly and monthly choices let a business compare cash-flow timing, while pay-as-you-go ties payments to reported payroll and requires no initial deposit. Eligibility and the full cost still need to be checked in the quote. 17 18
- The affiliated carrier group has a current independent financial-strength opinion. AM Best affirmed Pie Casualty Insurance Company’s pooled A- rating with a Stable outlook in April 2026. This speaks to the rating agency’s view of financial strength, not the wording or outcome of any claim. 22
Cons
- Public availability information does not fully agree. Pie’s dedicated state page and AM Best say workers’ compensation reaches 40 states and Washington, D.C.; Pie’s homepage and January 2026 release still say 39 states plus D.C. The state-page selector and claim-handler count add further ambiguity, so a multistate buyer should verify every location. 11 1 13 21
- The broader product menu needs a live check. Pie still displays commercial auto in navigation and on the claim page, but its own FAQ says new submissions and renewals ended. BOP, cyber, general liability and E&O pages invite quote requests without publishing a current carrier or state matrix. 14 7 8 10 9
- Workers’ compensation pricing is not final until audit. The initial premium uses estimated payroll, and the required annual audit uses actual records. Growth, classification changes or uninsured subcontractors can therefore change the amount due after the policy term. 19
- Some transaction costs require special attention. Pie publishes a 3% credit-card fee for most new single-state workers’ compensation policies and charges for waiver-of-subrogation requests without a public dollar schedule. Ask for these separately from premium and taxes. 17 16
- The advertised savings figure needs context. Wisconsin’s insurance regulator recorded that Pie Insurance Services agreed in 2024 to add a disclaimer to its “save up to 30%” claim after allegations of misleading advertising. Pie’s current pages say individual savings vary and the discounts are unavailable on Wisconsin workers’ compensation policies. 25 3
How It Works
Starting A Workers’ Compensation Quote
A small business can start a workers’ compensation quote on Pie’s website or work through an insurance agent; appointed agencies use a separate partner portal. 2,1,3
The live direct quote starts with the business ZIP code. Pie’s workers’ compensation page says applicants also need their name, business name, annual payroll and class-code information. 6,3
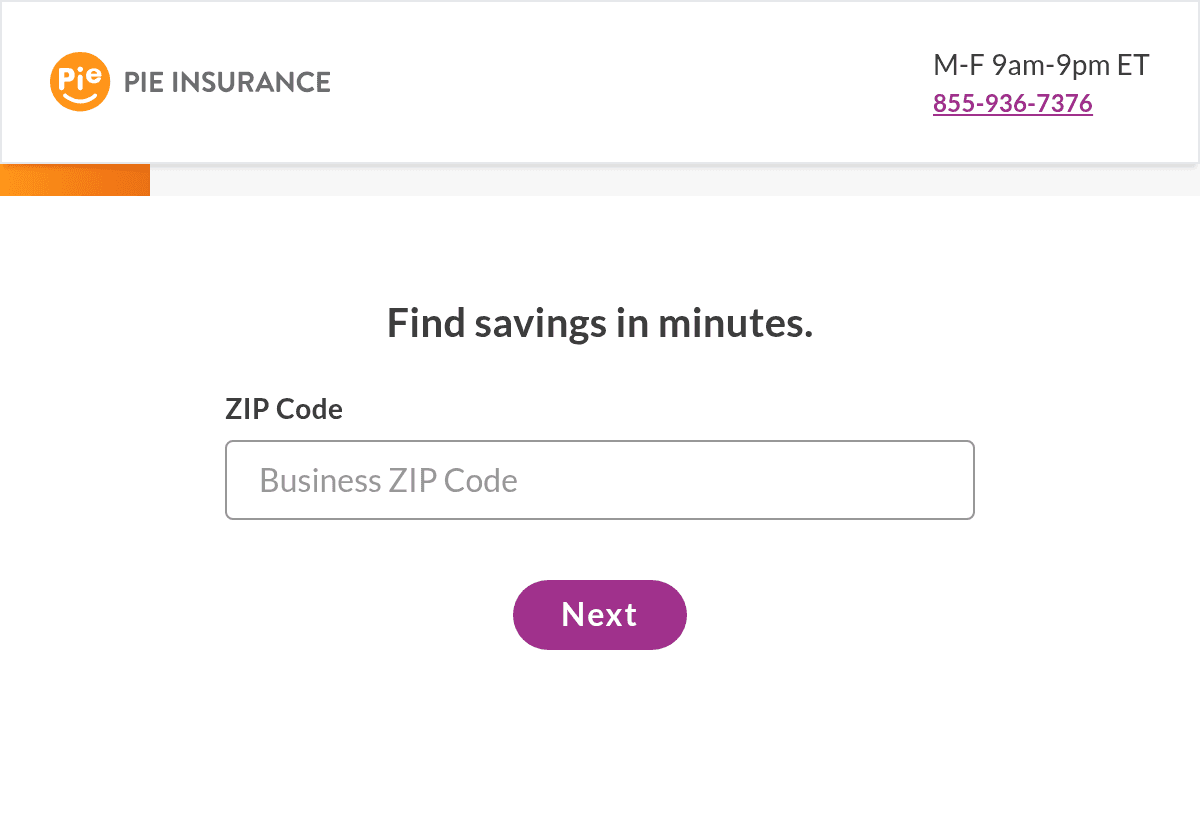
The first step of Pie’s direct quote flow, inspected without entering information or advancing.
Pie advertises an online workers’ compensation quote in about three minutes, while expressly stating that individual quote times vary. This is a company claim and does not establish how long underwriting or binding will take for a particular risk. 3,1
A fast first decision is not the same as a bound policy. Ask what additional underwriting information, signatures and payment are required, and when the quoted coverage would actually take effect. 4
The Producer, The Insurers And The Parent
Pie identifies Pie Insurance Services, Inc. as the licensed producer that sells and administers policies; its legal page publishes state licenses but is not a substitute for a current regulator lookup in the buyer’s state. 5,25
Pie says workers’ compensation is underwritten by The Pie Insurance Company (NAIC 21857) and affiliates. AM Best says Pie began writing all of that business through The Pie Insurance Company and Pie Casualty Insurance Company (NAIC 10997) on January 1, 2024. 5,22,23,24
Pie Group Holdings, Inc. owns the public website and is the regulator-listed parent of Pie Casualty Insurance Company. AM Best identifies the rated carrier group as Pie Insurance Group. 4,24,22
This means the Pie brand can appear in several roles. The producer handles the sale and administration, while the insurer named on the declarations assumes the policy obligation. The holding company owns group businesses but is not a substitute for the issuing insurer on a claim. 5 24
AM Best affirmed Pie Casualty Insurance Company’s pooled A- (Excellent) financial strength rating with a Stable outlook, effective April 24, 2026. A rating is an opinion of insurer financial strength, not a guarantee that a claim is covered or paid. 22
Coverage And Availability
The Current Coverage Catalogue
Current direct offering pages support workers’ compensation, business owner’s policy, cyber, general liability and professional liability/E&O. The non-workers’ compensation pages describe typical protection; the issued policy and endorsements determine actual coverage. 3,7,8,10,9,4
- Workers’ compensation: Pie’s affiliated carriers write the program. The product page describes medical, wage, disability and death benefits in general terms; state law and the issued policy decide the actual benefits and employer obligations. 3
- Business owner’s policy: Pie describes a package that can combine property, liability and business interruption coverage. Those components should not be treated as separately included until the quote and forms say so. 7
- Cyber: Pie’s page discusses first-party response costs and third-party liability, says policies vary and offers access through carrier partners. Confirm which parts are present, including incident response, ransomware, business interruption and liability terms. 8
- General liability: The public description lists bodily injury, third-party property damage, reputation harm, products liability and advertising injury as typical categories. The page does not establish the limits, exclusions or insurer on a proposed policy. 10
- Professional liability/E&O: Pie uses the two names for one offering aimed at claims arising from advice or services. Obtain the proposed definition of professional services, retroactive date and reporting terms. 9
Pie describes commercial property and business interruption as parts of a BOP, and products liability as part of general liability. These components are not separately marketed policies. 7 10
Workers’ Compensation Insurers And States
Pie’s dedicated state page and AM Best describe workers’ compensation in 40 states and Washington, D.C., but Pie’s homepage and January 2026 release say 39 states plus D.C. Confirm the business locations and class codes in the current quote or agent portal. 11,12,1,13,22
Pie’s document library lists state materials for Alabama, Alaska, Arizona, Arkansas, California, Colorado, Connecticut, Delaware, Florida, Georgia, Illinois, Indiana, Iowa, Kansas, Kentucky, Louisiana, Maryland, Michigan, Minnesota, Mississippi, Missouri, Nebraska, Nevada, New Hampshire, New Jersey, New Mexico, New York, North Carolina, Oklahoma, Oregon, Pennsylvania, Rhode Island, South Carolina, Tennessee, Texas, Utah, Vermont, Virginia, West Virginia and Wisconsin, plus Washington, D.C. That list is useful evidence of a service footprint, but it does not promise eligibility for every class code or multistate combination. 12 4
The declarations should identify either The Pie Insurance Company, Pie Casualty Insurance Company or another applicable entity for the actual risk. Do not rely on the logo or group rating alone to identify the insurer. 5 22
Partner-Carrier Products
Pie says business owner’s, general liability and professional liability policies are underwritten by unaffiliated third-party insurers, and its cyber page refers to carrier partners. The reviewed public pages do not name the currently participating insurers for these products. 5,7,8,9,10
The reviewed BOP, cyber, general-liability and professional-liability pages do not publish a product-by-state availability table. Pie’s terms also say products are not available in every US area or situation. 7,8,10,9,4
Pie’s terms say website coverage descriptions are not part of an insurance contract and do not change a policy or endorsement; eligibility and product availability can vary by geography and applicant. 4
For these products, ask whether Pie is placing one policy or coordinating several, which insurer issues each part and whether the quoted carrier is admitted in the relevant state. A website’s typical coverage list cannot answer contract-specific requirements. 4
Commercial Auto Is Legacy Business
Pie says it stopped accepting commercial-auto submissions on December 1, 2025 and will issue no new or renewal commercial-auto policies on or after January 1, 2026. Existing policyholders retain coverage through their policy term and can still use Pie’s claim channels. 14,20
The continued appearance of commercial auto on Pie’s website is relevant to existing policy service and claims, not evidence that a new buyer can obtain the product. 14 20
Service And Compensation
Policy Documents And Certificates
Pie’s policyholder account tutorial describes payment-method updates, instant or custom workers’ compensation certificates, policy details and downloads for policies, state posters, certificates and endorsements. Agent-served customers may need their agent for a custom certificate. 15,16
A certificate shows information about an existing policy; it does not itself add a party or amend coverage. Pie’s FAQ says workers’ compensation does not use additional insured status and handles waiver-of-subrogation requests separately. Confirm that the requested waiver or other endorsement was actually issued. 16
Billing, Fees And Premium Audit
Published workers’ compensation options include annual, semi-annual, quarterly and monthly schedules, plus pay-as-you-go. The monthly schedule requires 16.6% upfront followed by ten monthly payments; pay-as-you-go uses reported payroll and no initial deposit. 17,18
Pie publishes a 3% credit-card convenience fee for new, single-state workers’ compensation policies, except in Florida, Nebraska, Maryland and Rhode Island. Its page does not describe this fee for multi-state or renewal policies. 17
Pie says each specific or blanket waiver-of-subrogation request carries a charge set by state rules and disclosed individually; the public FAQ does not give a dollar schedule. 16
Pie says partner agents receive commissions on new and renewal workers’ compensation policies, and its legal footer says compensation rates can vary among insurers. The reviewed current pages do not publish the standard rate or the amount attached to a buyer’s policy. 21,5
Pie requires an annual workers’ compensation premium audit that replaces estimated payroll with actual payroll information. Its audit partner may request payroll and employee records, cash-expense details and subcontractor certificates, so the final premium can differ from the initial estimate. 19
Keep payroll and job classifications current during the term, and request a written explanation of any audit adjustment. Pay-as-you-go can reduce the gap between estimated and reported payroll, but Pie’s public page does not say it eliminates the required final audit. 18 19
Pie says it sends a workers’ compensation renewal quote about 30 days before the current term ends for the policyholder’s review and acceptance. 16
Reporting A Claim
Pie asks policyholders to report a workplace injury within 24 hours through its online form, 24/7 phone line or email. After intake, it says a claims professional follows up, determines whether the policy covers the claim and explains applicable benefits if accepted. 20
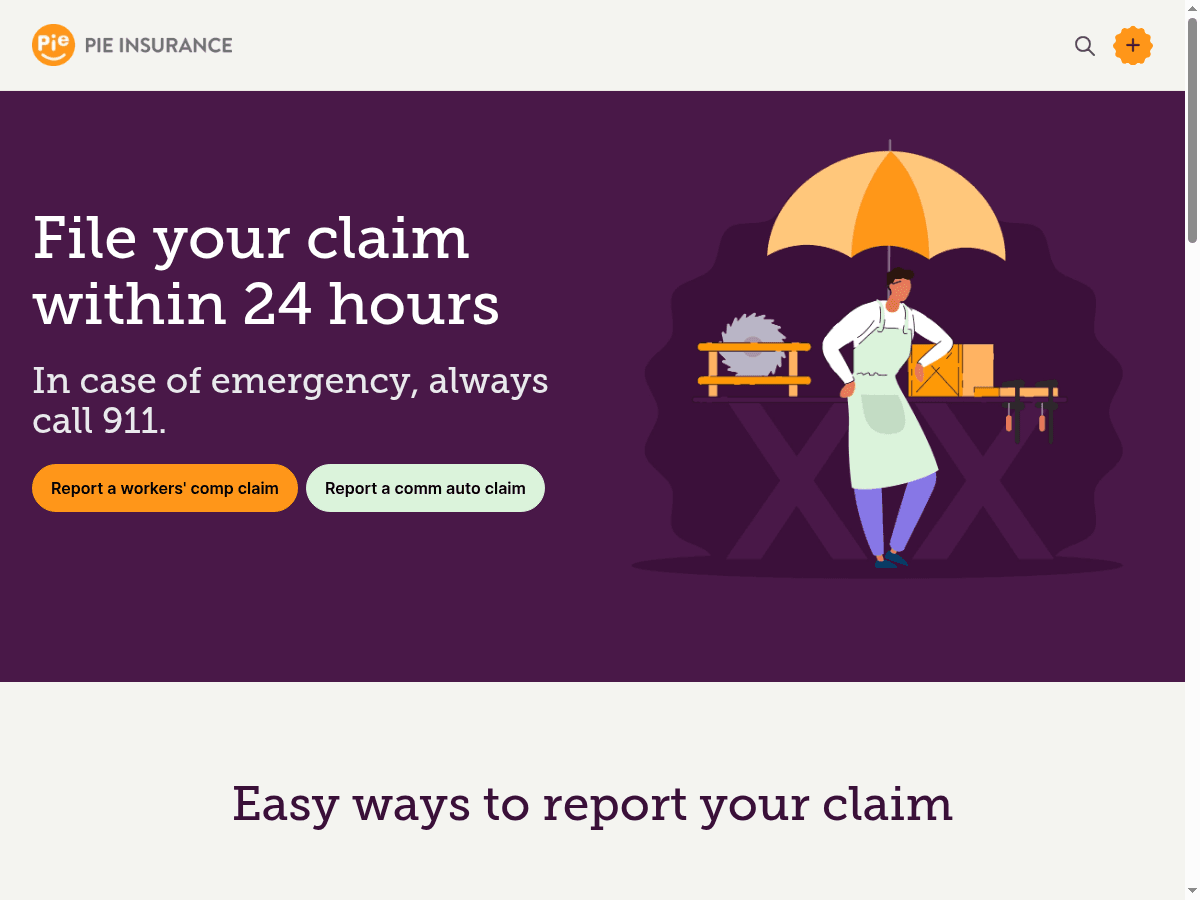
Pie’s public claim-reporting page. The commercial-auto option serves existing policies after Pie stopped new and renewal business.
Pie’s agency FAQ says Pie manages workers’ compensation claims in 34 states and CorVel handles Alaska, Mississippi, Nevada, New Mexico and Oregon. That 39-state split is not reconciled with the separately advertised 40-state-plus-D.C. footprint. 21,11,22
Before a loss, save the state-specific notice and identify whether Pie, CorVel or another administrator will receive the first report. Reporting to a service channel does not by itself establish coverage; the issuing insurer and policy terms control. 20 12
What To Confirm In A Quote
- The legal insurer and producer. Which entity issues each policy, and is Pie Insurance Services currently licensed for the transaction? For workers’ compensation, check whether The Pie Insurance Company or Pie Casualty appears on the declarations. 5 23 24
- State and class-code eligibility. Confirm every work location, employee class and out-of-state exposure. Pie’s published footprint counts conflict, and a listed state does not guarantee that a particular operation qualifies. 11 12 4
- Forms, limits and endorsements. Request the actual policy forms, exclusions, limits and deductibles or retentions. For BOP and general liability, identify which property and products-liability terms are included; for cyber and E&O, check prior acts, reporting triggers and defense costs. 7 8 10 9
- Total cost and audit exposure. Separate premium, taxes, installment charges, the credit-card fee and waiver charges. Ask how payroll and subcontractors will be treated at audit and how to dispute a classification or final adjustment. 17 16 19
- Service responsibilities. Establish who handles certificates, endorsements, renewals and claims for each policy, especially when an agent or third-party carrier is involved. Record the state-specific claim administrator and reporting deadline before coverage begins. 15 21 20
- Timing and discontinued products. Ask what remains after the first online decision before coverage can bind. Do not rely on an older Pie commercial-auto page or navigation label for new coverage; the company says that program is closed to new and renewal business. 6 14
Sources
Pie Insurance official website
- Pie Insurance. Pie Insurance; Homepage: small-business audience; direct workers’ compensation quote; online account; footer entity, insurer and availability qualifications. Accessed 2026-09-15.
- About Pie Insurance. Pie Insurance; About Pie; direct and agency distribution; footer legal disclosure. Accessed 2026-09-15.
- Workers’ Comp Insurance For Small Businesses. Pie Insurance; Quote inputs; coverage description; company-reported quote-time and savings qualifications; AM Best link. Accessed 2026-09-15.
- Terms Of Use. Pie Insurance; Updated 26 April 2022; Ownership and Agreement to Terms; geographic and product eligibility; policy controls coverage. Accessed 2026-09-15.
- Legal. Pie Insurance; State Licenses; footer disclosure naming producer and workers’ compensation versus third-party underwriting roles. Accessed 2026-09-15.
- Pie Insurance — Quote. Pie Insurance; Live unauthenticated first step: Business ZIP Code; inspected without entering data or advancing. Accessed 2026-09-15.
- Business Owner’s Policy. Pie Insurance; BOP definition; typical components; invitation to start a BOP quote; footer third-party insurer qualification. Accessed 2026-09-15.
- Cyber Insurance For Small Businesses. Pie Insurance; First- and third-party descriptions; carrier-partner quote invitation; policy-variation qualification. Accessed 2026-09-15.
- Errors And Omissions Insurance. Pie Insurance; E&O and professional-liability equivalence; typical claims; carrier-partner placement statement; footer third-party insurer qualification. Accessed 2026-09-15.
- General Liability Insurance. Pie Insurance; Typical covered categories; carrier-partner quote invitation; footer third-party insurer qualification. Accessed 2026-09-15.
- Workers’ Comp Coverage By State. Pie Insurance; Headline says 40 states and the District of Columbia; rendered state selector listed 39 state names and omitted New York and D.C.. Accessed 2026-09-15.
- Agency Document Library. Pie Insurance; Workers’ Comp State Documents: 40 named states plus Washington, D.C.. Accessed 2026-09-15.
- Pie Insurance Reports Strong 2025. Pie Insurance; 13 January 2026 release; Key 2025 Milestones says 39 states plus Washington, D.C.; company and distribution description. Accessed 2026-09-15.
- Commercial Auto Claim FAQs. Pie Insurance; Does Pie offer commercial auto insurance?; submission cutoff 1 December 2025; no new or renewal policies on or after 1 January 2026; legacy claim guidance. Accessed 2026-09-15.
- Online Account Tutorial. Pie Insurance; Payment-method updates; instant and custom certificates; policy information; document access; agent-handled custom certificate qualification. Accessed 2026-09-15.
- Workers’ Comp FAQs. Pie Insurance; Certificates; waiver request timing and state-dependent charge; billing and payments; renewal timing; annual audit; claims. Accessed 2026-09-15.
- Payment Options. Pie Insurance; Annual, semi-annual, quarterly, monthly and pay-as-you-go schedules; payment methods; 3% card fee and state exceptions. Accessed 2026-09-15.
- Pay-As-You-Go With Pie Insurance. Pie Insurance; No initial deposit; actual-payroll monthly premium; automatic deductions; payroll-provider coordination. Accessed 2026-09-15.
- File Your Claim Within 24 Hours. Pie Insurance; Workers’ compensation reporting by online form, 24/7 phone or email; information requested; post-report coverage determination. Accessed 2026-09-15.
- Partner FAQ. Pie Insurance; Workers’ compensation claim handling in 34 states; CorVel handling in Alaska, Mississippi, Nevada, New Mexico and Oregon; producer commissions on earned premium. Accessed 2026-09-15.
- AM Best Rating Disclosure Report — Pie Casualty Insurance Company. AM Best Rating Services, Inc.; Page 1: A- (Excellent), Stable, affirmed 24 April 2026; page 14: rating unit, group insurer acquisitions, 100% workers’ compensation writing through PCIC and TPIC from 1 January 2024, 40 states and D.C.. Accessed 2026-09-15.
- The Pie Insurance Company — Company Details. Missouri Department of Commerce and Insurance; Company name; active license status; NAIC 21857; property-and-casualty authority; 2025 workers’ compensation market data. Accessed 2026-09-15.
- Pie Casualty Insurance Company — Entity Details. Illinois Department of Insurance; Legal name; P&C Domestic Stock; active status; NAIC 10997; Pie Group Holdings, Inc. parent. Accessed 2026-09-15.
- Administrative Actions — January 2024. Wisconsin Office of the Commissioner of Insurance; Allegations and Actions Against Companies: Pie Insurance Services, Inc. agreed to add a disclaimer to its “save up to 30%” advertising claim after misleading-advertising allegations. Accessed 2026-09-15.