
What Is Coterie Insurance?
How Coterie Insurance's agent-led platform, small-business coverages, fees, renewals and claims service work.
Coterie Insurance is a managing general agency and digital small-business insurance platform built primarily for licensed agents, brokers and distribution partners. It is not a direct-to-consumer insurance marketplace; a business owner is directed to work with an agent. 1,6,19
In practice, Coterie supplies the underwriting and service platform while an insurance professional helps the buyer select and purchase a policy. The insurance company named on the resulting policy—not the Coterie brand—takes on the policy obligations. 5 8
Pros And Cons
Pros
- A focused digital workflow for small commercial accounts. An agent can begin with a business name and address, check prefilled information, select the principal industry, customize the proposed coverage and pay within the same dashboard. That can reduce duplicate data entry for an eligible account, although the advertised speed has not been independently timed here. 5 6
- Core products are described in useful detail. Coterie publishes current product guides for its BOP and miscellaneous professional liability policy, including appetite, limit options and important form features. It also links sample policies from its policyholder page. These materials give a buyer concrete questions to bring to an agent before relying on the final proposal. 13 14 10
- Optional coverages address several common small-business exposures. The current endorsement catalogue includes cyber, workplace violence, employment practices liability, restaurant, liquor liability and contractors equipment options. The cyber and workplace-violence guides also identify response-service partners, which lets a buyer ask how those services work before an incident. 12 15 16
- Policyholders have direct service routes after binding. My Policy Center, online policy-change and certificate tools, and online and phone claim reporting are publicly documented. A business can therefore establish where to retrieve documents and start routine requests instead of depending on an undocumented process. 10 11
Cons
- A business owner cannot use Coterie as a direct shopping marketplace. Coterie says its platform is for licensed agents and brokers, and it directs buyers to an agent. The quality and breadth of any market comparison therefore depend on that agent's process and the other insurers the agent considers. 6
- The public catalogue does not cover every routine commercial need. Coterie's claims page says it does not write workers' compensation or automobile policies. Cyber, employment practices, workplace violence and hired/non-owned auto are described as additions to eligible base policies rather than a separate full catalogue of standalone products. A buyer needing several lines may require other placements. 11 12 13
- Product availability needs a live check. Coterie's broad all-state marketing conflicts with its MPL guide, which excludes six jurisdictions, and its BOP appetite can change with coastal rules and catastrophe moratoriums. A nationwide distribution statement does not mean every line is available for every class or location. 5 14 18
- Several charges can sit outside the quoted premium. The terms describe variable policy fees, a $7 installment fee, possible late and insufficient-funds charges, and a separate Manage My Risk Program fee that can be fully earned. Automatic renewal can also charge the payment method on file. A buyer needs the itemized total and cancellation treatment, not only the premium. 8
- Service timing is not consistent across the public pages. One page says Coterie will respond around two business days after a claim report, while the claims page says three to five. Neither statement promises when a claim will be resolved. 10 11
How It Works
An Agent Starts The Application
A licensed agent starts a quote in Coterie's dashboard with the client's business name and address, selects the principal industry, confirms or edits prefilled details, customizes coverage and pays to bind an eligible policy. Business owners who do not already have an agent can use Coterie's agent finder. 5,6,2
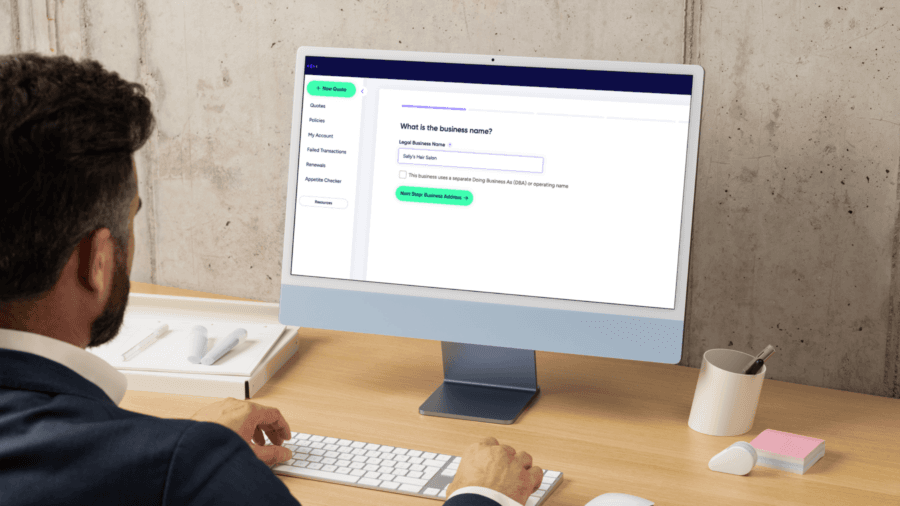
Coterie's agent quoting workflow, shown in an official marketing image rather than a live submitted application.
Coterie advertises bindable quotes in under two minutes for eligible standard risks. Its terms qualify that claim: a quote or estimate is not an insurance contract, and coverage remains subject to underwriting approval, eligibility verification and formal policy issuance. 6,8
That distinction matters when a landlord or client has a deadline. The agent should verify that the displayed quote is still valid, all requested endorsements have been accepted, payment has cleared and the carrier has issued the policy before treating coverage as active. 8
Coterie also distributes BOP and general liability through Progressive's BusinessQuote Explorer, which is operated by Progressive's in-house agency. That is a distribution relationship: it does not turn Coterie into Progressive or identify the insurer on an eventual policy. 21
The Platform, Agency And Insurer Are Different
Coterie Applications, Inc. provides the platform under the website terms. Florida's current corporate record lists it as the member of Coterie Insurance Agency, LLC, the agency named in Coterie's footer; Massachusetts separately lists the agency with an active property-and-casualty producer license through December 28, 2026. 8,1,22,23
Coterie's terms say carrier partners underwrite and issue its policies. Its claims page identifies a separate Spinnaker Specialty route for surplus-lines policies beginning CSE, while its current coastal guide names Spinnaker Insurance Company only for eligible coastal Texas BOP risks. The issuing insurer therefore needs to be checked on each quote and policy. 8,11,17
A managing general agency can perform delegated underwriting and administrative work for insurers, but it is not automatically the insurance company bearing the risk. Coterie's terms make that split explicit by assigning underwriting and issuance to carrier partners. 19 8
Coterie's website lists multiple investors, and Allianz X records Coterie as a current direct investment after leading a 2025 Series C round. The reviewed sources do not establish an acquisition, a controlling parent or Coterie's complete current ownership table. 1,19,20,22
Allianz X's investment and Allianz Re's reinsurance relationship should not be read as proof that an Allianz company issues a particular Coterie policy. The declarations and endorsements need to identify the actual insurance company. 19
Coverage And Availability
The Core Catalogue
Coterie's current core catalogue consists of a business owner's policy (BOP), standalone general liability and miscellaneous professional liability (MPL/E&O). A BOP combines liability with property coverage; the other two are distinct policies. 2,4,3,14
Commercial property sits within the documented BOP, while the specialty options below are endorsements to eligible base policies. 2 12
Business Owner's Policy
Coterie's December 2025 BOP guide states eligibility of up to $10 million in revenue and 50 employees, reduced to $5 million and 15 employees for contractors. It lists up to $1 million in building value and $500,000 in business personal property, with limits and availability still varying by state, industry and quote. 13,8
The guide describes business income on an actual-loss-sustained basis and several included limits, but it also lists mandatory exclusions and state- and industry-specific restrictions. Ask for the exact base form and every endorsement in the quote rather than assuming the guide's maximums or examples apply. 13
Optional Endorsements
Coterie currently markets cyber, workplace violence, employment practices liability, restaurant, liquor liability and contractors equipment endorsements. Its BOP guide also lists optional hired and non-owned auto liability, equipment breakdown, drone liability and other property extensions. These are optional additions, not evidence of separate standalone policies. 12,13,15,16
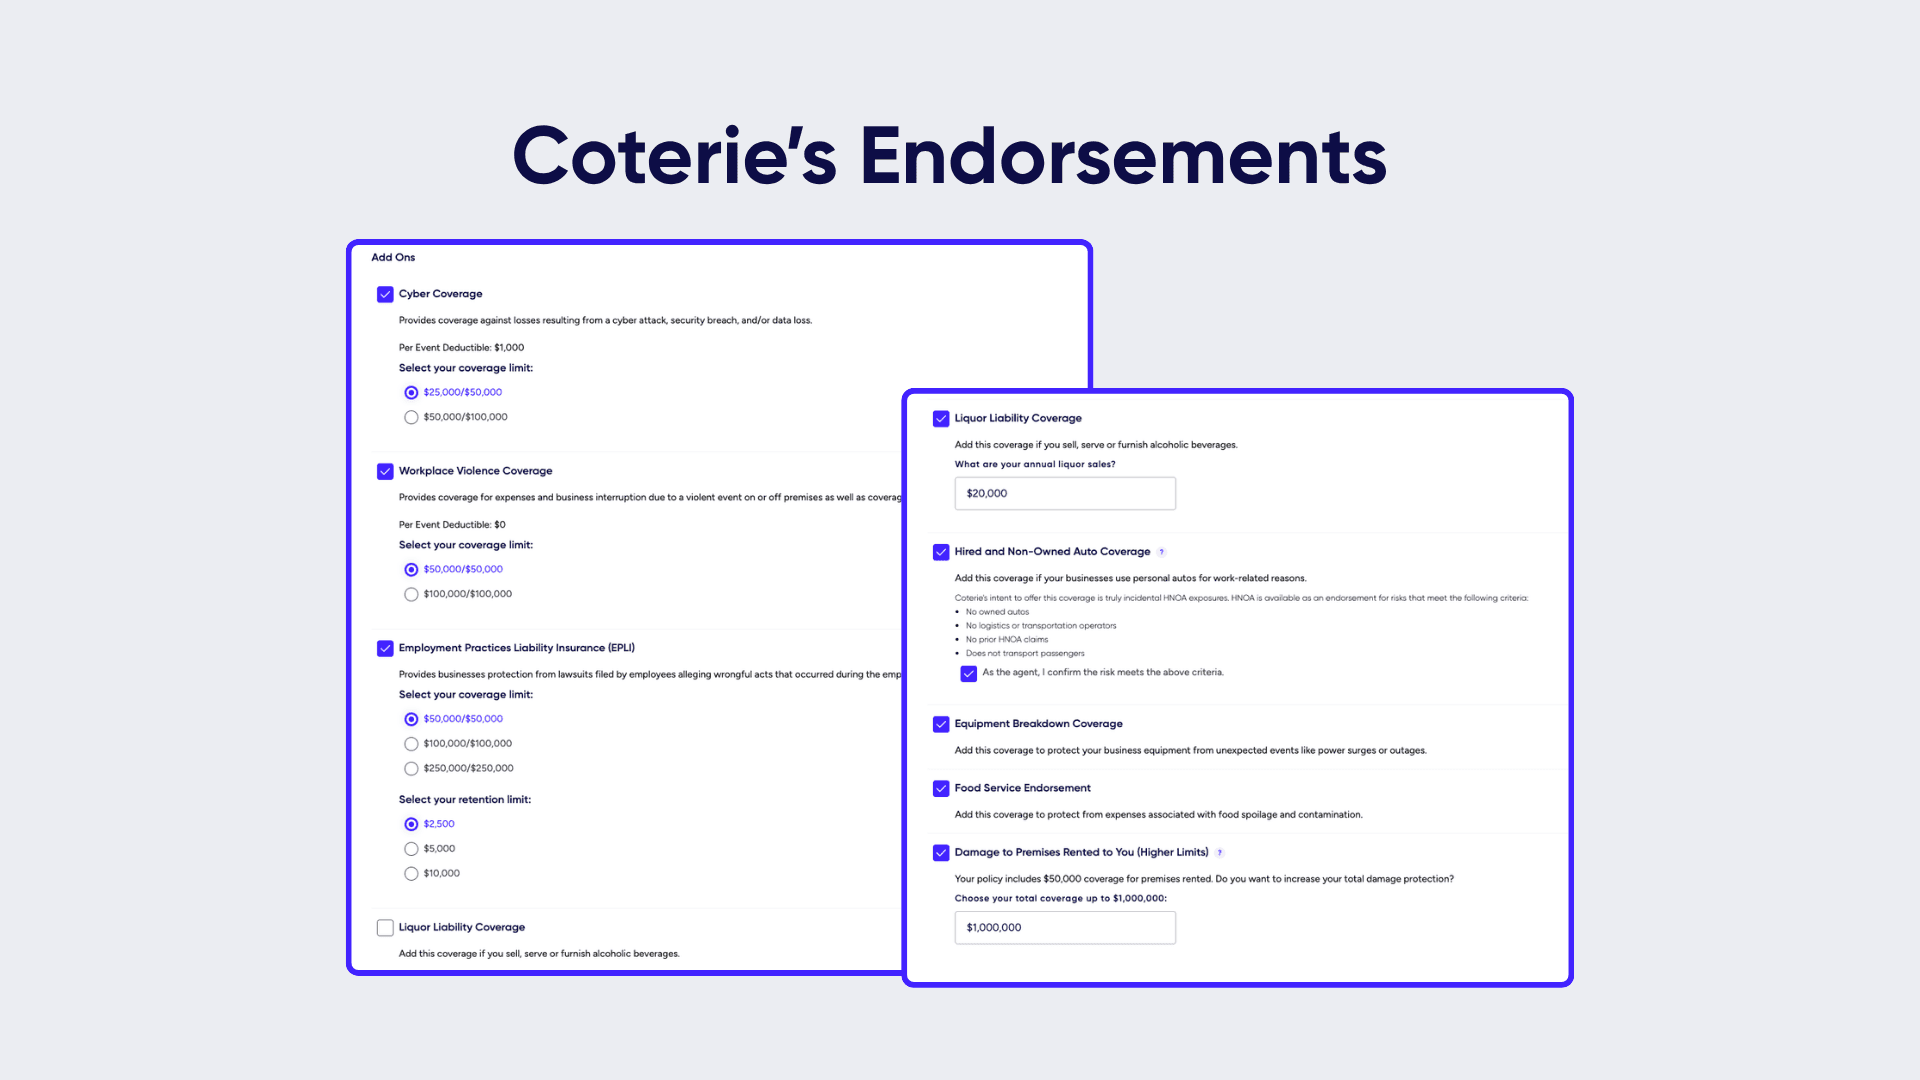
Coterie's endorsement-selection demonstration, using example limits and selections rather than a buyer's quote.
The screenshot is useful for understanding the selection step, not for establishing availability or price. For example, the separate workplace-violence guide says that option is an endorsement to BOP or general liability, and the cyber page likewise describes cyber as an endorsement on those base products. 16 15
Miscellaneous Professional Liability
Coterie's MPL is a claims-made professional liability policy for listed service professions. Its current guide says the basic policy includes a 60-day extended reporting period and offers longer periods for purchase; retroactive coverage and limits depend on the selected terms and eligibility. 14,8
Because the form is claims-made, the retroactive date and reporting window are central terms. A low premium is not comparable if an older date, broader definition of professional services or longer reporting option is missing. The current guide also lists profession-specific restrictions, so a familiar job title alone does not establish that every activity is accepted. 14
Product And Location Rules
Coterie says BOP and general liability are admitted products across all 50 states. That is not account-level availability: its terms make every product subject to jurisdiction, business class, underwriting and formal issuance, and temporary catastrophe moratoriums can stop new BOP binding in specified areas. 7,8,18
Coterie's broad broker page says BOP, general liability and professional liability are admitted in all 50 states, but its December 2025 MPL guide says MPL is unavailable in DC, Illinois, Massachusetts, Montana, North Dakota and Virginia. A newer quick-start page narrows the statement to BOP and general liability in all 50 states and MPL in most states. Use the product guide and a current quote for MPL eligibility. 5,7,14
As of September 11, 2026, Coterie says eligible BOP risks 3 to 26 miles from the coast can be considered in Florida, Texas, Mississippi, Alabama, Georgia, South Carolina and North Carolina, generally with up to $250,000 of business personal property and no building coverage in the coastal zone. Risks closer than 3 miles remain ineligible under this expansion, and Florida building coverage is unavailable statewide. 17,18
These coastal figures are especially time-sensitive. Coterie maintains a separate current-moratorium page that can temporarily stop new BOP binding or restrict increases in affected areas; agents should check it at the time of quote. 18
Coterie's policyholder FAQ says each business location must have its own policy rather than listing several operating addresses on one Coterie policy. 10
Coterie's claims page expressly says it does not write workers' compensation or automobile policies. Hired and non-owned auto appears only as an optional liability endorsement in the BOP guide and should not be read as commercial auto physical-damage coverage. 11,13
Service And Compensation
Policy Documents, Changes And Renewals
Policyholders can use My Policy Center, request policy changes, generate certificates and start a claim online. Coterie tells policyholders to use their agent or broker first for coverage questions and provides public sample BOP, general liability and professional liability forms for orientation. 10,8
A certificate of insurance is evidence of the policy information shown on it; it is not a substitute for the endorsement that changes coverage or adds an insured. For contract requirements, confirm that the policy change itself was accepted and issued. 10 8
Unless a policy says otherwise, Coterie's terms describe a 12-month policy that may renew automatically. Renewal charges may use the payment method on file, and the policyholder can contact Coterie or use account tools to change renewal preferences. 8
Review the renewal notice for changes in insurer, forms, limits, deductible, endorsements, premium and fees. An automatic payment setting does not establish that the renewed coverage is unchanged. 8
Fees And Agent Compensation
Coterie's terms say new and renewal policies have a one-time policy fee whose amount varies, successful installments carry a $7 fee, late fees can be up to $10 and insufficient-funds fees up to $35. Fees vary by state and line, can be nonrefundable, and additional charges must be disclosed before bind or renewal. 8
A Coterie policy can include a separate Manage My Risk Program fee that the terms call fully earned on payment and nonrefundable after midterm cancellation. The terms say participation, or an accepted outside risk program, affects the insurance premium but do not publish the program fee amount. 8
The risk-program provision deserves separate attention: declining the program can increase premium, while joining can create a nonrefundable fee. Ask the agent to show both paths, identify an accepted outside program if relevant and explain what remains payable after cancellation. 8
Coterie's privacy policy says it may pay commissions to certain agents through a third-party processor. The reviewed public sources do not state the commission rate or whether additional producer compensation applies to a particular buyer's policy. 9,8
Reporting A Claim
Coterie accepts standard and surplus-lines claim reports online and standard reports by phone. It asks for the policy number, named insured, loss date, event description and carrier name, then assigns a claims representative to investigate under the policy terms. 11,8
Coterie's policyholder page says its team will reach out around two business days after an online claim report, while the claims page says to expect contact within three to five business days. The claims page gives no standard settlement timeline. 10,11
Coterie directs cyber claim reports through its normal intake and says it works with Cyberscout on the investigation. Workplace-violence reports also start with Coterie before a specialty partner handles the response. These service descriptions do not establish that an event is covered. 11,15,16,8
Keep the carrier name and policy-specific notice instructions with the policy documents. Coterie's intake can help start the process, but the actual form determines whether an event is covered and which insurer owes a covered payment. 11 8
What To Confirm In A Quote
- The legal insurer and product. Which carrier issues each policy, is it admitted or surplus lines in the state, and which entity will handle notices and claim decisions? Do not infer the answer from Coterie's investors or a carrier used for another state. 8 11 19
- Every required line. Does the business need workers' compensation, owned commercial auto, umbrella, crime, cyber or another policy that Coterie's three-line core catalogue does not supply? Identify which items are endorsements and which require another insurer. 2 11 12
- Eligibility today. Confirm the business class, operations, revenue, employee count, every location and any coastal or catastrophe restriction. For MPL, reconcile the current jurisdiction list before completing an application. 13 14 18
- The actual forms. Obtain the declarations, base form and all endorsements. For MPL, check the covered professional services, retroactive date and extended reporting period; for BOP, check property valuation, coinsurance, business income, exclusions and any sublimits. 13 14
- Total and cancellation cost. Separate premium, taxes, the policy fee, installment charges, the Manage My Risk Program fee and any producer compensation or other charges. Ask which amounts are refundable and what a monthly payment schedule costs over the full 12-month term. 8 9
- Renewal and service authority. Is automatic renewal enabled, when must it be changed, who can approve a policy change, and how quickly can the agent and Coterie produce the required endorsement or certificate? 8 10
- Claim notice. Save the carrier name, policy number, online and phone reporting routes and any cyber or workplace-violence emergency service. Ask which deadline in the policy controls even if Coterie's service page quotes a different response window. 11 10
Sources
Coterie Insurance official website
- About Coterie Insurance. Coterie Insurance; Agent and broker focus; company history; investors; agency name, NPN and Wisconsin license in footer. Accessed 2026-09-15.
- Insurance for Small Businesses. Coterie Insurance; General Liability, Business Owners Policies and Professional Liability sections; agent distribution; footer agency disclosure. Accessed 2026-09-15.
- General Liability Insurance for Small Business. Coterie Insurance; How General Liability Insurance Works and Common Questions sections. Accessed 2026-09-15.
- Business Owner's Policy for Small Businesses. Coterie Insurance; Package components and exclusions from the typical BOP description. Accessed 2026-09-15.
- Agents and Business Insurance Brokers. Coterie Insurance; How It Works steps; nationwide product statement; dashboard service statement. Accessed 2026-09-15.
- Instant Bindable Small Business Insurance Quotes for Agents. Coterie Insurance; Built for Agents and Brokers; online workflow; core lines; endorsements; availability sections. Accessed 2026-09-15.
- Quick Start: Quote and Bind Small Business Insurance With Coterie. Coterie Insurance; Five-Step Quote-to-Bind Workflow and Does Coterie Work in All 50 States sections. Accessed 2026-09-15.
- Terms and Conditions. Coterie Insurance; Effective December 16, 2025; Sections 1, 5, 6 and 10. Accessed 2026-09-15.
- Privacy Policy. Coterie Insurance; Introduction; Section 6, Payment and Commissions Processing; carrier privacy links. Accessed 2026-09-15.
- Policyholder Resources. Coterie Insurance; Account, policy-change, certificate, claims, multiple-location and sample-policy sections. Accessed 2026-09-15.
- Claims. Coterie Insurance; Reporting routes; response timing; settlement timing; excluded workers' compensation and auto claims; cyber and workplace-violence FAQs. Accessed 2026-09-15.
- Coterie Insurance Endorsements. Coterie Insurance; Cyber, Workplace Violence, Employment Practices, Restaurant, Liquor Liability and Contractors Equipment list; product caveat. Accessed 2026-09-15.
- BOP Product Overview. Coterie Insurance; Pages 1-5: eligibility criteria, base property and liability coverages, additional extensions and mandatory forms. Accessed 2026-09-15.
- Miscellaneous Professional Liability Policy Overview and Product Highlights. Coterie Insurance; Pages 1-7: eligible professions, unavailable jurisdictions, limits, claims-made terms and exclusions. Accessed 2026-09-15.
- Cyber Insurance Overview. Coterie Insurance; Pages 1-2: coverage, criteria, limits and Cyberscout services. Accessed 2026-09-15.
- Workplace Violence Insurance Overview. Coterie Insurance; Pages 1-2: endorsement status, criteria, services and limits. Accessed 2026-09-15.
- Coterie's Coastal Business Insurance Appetite. Coterie Insurance; September 11, 2026 state-by-state coastal BOP eligibility, limits, exclusions and Texas carrier statement. Accessed 2026-09-15.
- Current Moratoriums. Coterie Insurance; Active BOP catastrophe moratoriums, updated September 2-4, 2026; effect on new business and changes. Accessed 2026-09-15.
- Allianz X Announces Strategic Investment in Coterie Insurance. Coterie Insurance and Allianz X; September 11, 2025 announcement; MGA role; Series C investment and reinsurance relationship. Accessed 2026-09-15.
- Allianz X Portfolio and News. Allianz X; Current Direct Investments and September 11, 2025 Coterie strategic-investment entry. Accessed 2026-09-15.
- Coterie BOP and GL Products Available Through Progressive. Coterie Insurance; November 20, 2025 agency relationship and Progressive BusinessQuote Explorer distribution scope. Accessed 2026-09-15.
- Coterie Insurance Agency, LLC Entity Record. Florida Department of State, Division of Corporations; Active foreign LLC record; January 6, 2026 annual report; Coterie Applications, Inc. listed as member. Accessed 2026-09-15.
- Licensed Property and Casualty Agencies. Massachusetts Division of Insurance; Coterie Insurance Agency, LLC; license 19000811; approval period December 28, 2025 through December 28, 2026. Accessed 2026-09-15.