
What Is Cowbell Insurance?
Cowbell suits small and midsize businesses seeking cyber options by company size, with technology E&O and Zurich management-liability options also available; firms needing broad commercial coverage should compare a full-service broker. Some security services cost extra.
Your policy’s named insurer remains responsible for coverage; Cowbell is an insurance platform and agency that may act as a general agent. Cowbell Insurance Agency LLC identifies itself as a US P&C producer. 1,5,2Cowbell's current U.S. website and producer disclosure; the exact role can vary by product and placement.
Cowbell's main U.S. offerings are cyber policies for different company sizes, combined Technology Errors and Omissions (E&O) and cyber coverage for technology businesses, and a modular Zurich management-liability product. A buyer works through a broker, while Cowbell supplies underwriting technology, risk information and cyber claims support. 1 9
What Are the Pros and Cons of Cowbell?
Pros
- Pro: Cyber options span small business, middle market and excess layers. Prime 100 and Prime 100 Pro target businesses up to $100 million in revenue; Prime 250 reaches up to $1 billion; Prime One addresses more complex digital exposures; and Prime Plus can sit above a primary cyber policy. This lets a broker investigate a program matched to the company's size and position in the insurance tower instead of treating “cyber” as one undifferentiated product. 11 12 13 14 15
- Pro: Technology companies can investigate E&O and cyber together. Prime Tech addresses both failures in technology products or services and digital-security events, while Prime Tech Plus can add a follow-form excess layer. That combination can reduce gaps caused by discussing the two exposures in isolation, although the actual primary and excess forms still need to align. 16 17
- Pro: The cyber offering includes services beyond the policy. Cowbell describes risk ratings, security insights, connectors, training, risk engineering and an in-house cyber claims team. Those resources can give a policyholder concrete prevention and incident-response contacts during the term. 22 21
- Pro: Current materials identify several product-level carrier relationships. The reviewed overviews name Palomar for Prime 100 and Prime 100 Pro, Palomar and Chaucer for Prime 250, and Chaucer for Prime One. That is more useful than a carrier-logo wall, though the proposal must still identify the legal insurer for the buyer's placement. 11 12 13 14
Cons
- Con: The public path is broker-first. Cowbell's buyer-facing route is an agent directory, while quoting and binding tools are described for appointed agents. A business looking for a self-directed direct purchase should expect a broker in the process. 8 9
- Con: Not every product follows the same state or distribution path. Prime 100 Pro lists 47 states, Prime 250 and Prime Tech describe surplus-lines availability, and Zurich Select Plus is available through appointed Zurich E&S wholesalers. The agency's broad license list does not mean every product is available to every buyer in every state. 5 12 13 16 19
- Con: Some insurer details remain quote-specific. Prime Plus and Prime Tech Plus refer to A-rated paper without naming the carrier, and the Select Plus page refers to Zurich admitted paper rather than the issuing legal insurer. Buyers need the declarations and proposed forms to identify the responsible carrier and exact coverage. 15 17 18
- Con: Public cost information is limited. Cowbell discloses a 2.99% credit-card fee and says financing carries a disclosed finance charge, but the reviewed U.S. sources do not publish buyer-wide premiums or producer-compensation terms. A buyer cannot establish total cost from the website alone. 20 2
How Does Cowbell Work?
The Buyer, Broker, Agency and Insurer
Buyers work through an insurance agent or broker; appointed agents use Cowbell’s platform to quote, bind and issue eligible products, and no direct-buyer quote path was described. 8,1,9,11Current public U.S. buyer and broker paths. This does not establish that every listed agent can access every Cowbell product.
An agent's access also depends on the product. Zurich says its Select Plus management-liability product is reached through appointed Zurich E&S wholesalers using a Cowbell-powered platform. A broker listed for cyber business is not automatically evidence that the same broker can place Select Plus. 19
Cowbell identifies Zurich as a $60 million Series C investor and partner, while Zurich describes Cowbell as its technology collaborator for Select Plus. The reviewed sources do not describe Cowbell as a Zurich subsidiary or say that Zurich underwrites every Cowbell product. 4,19,3Ownership and commercial relationship characterization in Cowbell's 26 July 2024 financing announcement and current Zurich Select Plus page; no capitalization table was available.
This distinction matters because “Cowbell” can refer to the technology and brand, Cowbell Insurance Agency LLC can perform producer or general-agent functions, and another legal company can issue the policy. Ask the broker to identify each role in writing. 2 5
Quoting and Binding
Cowbell says appointed agents can quote, bind and issue Prime 100 through its platform in less than five minutes. That is a company-reported workflow claim, not a guarantee that a particular application will qualify or bind in that time. Larger or more complex accounts can require different underwriting: the FAQ says a Prime 250 renewal needs a signed application and review before the quote is released. 11 20
What Coverage Does Cowbell Offer, and Where?
Cyber Programs
You can compare Cowbell’s distinct admitted Prime 100/100 Pro, non-admitted Prime 250/Prime One and follow-form excess Prime Plus programs; their revenue fit, limits, coverage and jurisdiction differ. 9,11,12,13,14,15Current U.S. broker-resource catalogue and product overviews. Product descriptions are illustrative and actual forms control.
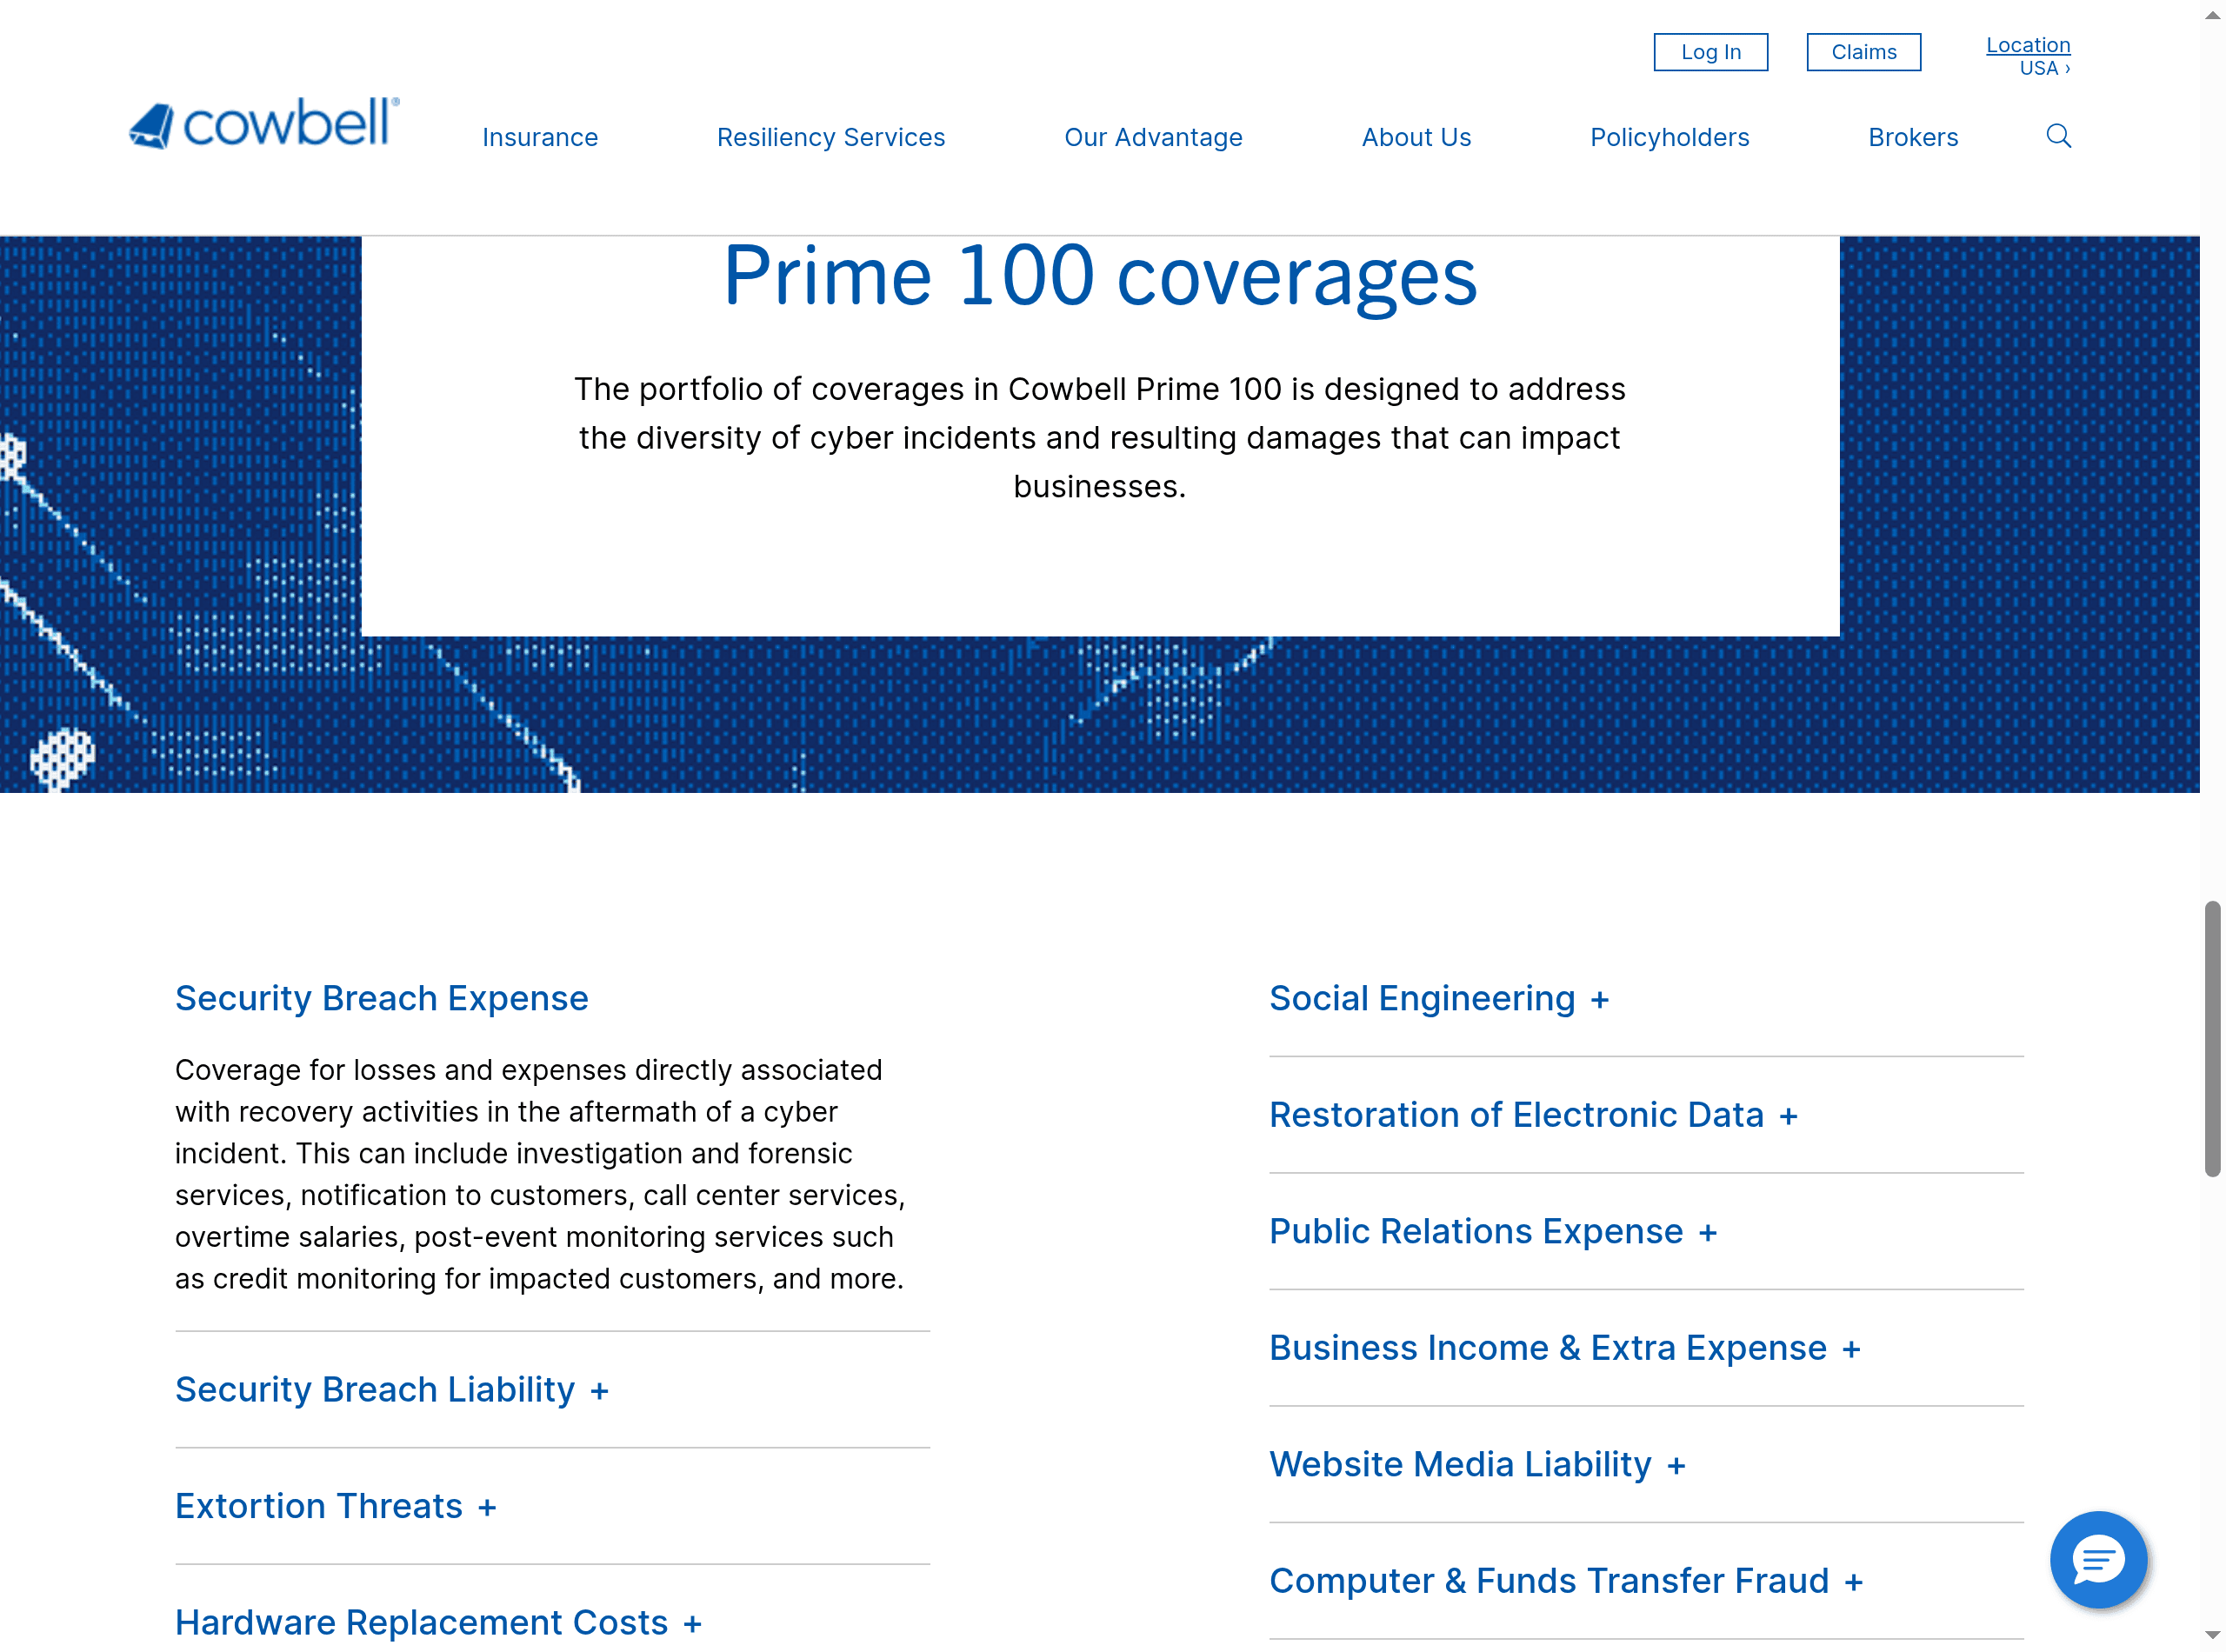
Cowbell advertises up to $3 million for Prime 100 Pro, up to $10 million for select Prime One risks including AI and quantum exposures, and up to $5 million excess through Prime Plus; underwriting and policy terms control. 12,14,15Selected differentiators in current U.S. product overviews; these are maximum advertised limits, not guaranteed buyer terms.
These program names do not make every listed event a separate policy. For example, Prime 100's overview describes security-breach expense, business-income loss, extortion, fraud and website-media liability within its cyber portfolio. Treat those as coverage parts to check in the proposed form, not as standalone products in Cowbell's commercial catalogue. 11
Technology E&O and Excess
Eligible technology firms up to $1 billion revenue can ask about non-admitted Prime Tech, combining Tech E&O and cyber with up to $5 million limits; Prime Tech Plus is a separate excess option up to $5 million. 16,17Current U.S. Prime Tech and Prime Tech Plus marketing overviews; product appetite and actual terms are subject to underwriting.
“Follow form” means the excess policy is intended to track parts of the underlying primary policy once that primary limit is exhausted. It does not remove the need to compare definitions, exclusions, notice requirements and attachment points between the layers. Prime Tech Plus's own overview says its descriptions are illustrative and the issued policy controls. 17
Management Liability
Private companies under 250 employees and $50 million assets may consider Zurich Select Plus for D&O, EPL, fiduciary or crime; Zurich says appointed E&S wholesalers use Cowbell’s platform. 18,19Current Zurich Select Plus U.S. wholesale offering. Availability through a wholesaler does not guarantee eligibility or inclusion of all four modules.
The four modules protect different interests. D&O concerns alleged wrongful acts by company leaders; employment-practices coverage concerns workplace claims; fiduciary liability concerns employee-benefit-plan duties; and crime responds to specified dishonest acts. Ask which modules are quoted and whether each limit is separate or shared. 19
Geography, Carriers and Forms
Confirm the exact product and state before applying: Cowbell publishes licenses for all states and DC, but current product availability differs—Prime 100 Pro is listed in 47 states, while Prime 250 and Prime Tech describe broader surplus availability. 5,6,12,13,16Company-published U.S. licensing and current product availability. A California public lookup for the producer could not be completed, so the agency's current national license status was not independently confirmed.
Ask which insurer is on your declarations: Cowbell names Palomar for Prime 100/100 Pro, Palomar and Chaucer for Prime 250, Chaucer for Prime One, and more general carrier descriptions for excess, Tech Plus and Select Plus. 11,12,13,14,15,17,18,7Named paper providers in the current reviewed product materials. The quote and policy must identify the actual insurer for a specific product, state and account.
Use your issued policy to decide what is covered: Cowbell says product overviews are examples only and do not alter coverage, conditions, exclusions, availability or underwriting. 11,12,13,14,15,16,17Disclaimers in the current U.S. Prime 100, Prime 100 Pro, Prime 250, Prime One, Prime Plus, Prime Tech and Prime Tech Plus overviews.
The distinction between admitted and non-admitted coverage affects filing rules and state guaranty-fund treatment. It does not, by itself, determine whether coverage is broad or suitable. Ask the broker how the proposed carrier and product are authorized in the applicable state. 5
How Is Cowbell Paid, and What Service Does It Provide?
Risk and Policy Services
Cowbell pairs cyber coverage with risk ratings, policyholder insights, security connectors, training and resiliency support; included access may be limited or trial-based, while some services require a subscription. 22,11,15Current U.S. resiliency-services catalogue and cyber product overviews. Eligibility, third-party terms and whether a service is bundled depend on the policy and service agreement.
“Included with a policy” needs a product-level check. The Prime 100 overview, for example, limits complimentary Wizer training to unlimited seats for the first policy year, while the resiliency catalogue separately labels several services as subscription based or available only to qualified customers. 11 22
Ask your agent how to request changes or cancel; Cowbell directs policyholders to agents for cancellations and agents to Cowbell for endorsements. Prime 100 renewal proposals start around 60 days before expiry; Prime 250 requires a signed application and underwriting. 20Current public FAQ for P100 and P250; other products and individual policy terms may use different servicing and renewal procedures.
Claims Support
Cowbell says its in-house cyber claims team and response panel are available 24/7; have your policy number, incident date, details and contact ready. The issuing insurer and policy determine coverage and payment. 21,11,14Cowbell's current U.S. cyber claims-services page and product overviews; company-reported service description, not an independently measured outcome.
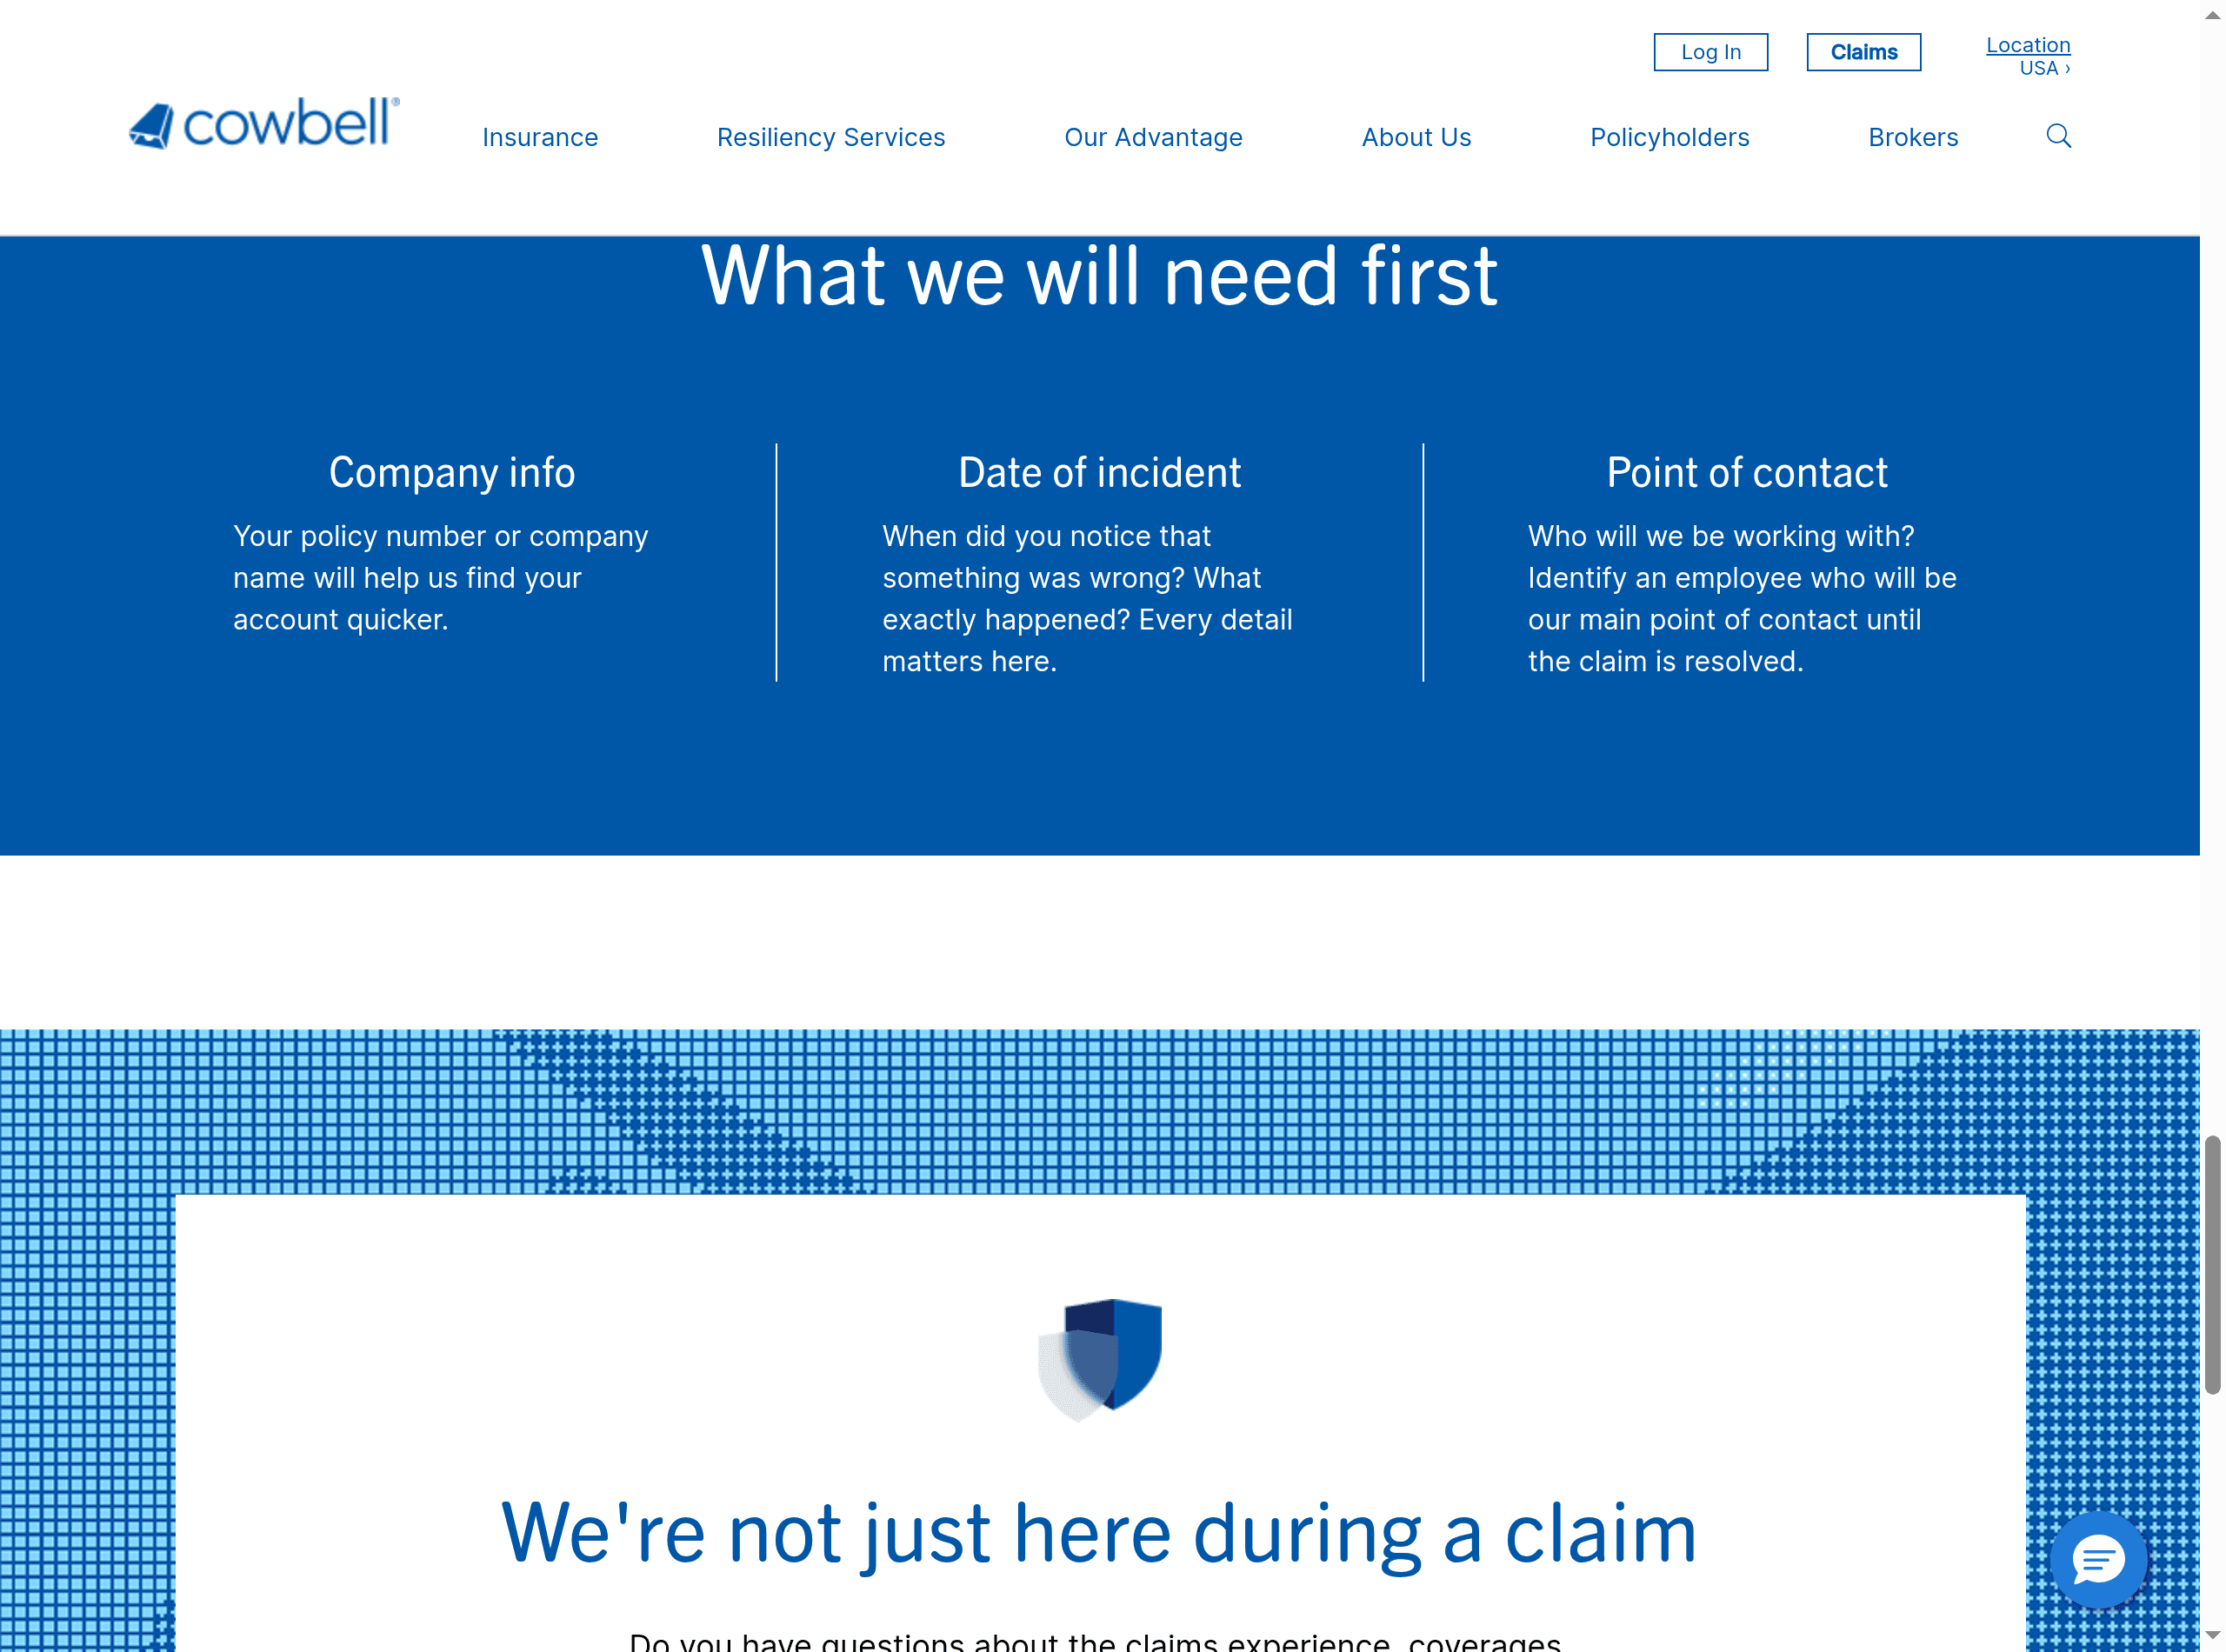
The claims page describes access to breach counsel, forensic investigators and recovery specialists. Before an incident, save the policy's notice instructions and approved-vendor rules; the marketing page does not override consent, retention or reporting conditions in the contract. 21 11
Payment and Compensation
Cowbell lists several payment methods and financing for direct-billed policies; credit cards carry a disclosed 2.99% processing fee, and financing terms are shown before enrollment. 20Current U.S. direct-bill FAQ. Agency-billed policies use different payment routes, and policy invoices control account-specific instructions.
Financing an annual premium changes how the premium is paid; it does not turn the insurance into a month-to-month policy. Request the finance agreement's total charge, cancellation balance and refund treatment before selecting installments. 20
Request your broker’s compensation disclosure and itemized premium because reviewed US sources do not publish Cowbell’s producer commissions or universal premiums. 2,20,5,10Review of Cowbell's U.S. terms, FAQ, licensing page and current product overviews as of 15 September 2026; this is not a finding that compensation or other fees do not exist.
The general website terms also describe paid services and service fees, but they do not establish the insurance premium or producer compensation for a particular policy. Keep any separate cybersecurity subscription price apart from premium, taxes, policy fees, credit-card charges and financing costs. 2 22
What Should You Confirm in Cowbell Quotes?
- The exact product and coverage parts. Is the proposal Prime 100, Prime 100 Pro, Prime 250, Prime One, Prime Plus, Prime Tech, Prime Tech Plus or Zurich Select Plus? Which insuring agreements and optional endorsements are included, and which advertised examples are absent? 9 17
- The legal insurer and Cowbell's role. Which entity appears on the declarations, is the policy admitted or surplus lines in the buyer's state, and is Cowbell acting as producer, general agent, technology provider or claims contact? Do not substitute Zurich's investment or product collaboration for the name of the issuing insurer. 5 4 19
- Limits, retentions and layer alignment. Request limits and sublimits for extortion, social engineering, business interruption, dependent providers, system failure and other relevant events. For Prime Plus or Prime Tech Plus, compare the primary and excess definitions, exclusions, notice provisions and attachment point. 15 17
- Territory, eligibility and term. Confirm every operating state, overseas exposure, industry classification and revenue figure used in underwriting. For Prime 100 Pro, ask whether the proposed short, standard or long-term option changes any coverage or cost. 12 16
- Service entitlements and renewal steps. Which risk tools, training, consultations and incident-response vendors are included, for how long, and under whose terms? Ask which renewal workflow applies and what information must be updated before binding. 22 20
- The itemized cost. Separate premium, taxes, surplus-lines charges, policy or service fees, broker compensation, the 2.99% card charge and any financing cost. Confirm who receives each amount and what remains due if the policy or a separate service is cancelled. 20 2
Cowbell Review Scores for 2026
These averages can combine ratings for different products, locations, and customer groups, including approximate BBB grade conversions. Read each review for its sources, what it covers and how the score is calculated.
Cowbell Review Score
Review Score
1 rated source
Cowbell has one public rating we could find: 1.0 out of 5 on SourceForge from three reviews in 2023. That's too few and too old to say much.
Read Cowbell reviewsCowbell Reliability Scores for 2026
Managing general agent. Cowbell US cyber and specialty program-administration activity at the named-entity level, centered on Cowbell Insurance Agency LLC as producer/general-agent/MGA activity. Palomar Specialty Insurance Company and Chaucer Specialty Insurance Company are separate external carrier-paper relationships and are not treated as Cowbell-owned risk-bearing entities; Cowbell Cyber, Inc. is brand/operator context.
Cowbell Carrier & MGA Reliability Score
This partial Carrier & MGA Reliability Score covers carrier-network strength, disclosure clarity within the scope described on this page. Those factors make up 25% of the full score, normalized to a ten-point scale. The factors left out remain unknown, and evidence for one program does not describe another.
Scored entity unavailable
Sources for Cowbell
What Are the Closest Alternatives to Cowbell?
Other providers that list the same coverage lines as Cowbell.