What Is Kinro Insurance?
Kinro fits U.S. small businesses that want a free review of an existing policy or renewal packet and agent help comparing quotes online. Its pages don't name the insurer behind a given quote, so ask which markets Kinro approached before you switch.
Kinro helps U.S. small businesses identify insurance needs and compare available options through an agency. You can start with business questions online or ask for help by phone, text, email, or chat. 1,19Current retail offering at kinro.com; the function as Kinro describes it, not independently tested placement or service outcomes.
What Are the Pros and Cons of Kinro?
Pros
- Pro: You don't need to know the policy name to start. Kinro's online intake starts with your business activity, and its product guide groups common needs such as a client contract, employees or vehicles. 1 3
- Pro: You can start from the policy you already have. Upload a declarations page, renewal packet or full policy for a free review instead of filling in a blank application. 4
- Pro: The guides tell you what insurers will ask for. Kinro lists inputs such as employee duties, payroll, professional services and cyber controls, so you can gather documents before an agent seeks terms. 13 14 15
- Pro: Support continues after purchase. Kinro says it shops the market at renewal and texts links to policy documents and certificates; marketing texts are a separate opt-in. 1 5
Cons
- Con: You can't tell which insurer you'll get. Kinro shows carrier logos, but its product guides don't name the insurer or policy form for an individual placement, and carrier access depends on approvals. 10 11 4
- Con: Confirm the placement agreement. Kinro’s September 27, 2026 terms define Kinro as Kinro, Inc. and its subsidiaries, including Kinro Insurance Services LLC; insurance is offered through that agency only where licensed. A separate written software agreement controls differences, so confirm the agreement and insurer for your placement. 6
- Con: No buyer-specific cost or compensation. Kinro's consultant prices are market benchmarks, and its compensation disclosure doesn't say what it earns on your policy. 17 18
- Con: No published claims procedure. The reviewed pages don't say how to report a claim or who adjusts it, so get those contacts before you rely on the service. 19 5
How Does Kinro Work?
Kinro targets businesses from contractors and restaurants to consultants, manufacturers and care providers. 1
You can begin Kinro’s public four-step quote intake without a login by selecting your business activity; later steps, pricing and binding were not inspected. 2Observed initial unauthenticated interface in Chrome; no answers, personal information, uploads, account creation or submissions. Later access requirements unknown.
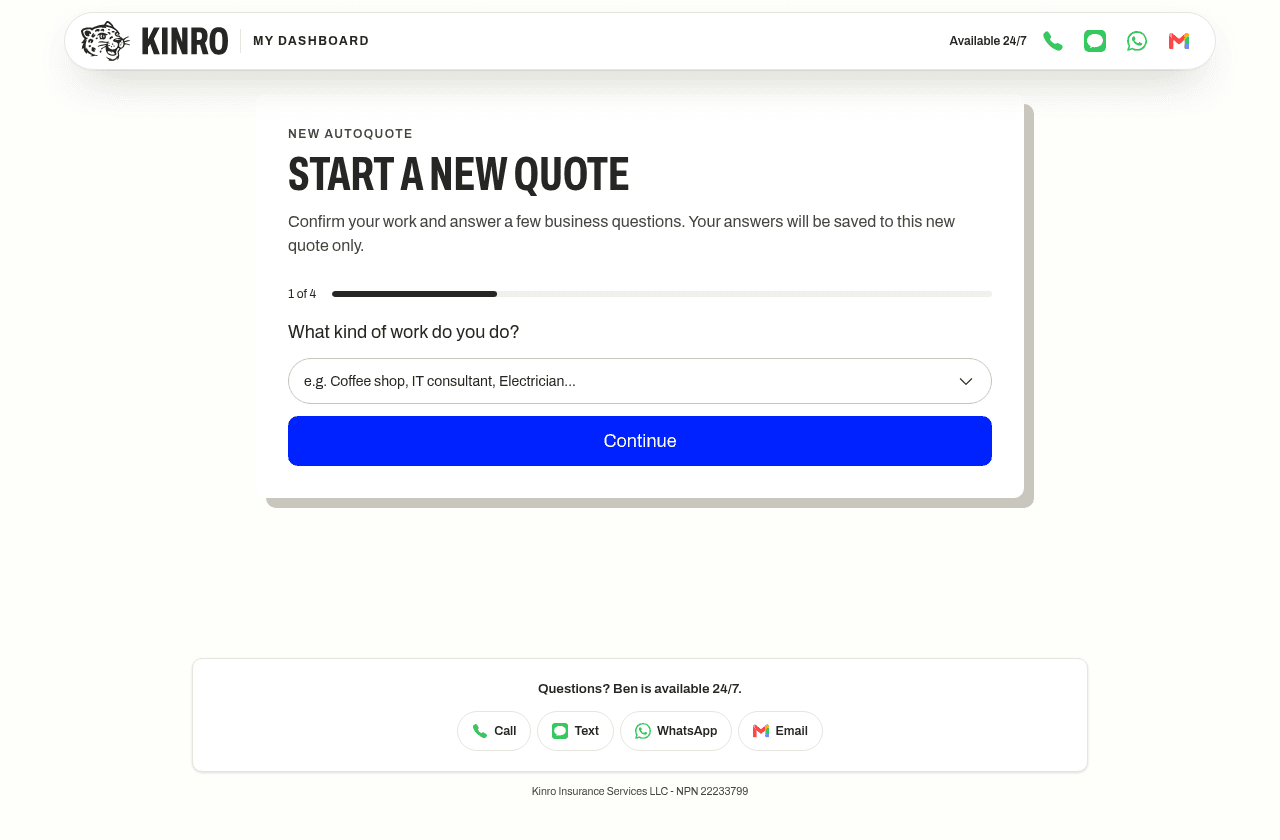
Kinro says AI gathers business details and presents available quote options with licensed-agent help; its roughly two-minute follow-up is a company response-time claim, not a quote or binding deadline. 1Homepage FAQ and response claim; no interactions submitted or timing study performed.
Reviewing an Existing Policy
You can ask Kinro for a free review by uploading up to three policy or renewal files; its promise to find better pricing with equal or more coverage is company-reported, and no replacement quote was tested. 4Public upload entry screen only; no documents uploaded and no service or outcome verification.
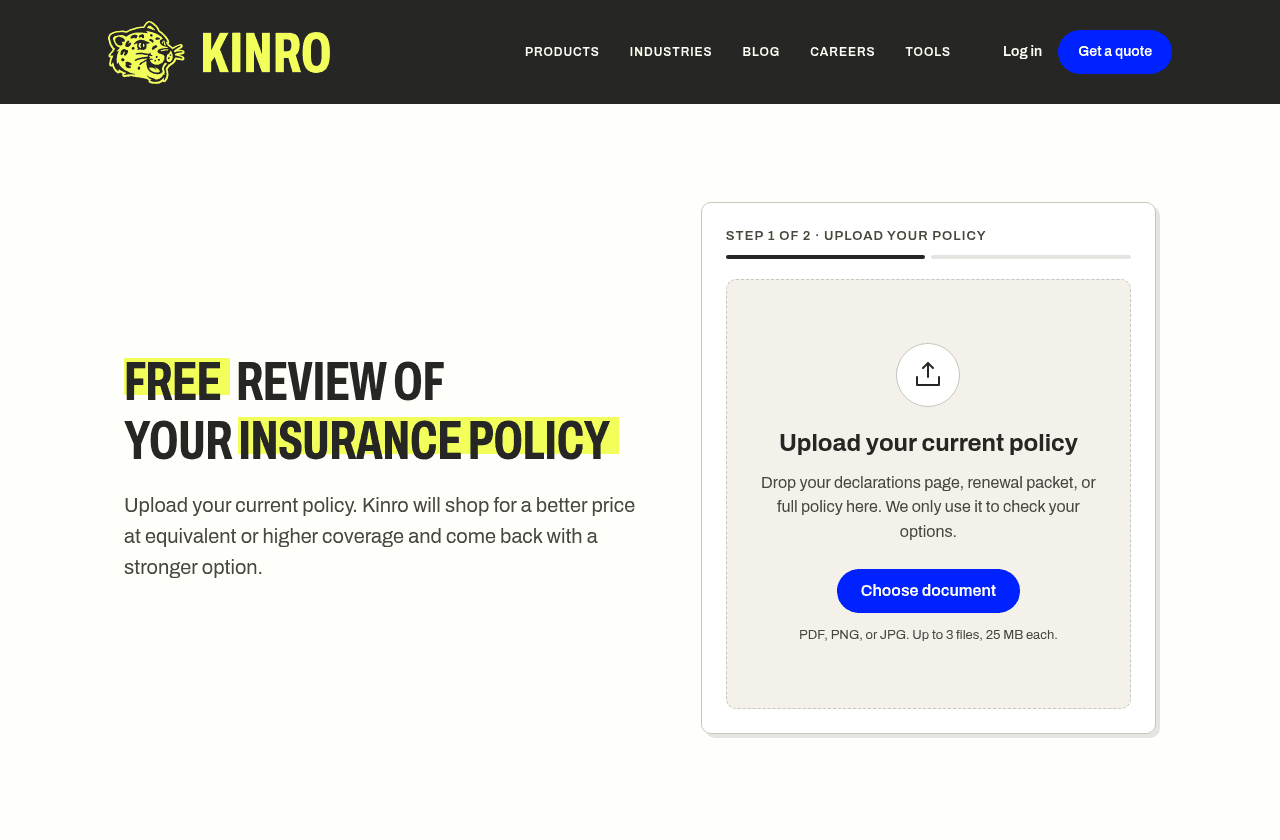
Ask Kinro to show coverage changes next to the price difference. A declarations page is only a summary; you need the full policy and endorsements (the documents that amend it) to see what a replacement changes. Kinro's own general-liability guide points buyers to the actual forms, endorsements and exclusions. 11
Agency and Insurer Roles
Kinro helps arrange coverage as a broker; its website names Kinro Insurance Services LLC and NPN 22233799, while the insurer on your policy takes the risk. 5,10Website identification and brokerage positioning only; LLC existence, NPN assignment, state licenses and insurer authority were not independently established.
Kinro says it works with 50+ companies and displays Progressive, GEICO, AmTrust, Pie, Coterie and NEXT, but access depends on approval and logos do not identify your issuing insurer. 1,10Company-reported network size and displayed brands. Direct appointments, access through intermediaries, actual market search breadth and insurer financial strength are not independently verified.
Ask which markets Kinro approached for your business, which returned quotes, and which insurer is named on each proposal. Its placement terms say a submission doesn't guarantee a quote, rate, placement or binding authority. 9
Buying Through Another Agent
Independent agencies can use Kinro’s market access and technology while retaining their customer relationship under contract; clarify who advises, binds, bills, services and handles renewals. 8,9B2B partner pathways; not a finding that all retail Kinro buyers work through a subproducer, or that Kinro has wholesale or MGA authority in a particular jurisdiction.
If your existing agent brings a quote through Kinro, agree who stays your day-to-day contact and who can authorize changes. 9
Legal Names and Terms to Clarify
Kinro’s September 27, 2026 terms define Kinro as Kinro, Inc. and its subsidiaries, including Kinro Insurance Services LLC, and say insurance is offered through that agency only where licensed. A separate written software agreement controls where it differs from these terms; confirm the contracting entity on your insurance engagement. 6,5Company-published terms effective September 27, 2026 state the parent/subsidiary relationship and insurance-service scope. No placement-specific authority or contracting agreement was independently verified.
Kinro’s September 27, 2026 terms define Kinro as Kinro, Inc. and its subsidiaries, including Kinro Insurance Services LLC; insurance is offered through that agency only where licensed. A separate written software agreement controls differences, so confirm the agreement and insurer for your placement. 6
What Coverage Does Kinro Offer, and Where?
Small businesses can shop for GL, BOP, workers’ comp, auto, trucking, property, equipment, HNOA, umbrella, professional liability, cyber and D&O; categories do not guarantee eligibility or a single package. 3Advertised product catalogue for U.S. businesses. No specimen contract, issuing-insurer mapping or state-specific eligibility inferred.
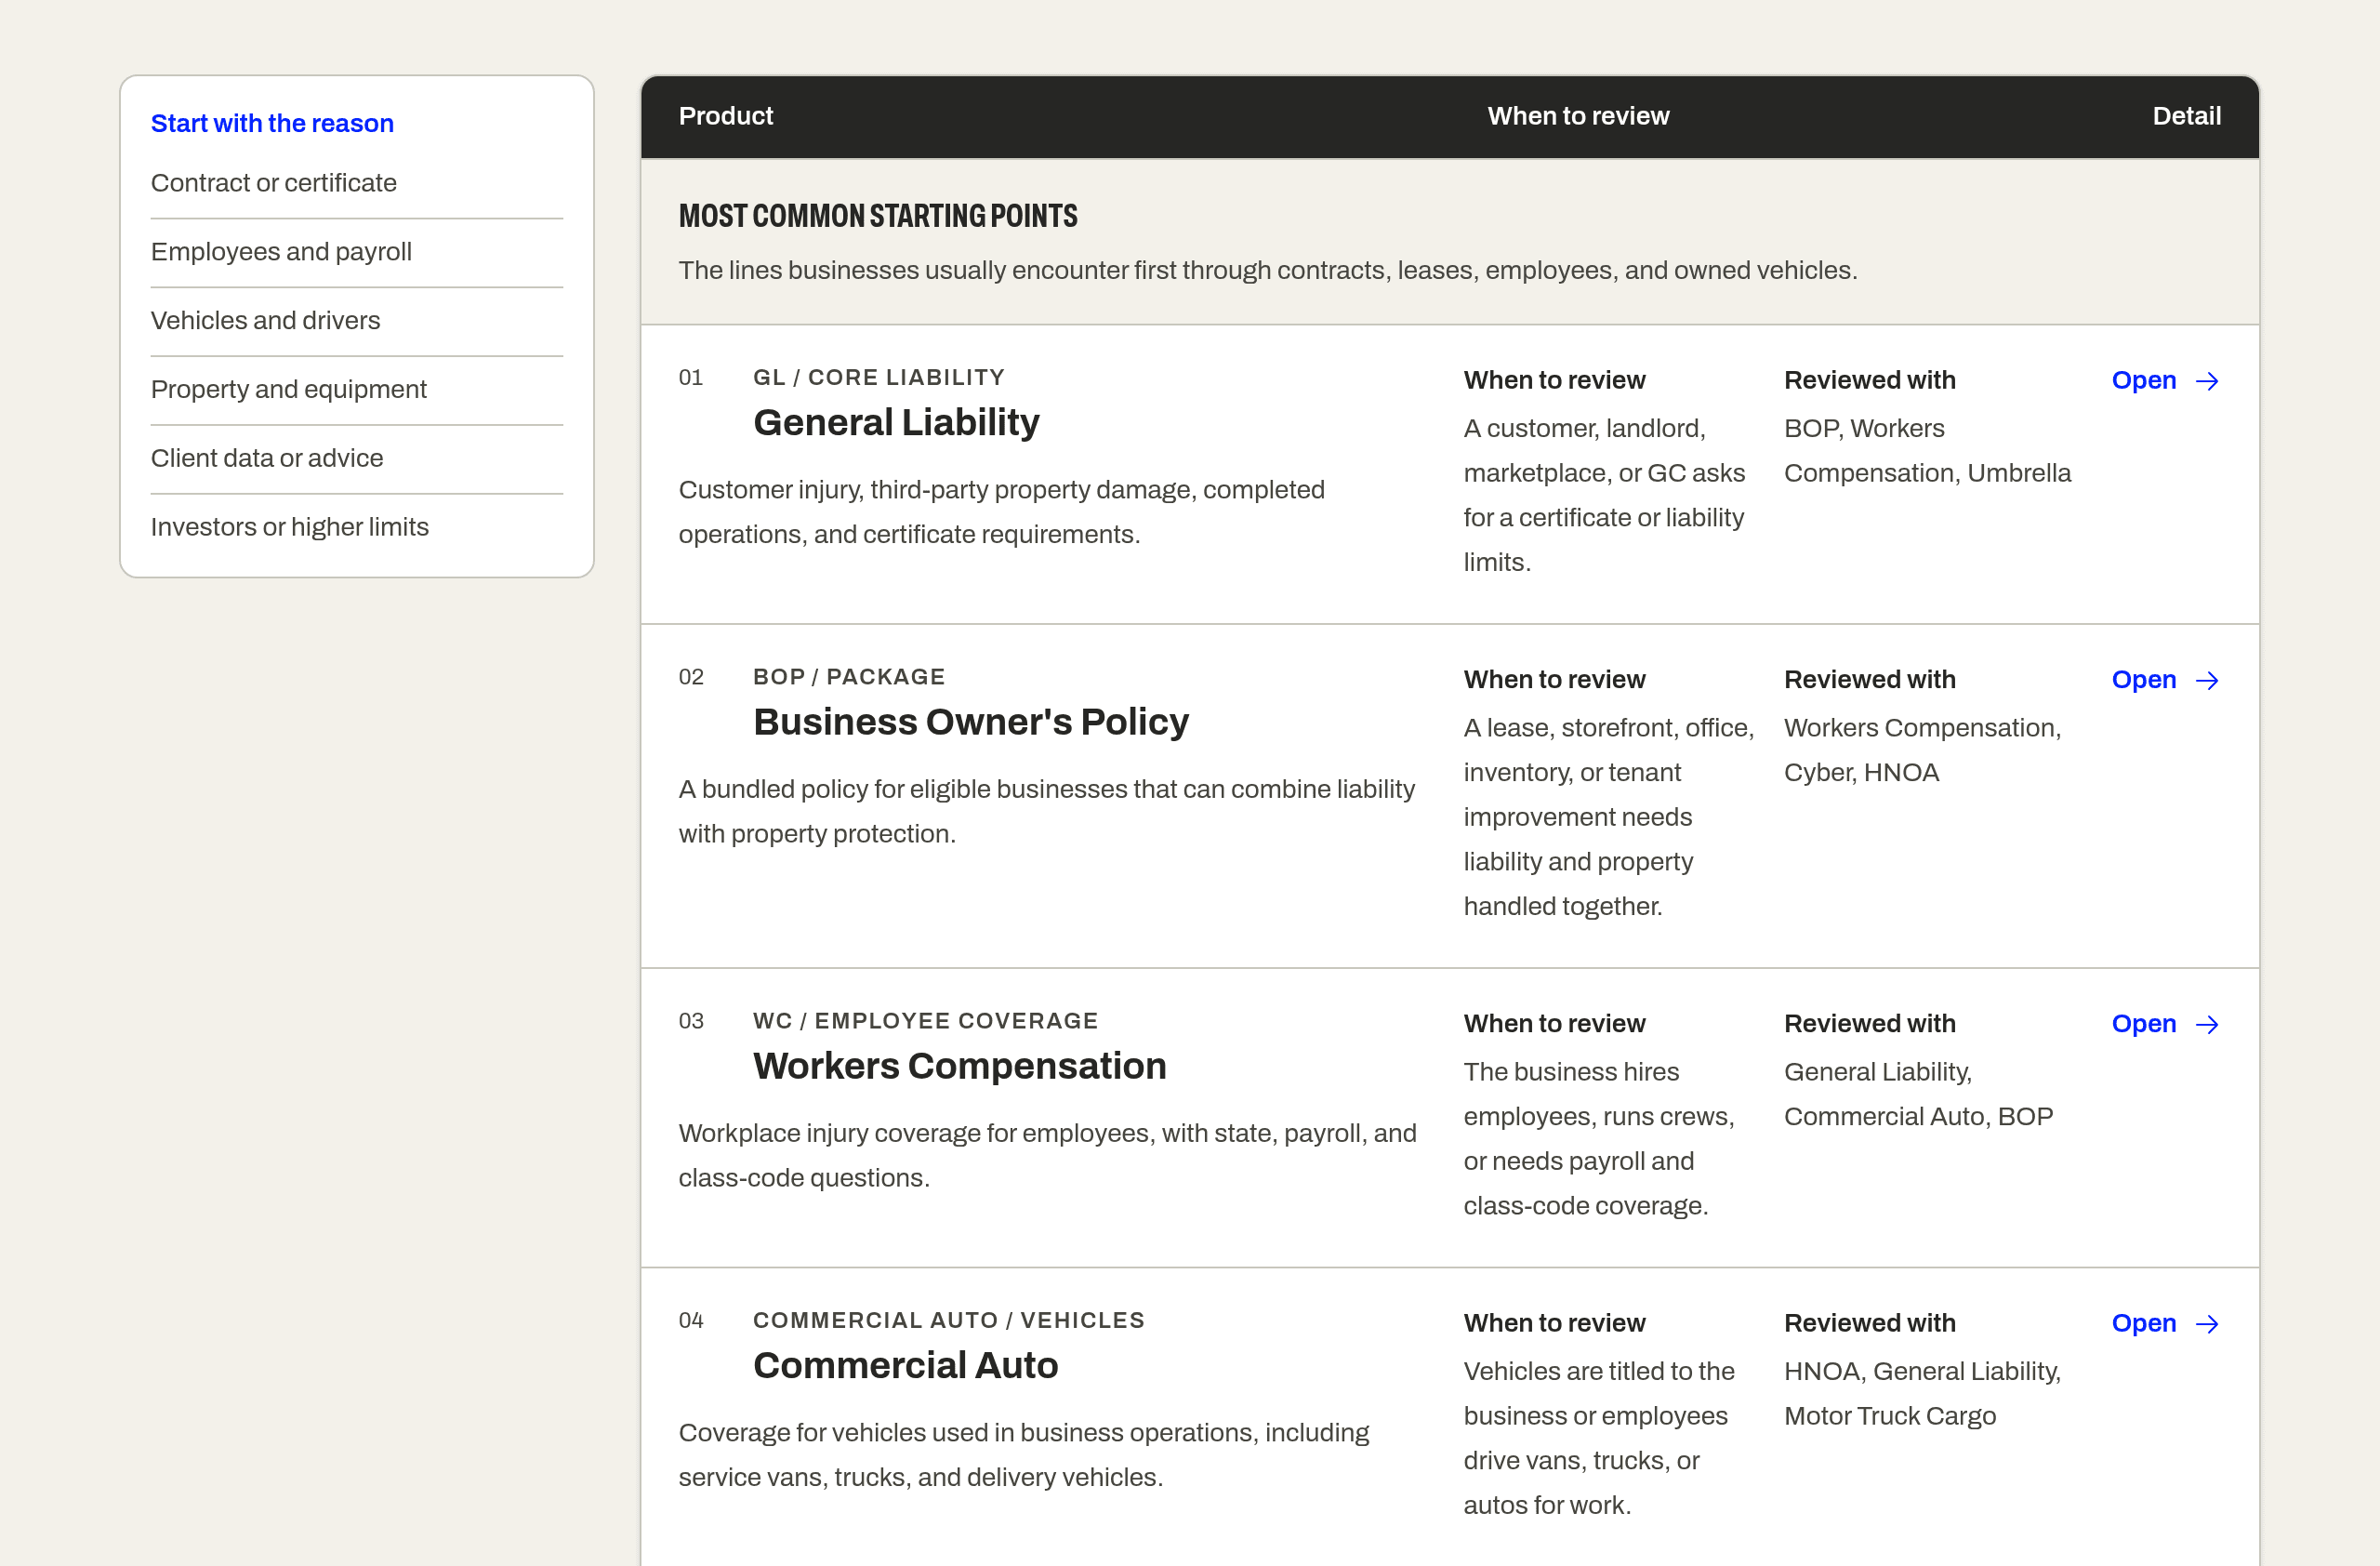
Eligible businesses can compare a BOP combining general liability and business property; Kinro’s intake asks about premises, inventory, equipment and required limits. 12Company product overview, not policy wording; no finding about business interruption, catastrophe coverage or particular insurer terms.
If you have employees, the workers’ compensation guide asks for payroll by state, job duties, owner inclusion or exclusion, and prior losses. Your quote depends on those inputs, not just your business description. 13
For E&O, be ready to describe your services, customers, contracts, claims and current policy; for cyber, Kinro asks about data, MFA, backups, vendor access and incidents. 14,15Published inputs, not a tested underwriting process or guarantee of cyber incident, funds-transfer, professional or technology coverage.
Companies with investors, boards or financing conditions can consider D&O; Kinro’s guide asks about funding, ownership, board, debt and claims, and flags EPL, fiduciary and crime as related questions. 16Product guidance; companion lines are not automatically included.
Ask for insurer-specific forms and terms before buying; reviewed guides do not name the insurer or provide specimen forms, so limits, deductibles and exclusions remain proposal details. 11,12,14,15,16Scoped to cited current product pages; no claim that forms are unavailable on request or elsewhere.
Verify producer authority where your business is located before buying: reviewed sources do not establish a complete state license and product list, and California’s lookup could not be completed. An NPN alone does not prove state authority. 21,20,3California's public lookup for Kinro could not be completed. No negative license finding. U.S. marketing and a published identifier do not verify state authority or any product footprint.
How Is Kinro Paid, and What Service Does It Provide?
Kinro says it shops at renewal and sends text links to documents and certificates with reminders and coverage support; these are service descriptions, not turnaround guarantees. 1,5Retail service statements; no authenticated customer account or actual renewal inspected.
Get the policy’s claim instructions and responsible insurer or administrator before binding because Kinro’s public materials do not establish a dedicated claims route or adjuster. 19,5,9Scoped absence of detailed first-notice-of-loss instructions and administrator identification in these reviewed sources; not a finding that Kinro offers no claims assistance.
Premiums and Producer Pay
Consultants can use Kinro’s monthly benchmarks—$25–$35 GL, $50–$65 E&O and $90–$105 cyber—as rough market references, not quotes matched to an insurer, limit or deductible. 17One industry-page illustration, not Kinro-wide pricing or a comparable quote; underlying calculation methodology not established.
Kinro’s terms say it is usually paid a commission by the issuing insurer, included in the insurer-set premium. Its services are free to use unless a fee is disclosed before you agree to pay it. Ask for the commission and any proposed fee for your policy; the terms do not publish an account-specific amount. 6,18,8September 27, 2026 company terms describe buyer fees and insurer-paid commissions; no account-specific fee or commission rate is stated. Separate agency-partner economics are not retail rates.
A free review isn't a price. Ask for premium, taxes, fees and payment terms, plus the producer’s compensation disclosure. 4 18
Contact Preferences
Before sharing business details, note that Kinro separates service texts from marketing consent, while its privacy policy says website activity may be linked to profiles for marketing. 5,7Published consent and privacy terms, not an audit of data practices or consent enforcement; privacy policy effective August 10, 2026.
What Should You Confirm in Kinro Quotes?
- Who is arranging and issuing coverage? Get the producer’s legal name, its authority in your state, and the issuing insurer for each policy. Ask how any other agency takes part. 5 9
- What changes if you replace a policy? Ask for a side-by-side of covered operations, limits, deductibles, exclusions and endorsements. For professional liability, include the retroactive date (the date from which prior work can be covered). 11 14
- Does it meet your contract? Give the agent the client contract or lease and ask it to confirm limits and any additional-insured wording. Kinro’s consultant guide offers help reading client insurance clauses. 17 11
- When does coverage actually start? Confirm open underwriting conditions, payment, who can bind, and written proof of the effective date. An intake reply isn't coverage. 9 18
- Who handles the policy after purchase? Get named contacts for certificates, changes, billing, renewals and claims, plus the total payable amount and any separate agency charges. 9 18
Kinro Review Scores for 2026
These averages can combine ratings for different products, locations, and customer groups, including approximate BBB grade conversions. Read each review for its sources, what it covers and how the score is calculated.
Kinro Review Score
Review Score
No reviews found
We found no independent customer reviews of Kinro. It shows a 5.0 Google rating on its own website, but there is no review count or listing behind it.
Read Kinro reviewsKinro Reliability Scores for 2026
Broker. Kinro Insurance Services LLC and the Kinro/Kinro AI technology-enabled distribution service for U.S. small-business commercial insurance. No carrier, MGA underwriting authority or risk-bearing status is assigned to Kinro itself.
Kinro Broker Reliability Score
This partial Broker Reliability Score rates only how clearly Kinro discloses its role and relationships, which is 15% of the full score, scaled to ten points. Licensing authority, carrier network and conduct history are unrated because the evidence doesn't establish them, so ask Kinro for its state license and the insurer on your quote.
Scored entity unavailable
Sources for Kinro
What Are the Closest Alternatives to Kinro?
Other providers that list the same coverage lines as Kinro.
 5.5/ 10