List the liability policies you have
Your Spot team lists every liability policy you hold, with its limits and named insureds, plus any contract that asks for higher limits, and builds the submission from there.
Spot for Umbrella and Excess Liability Insurance
We get quotes for the extra limits your contracts require, check how each one fits over your other policies and send the certificate.

Your Spot team lists every liability policy you hold, with its limits and named insureds, plus any contract that asks for higher limits, and builds the submission from there.
Send the contract. Spot compares its required limits with your primary limits and the proposed layer, including the underlying limits the contract assumes, and flags any shortfall.
Umbrella and excess liability insurance
Alder Builders · Policy review
Confirm with your broker
Limits, exclusions, and endorsements
Brokers take the layer to market, and we compare each proposal’s underlying schedule, attachment point, specialty exclusions and the retention that applies when a primary policy doesn’t respond.
Umbrella and excess liability insurance
Coverage limits · Policy terms
Alder Builders
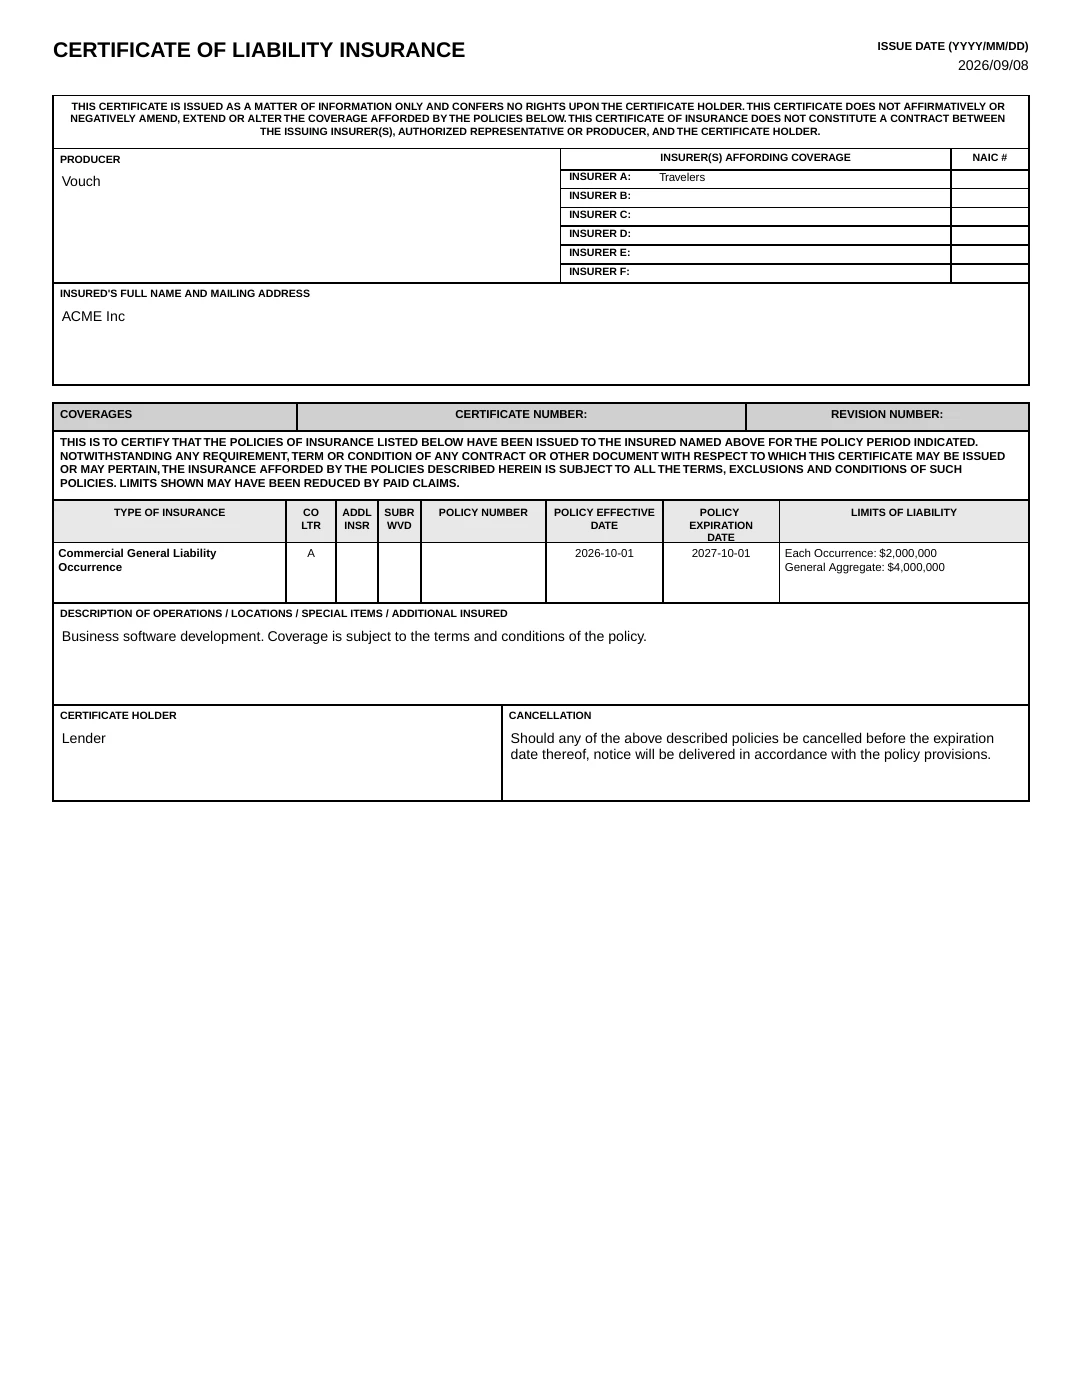
When a general contractor or customer wants a certificate that shows your umbrella limits, ask in your shared Slack channel. Your Spot team gets it ready with the primary and umbrella limits shown together.

MorganAlder Builders

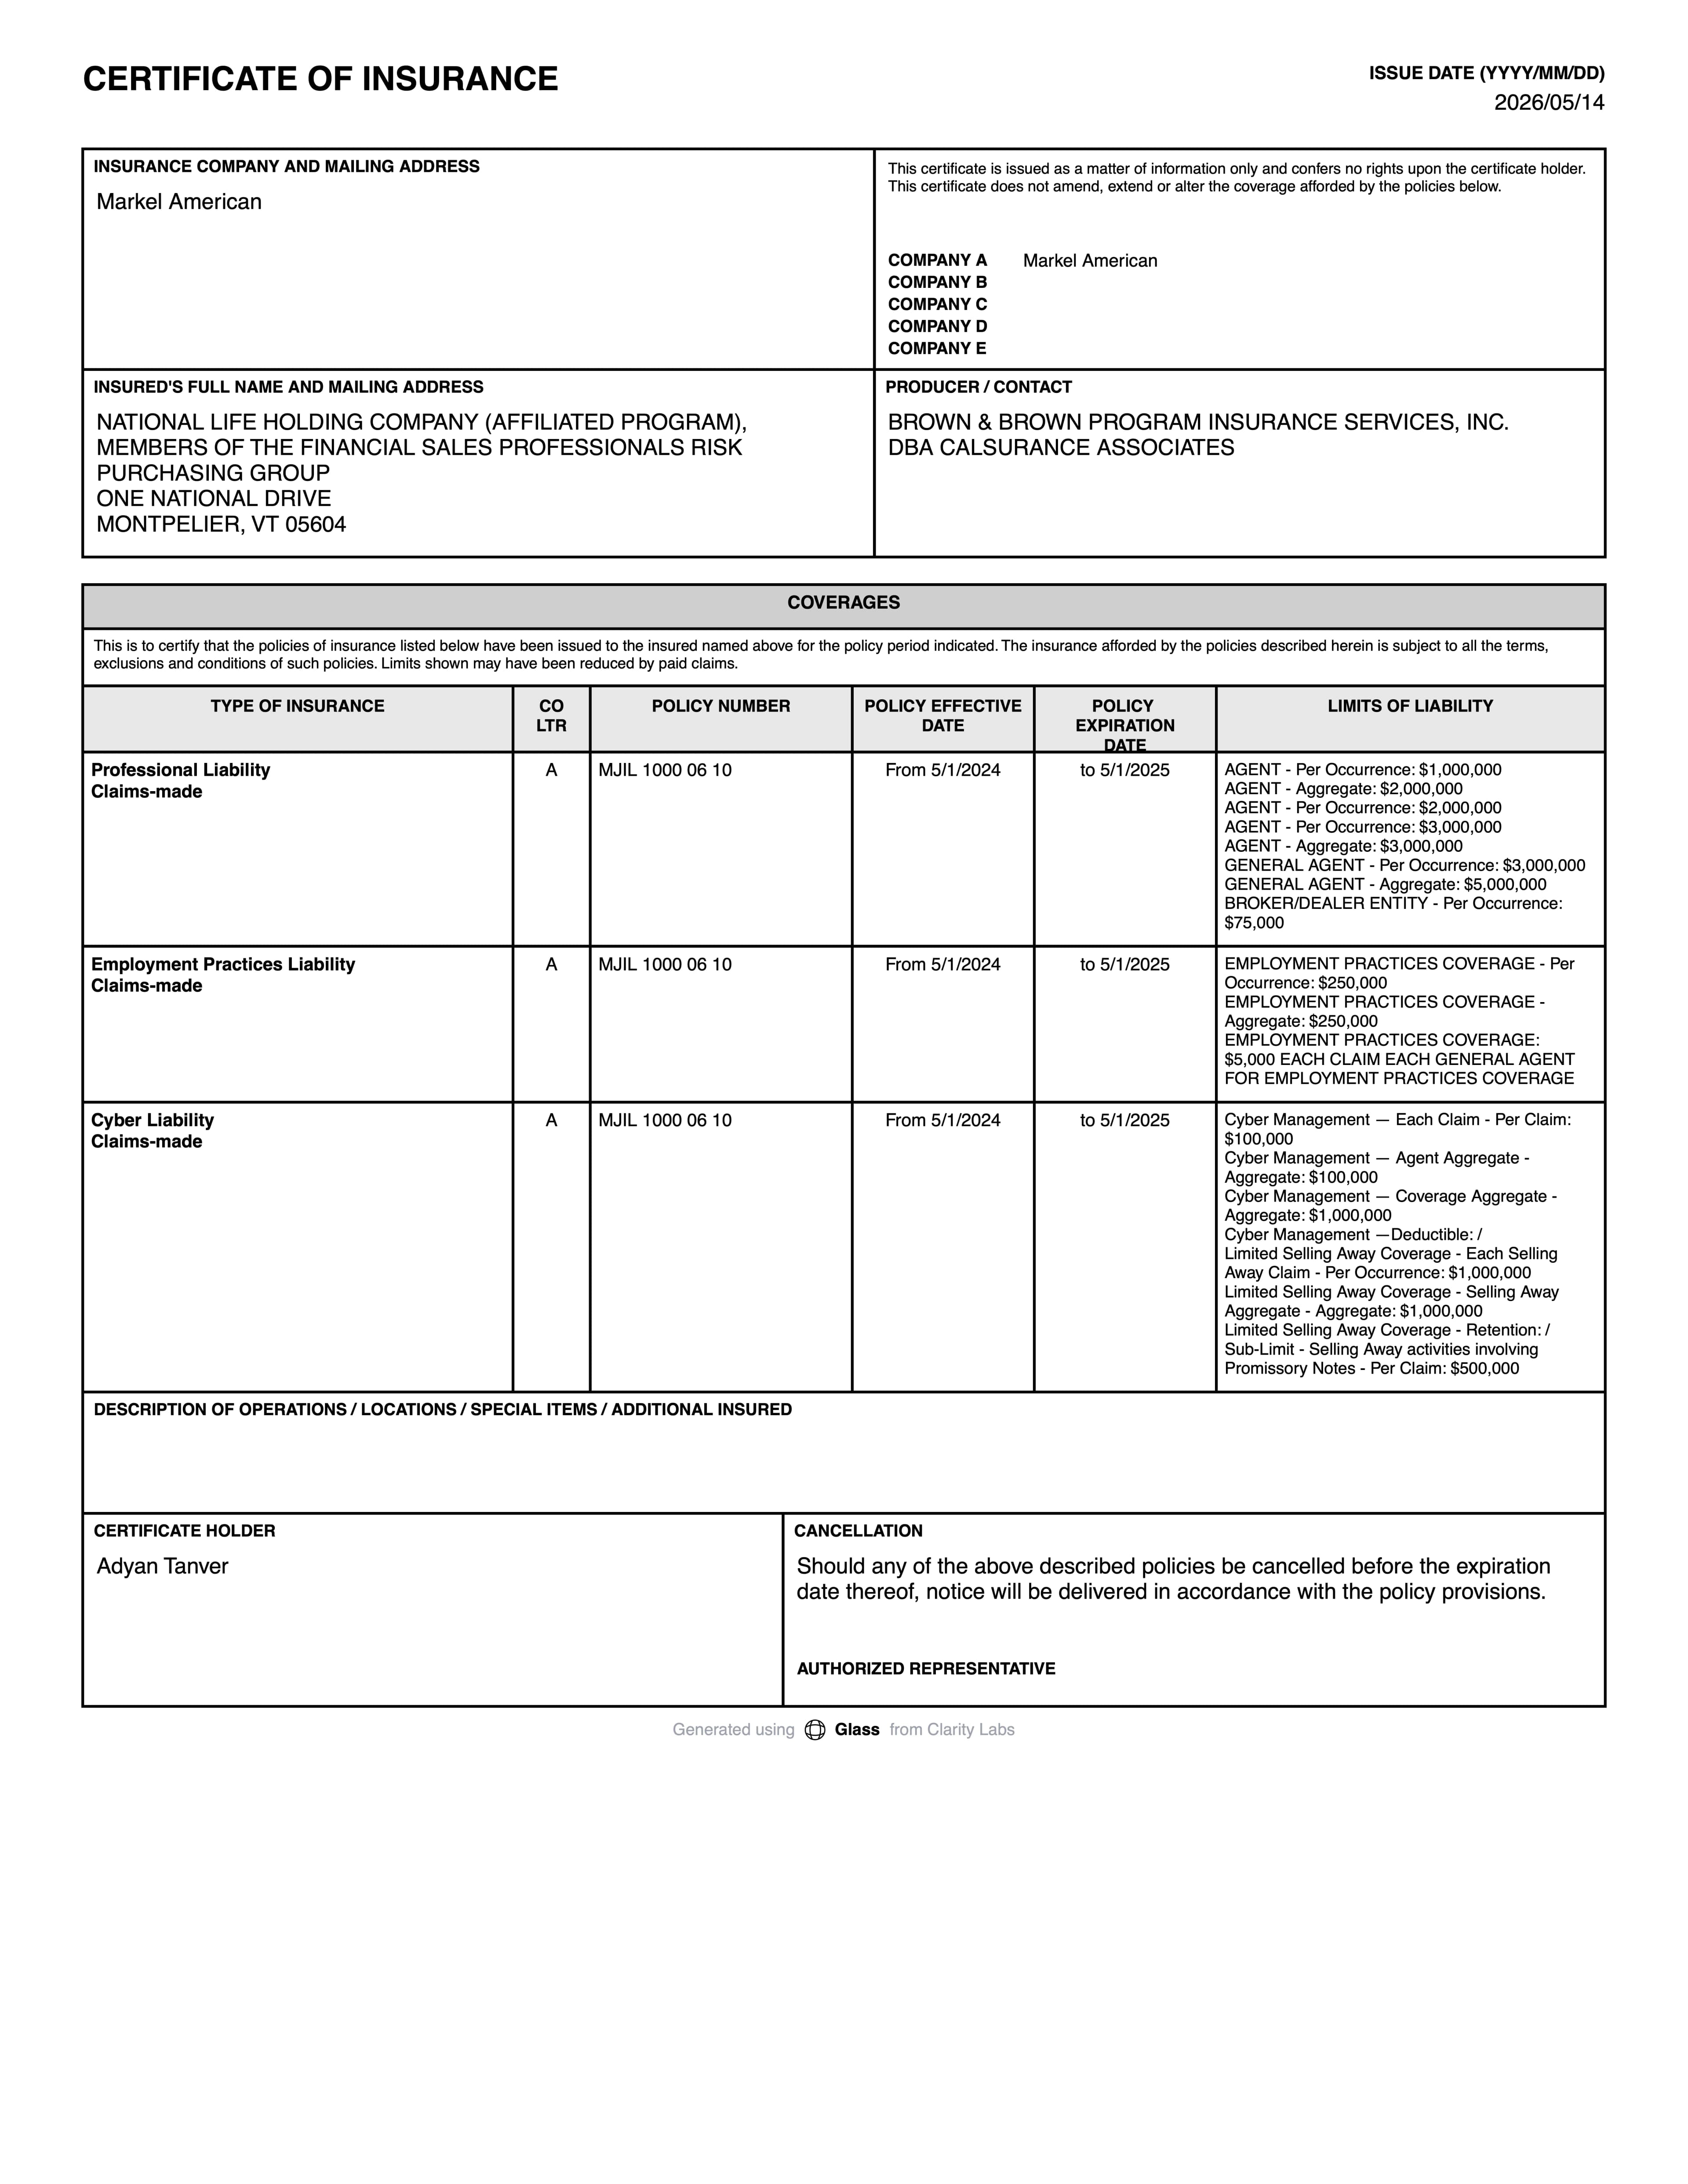
Certificate of insurance
Alder Builders
Ready for your review
Share what you do, where you work, the policies you have and any contracts that ask for insurance.
Spot turns it into an application that describes your business the way insurers need to see it.
Spot handles the procurement, sending it to the insurers and markets that cover businesses like yours and chasing every quote.
We put the quotes side by side on limits, exclusions and terms as well as price.
You choose. Spot places the policy for you, and certificates are ready when a customer or landlord asks.
A project contract can set a liability limit above what your primary policy carries, and you’ll be asked to show it on a certificate.
A serious crash can outrun an auto liability limit, and your auto or trucking policy has to be listed underneath before you count on the layer above it.
A customer or landlord may name a total liability figure that your primary limits alone don’t reach.
General liability, auto and employers liability each carry their own limit, and the layer above should list the ones you rely on.
What each industry usually faces, and where Spot fits in.
A contract or customer asks about limits above your underlying liability policies.
Get quotes from 35+ umbrella and excess liability insurance providers with Spot.
Compare the requirement with your current limits before you sign, and price the layer that closes the difference.
If you want auto claims to reach the umbrella, confirm your auto or trucking policy is on its underlying schedule at the limit the layer expects.
A new general liability or auto policy, or a lower limit on one, can leave the umbrella’s schedule out of step with what’s underneath. Line the two up at the same time.
Bring the current schedule and any contracts signed since the last renewal, and ask whether employment practices, professional liability or product recall exposures are excluded by name.
Also known as commercial umbrella insurance, business umbrella insurance, umbrella liability insurance, excess liability insurance and excess casualty insurance.
Get quotes from 35+ umbrella and excess liability insurance providers with Spot. Keep your broker or switch, with no commissions on premiums.
Get StartedRead these before you choose a policy or an insurer.