Spot for Food and Beverage Companies

Get quotes from 45+ food and beverage insurance providers with Spot

We get quotes for your products and production sites, compare them with you and help you buy before you add a co-packer or taproom.

  • Products, co-packers and cold storage in one submission
  • Recall and spoilage terms read in every quote
  • Keep your broker or switch, with no commissions on premiums
A food maker checks the lid seal on a jar of sauce at a stainless prep table.

How Spot helps Food and Beverage Companies

Tell us how your food gets to customers

Your Spot team gathers your product and ingredient schedule, co-packers, suppliers, cold stores, carriers and sales channels, along with your lot coding and traceability practices.

Alder ManufacturingOrganized by Spot
AIG
Alliance Risk

Amelia Risk

Ask about recall before you need it

As brokers bring back quotes, Spot asks about contamination terms, recall expense forms, sublimits and notice requirements, so you know which withdrawal costs a proposal includes.

Amelia Risk
Alliance Risk
AIGQuote request

Product liability insurance

Coverage limits · Policy terms

Alder Manufacturing

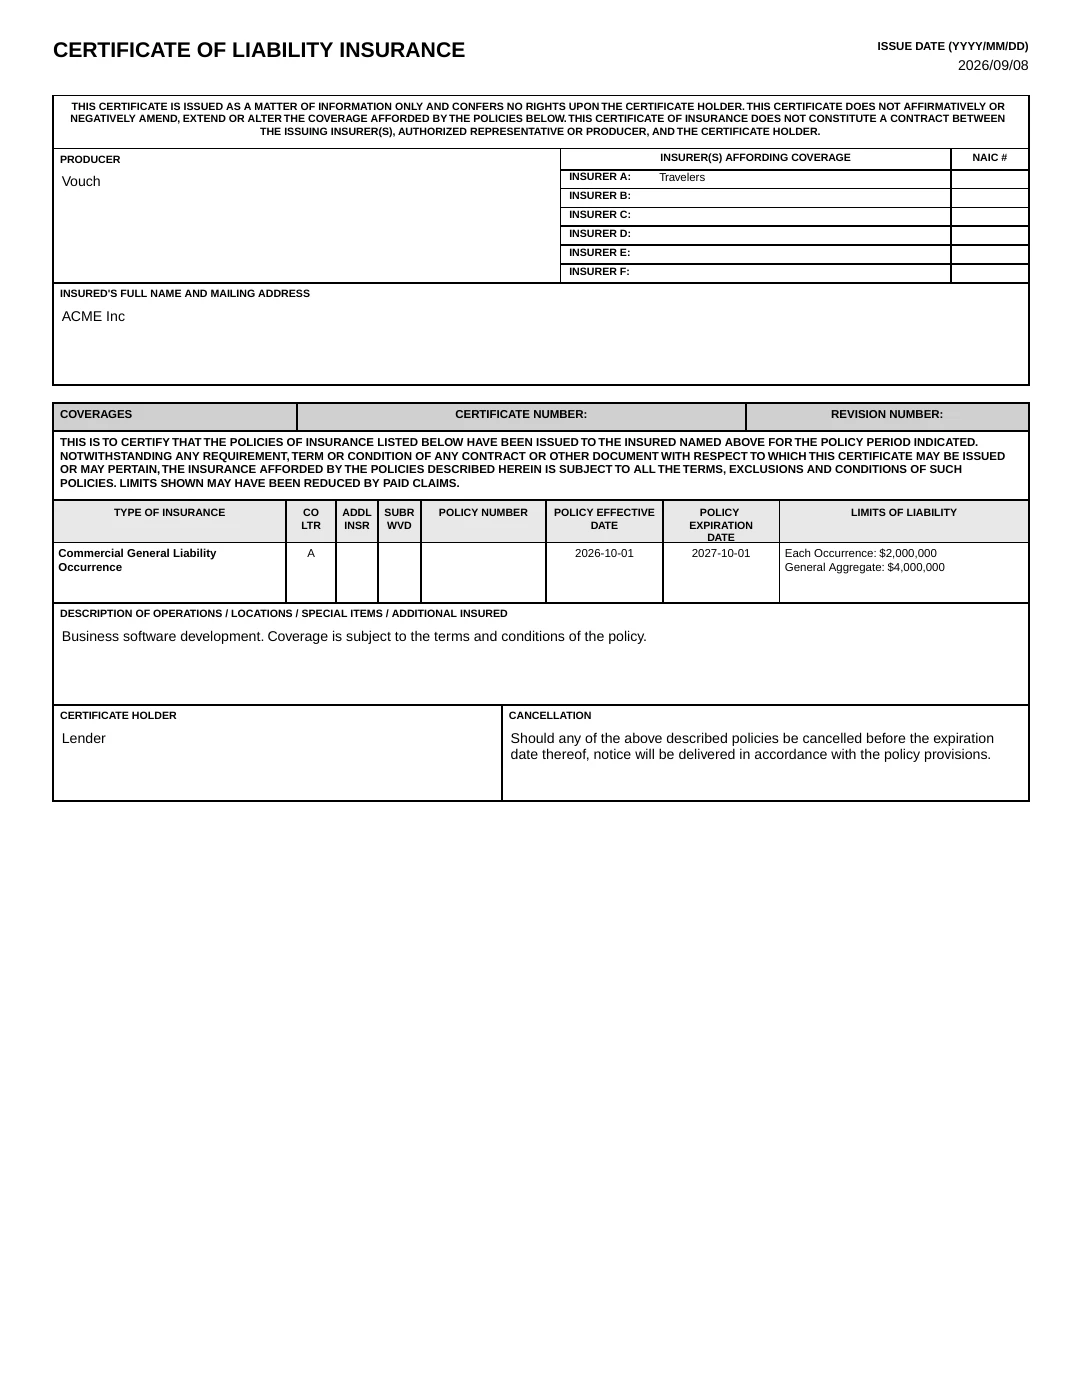
Answer distributor requirements

Distributors and retailers send insurance requirements with their agreements. Spot checks them against your policies and gets your certificate ready.

Product liability insurance

Alder Manufacturing · Policy review

Policy wording
Coverage limits
Compare with
Contract requirements

Confirm with your broker

Limits, exclusions, and endorsements

Keep lot records and policies together

Your product schedule, co-packer agreements and policies stay in one place, so renewal and any incident report start from current records.

MorganAlder Manufacturing

What do we need to request product liability insurance quotes?

Let’s prepare the information for your broker and compare the terms, not just the price.

Product liability insurance policy

Coverage terms · Limits

How buying insurance works for Food and Beverage Companies

  1. 01

    Tell us about your business

    Share what you do, where you work, the policies you have and any contracts that ask for insurance.

  2. 02

    We write up your application

    Spot turns it into an application that describes your business the way insurers need to see it.

  3. 03

    We get quotes from insurers

    Spot handles the procurement, sending it to the insurers and markets that cover businesses like yours and chasing every quote.

  4. 04

    Compare your quotes

    We put the quotes side by side on limits, exclusions and terms as well as price.

  5. 05

    Buy your policy and get certificates

    You choose. Spot places the policy for you, and certificates are ready when a customer or landlord asks.

Food and Beverage Companies we help

  • Packaged food and beverage brands

    Your products reach customers through grocery, wholesale and direct channels, and your product liability application should name each one.

  • Brands working with co-packers

    Your goods are made at someone else’s site, so your property schedule should list the stock there and your product coverage should include what they make.

  • Breweries, wineries and distilleries

    A taproom or tasting room brings guests on site, and the alcohol you serve has to be disclosed.

  • Producers with temperature-sensitive stock

    Refrigeration failure or a warm truck can spoil inventory, and spoilage terms vary by form.

Insurance Food and Beverage Companies usually carry

The policies companies like yours are usually asked for, and when each one comes up.

  • Product liability

    You sell packaged food or beverages through retail, wholesale, delivery, or direct-to-consumer channels.

  • Product recall

    Product recall insurance can pay specified costs to locate and withdraw a product after a covered problem. It fits businesses that could face recall logistics; product liability does not automatically pay those costs, so compare the trigger and covered expenses.

  • Commercial property

    You store ingredients, packaging, finished goods, kitchen equipment, or refrigeration at a production site.

  • Tools, equipment and inland marine

    Ingredients or finished goods travel between a supplier, co-packer, cold store, distributor, and customer.

  • General liability

    Customers visit a taproom, tasting room, restaurant, market stall, or food event.

  • Liquor liability

    Liquor liability can cover claims tied to your business selling, serving or furnishing alcohol. If you run a bar, restaurant or event where you provide drinks, check how the quote treats injuries, property damage and occasional service.

  • Workers’ compensation

    You hire kitchen, warehouse, delivery, or production employees.

Insurers that quote Food and Beverage Companies

Get quotes from 45+ food and beverage insurance providers with Spot.

  • AIG
  • Alliance Risk
  • Amelia Risk
  • Aon
  • Beazley
  • Berkshire Hathaway Specialty Insurance
  • biBerk
  • And many more

When Food and Beverage Companies need insurance

  • 01

    You’re moving production to a co-packer

    Add the co-packer’s site, your stock held there and the products they make to the submission before the first run.

  • 02

    You’re signing a cold-storage contract

    Before stock moves into a third-party cold store, ask what property, breakdown, spoilage and temperature conditions each quoted form includes.

  • 03

    You’ve landed a wholesale or grocery order

    The buyer’s agreement can set product liability limits and additional insured wording. Check them before you ship.

  • 04

    You’re opening a taproom or tasting room

    Seating, tastings, events, food prep and alcohol service all need describing for general liability and liquor liability.

  • 05

    You’re hiring for production or delivery

    Kitchen, warehouse and delivery staff, including seasonal workers, need to be reported for workers’ compensation in each state.

Questions from Food and Beverage Companies

Also known as food business insurance, food company insurance, food manufacturer insurance, beverage company insurance, brewery insurance and food and drink insurance.

What insurance does a food business need before wholesale?

Distributors and retailers usually ask for product liability and a certificate naming them. Many food brands add product recall, property for stock and equipment, and inland marine for goods on the road, and a taproom brings liquor liability. Spot lines them up before the deal.

Does product liability pay for a food recall?

Don’t assume it does. Product liability and recall expense are separate questions. Spot asks for the exact forms and any recall sublimit.

What should we send before opening a taproom?

Describe the premises and how you serve guests: seating, tastings, food preparation, events, delivery, and whether you produce, sell or serve alcohol.

Is spoiled stock covered if a freezer fails?

That’s decided by the property and equipment breakdown terms, which vary between forms. Spot checks how each proposal treats temperature-sensitive stock and spoilage.

How is Spot paid?

Your Spot fee is monthly, tiered by what you spend on insurance each year, and never a commission on premiums. Your broker can keep placing your product and recall coverage, or you can switch to one who knows food and beverage.

Get insurance off your to-do list.

Get quotes from 45+ food and beverage insurance providers with Spot. Keep your broker or switch, with no commissions on premiums.

Get Started