Insurance Required by a Commercial Lease

Get the insurance your commercial lease requires

Send us the lease’s insurance section, and your Spot team turns it into coverage you can buy and a certificate your landlord will accept.

  • The lease’s insurance clause read against real quotes
  • Additional insured and waiver wording requested before you bind
  • Keep your broker or switch, with no commissions on premiums
A tenant receives keys from a property manager beside a storefront doorway.

How it works

Send us the insurance section of your lease

Leases usually put insurance in its own article or exhibit. Upload the lease or just those pages, and tell us your move-in or build-out date.

General liability insurance

Maple Market · Policy review

Policy wording
Coverage limits
Compare with
Contract requirements

Confirm with your broker

Limits, exclusions, and endorsements

We list what the landlord requires

Your Spot team pulls out each coverage, the limits, who must be named as an additional insured and any waiver or notice wording, so nothing is left for the last week.

Maple MarketOrganized by Spot

Compare quotes that meet the clause

We work with brokers to get quotes written to the lease, then show which ones include the endorsements the landlord asked for and which would need them added.

Insurance documents

Requirements review

General liability insurance

Coverage limits · Policy terms

Maple Market

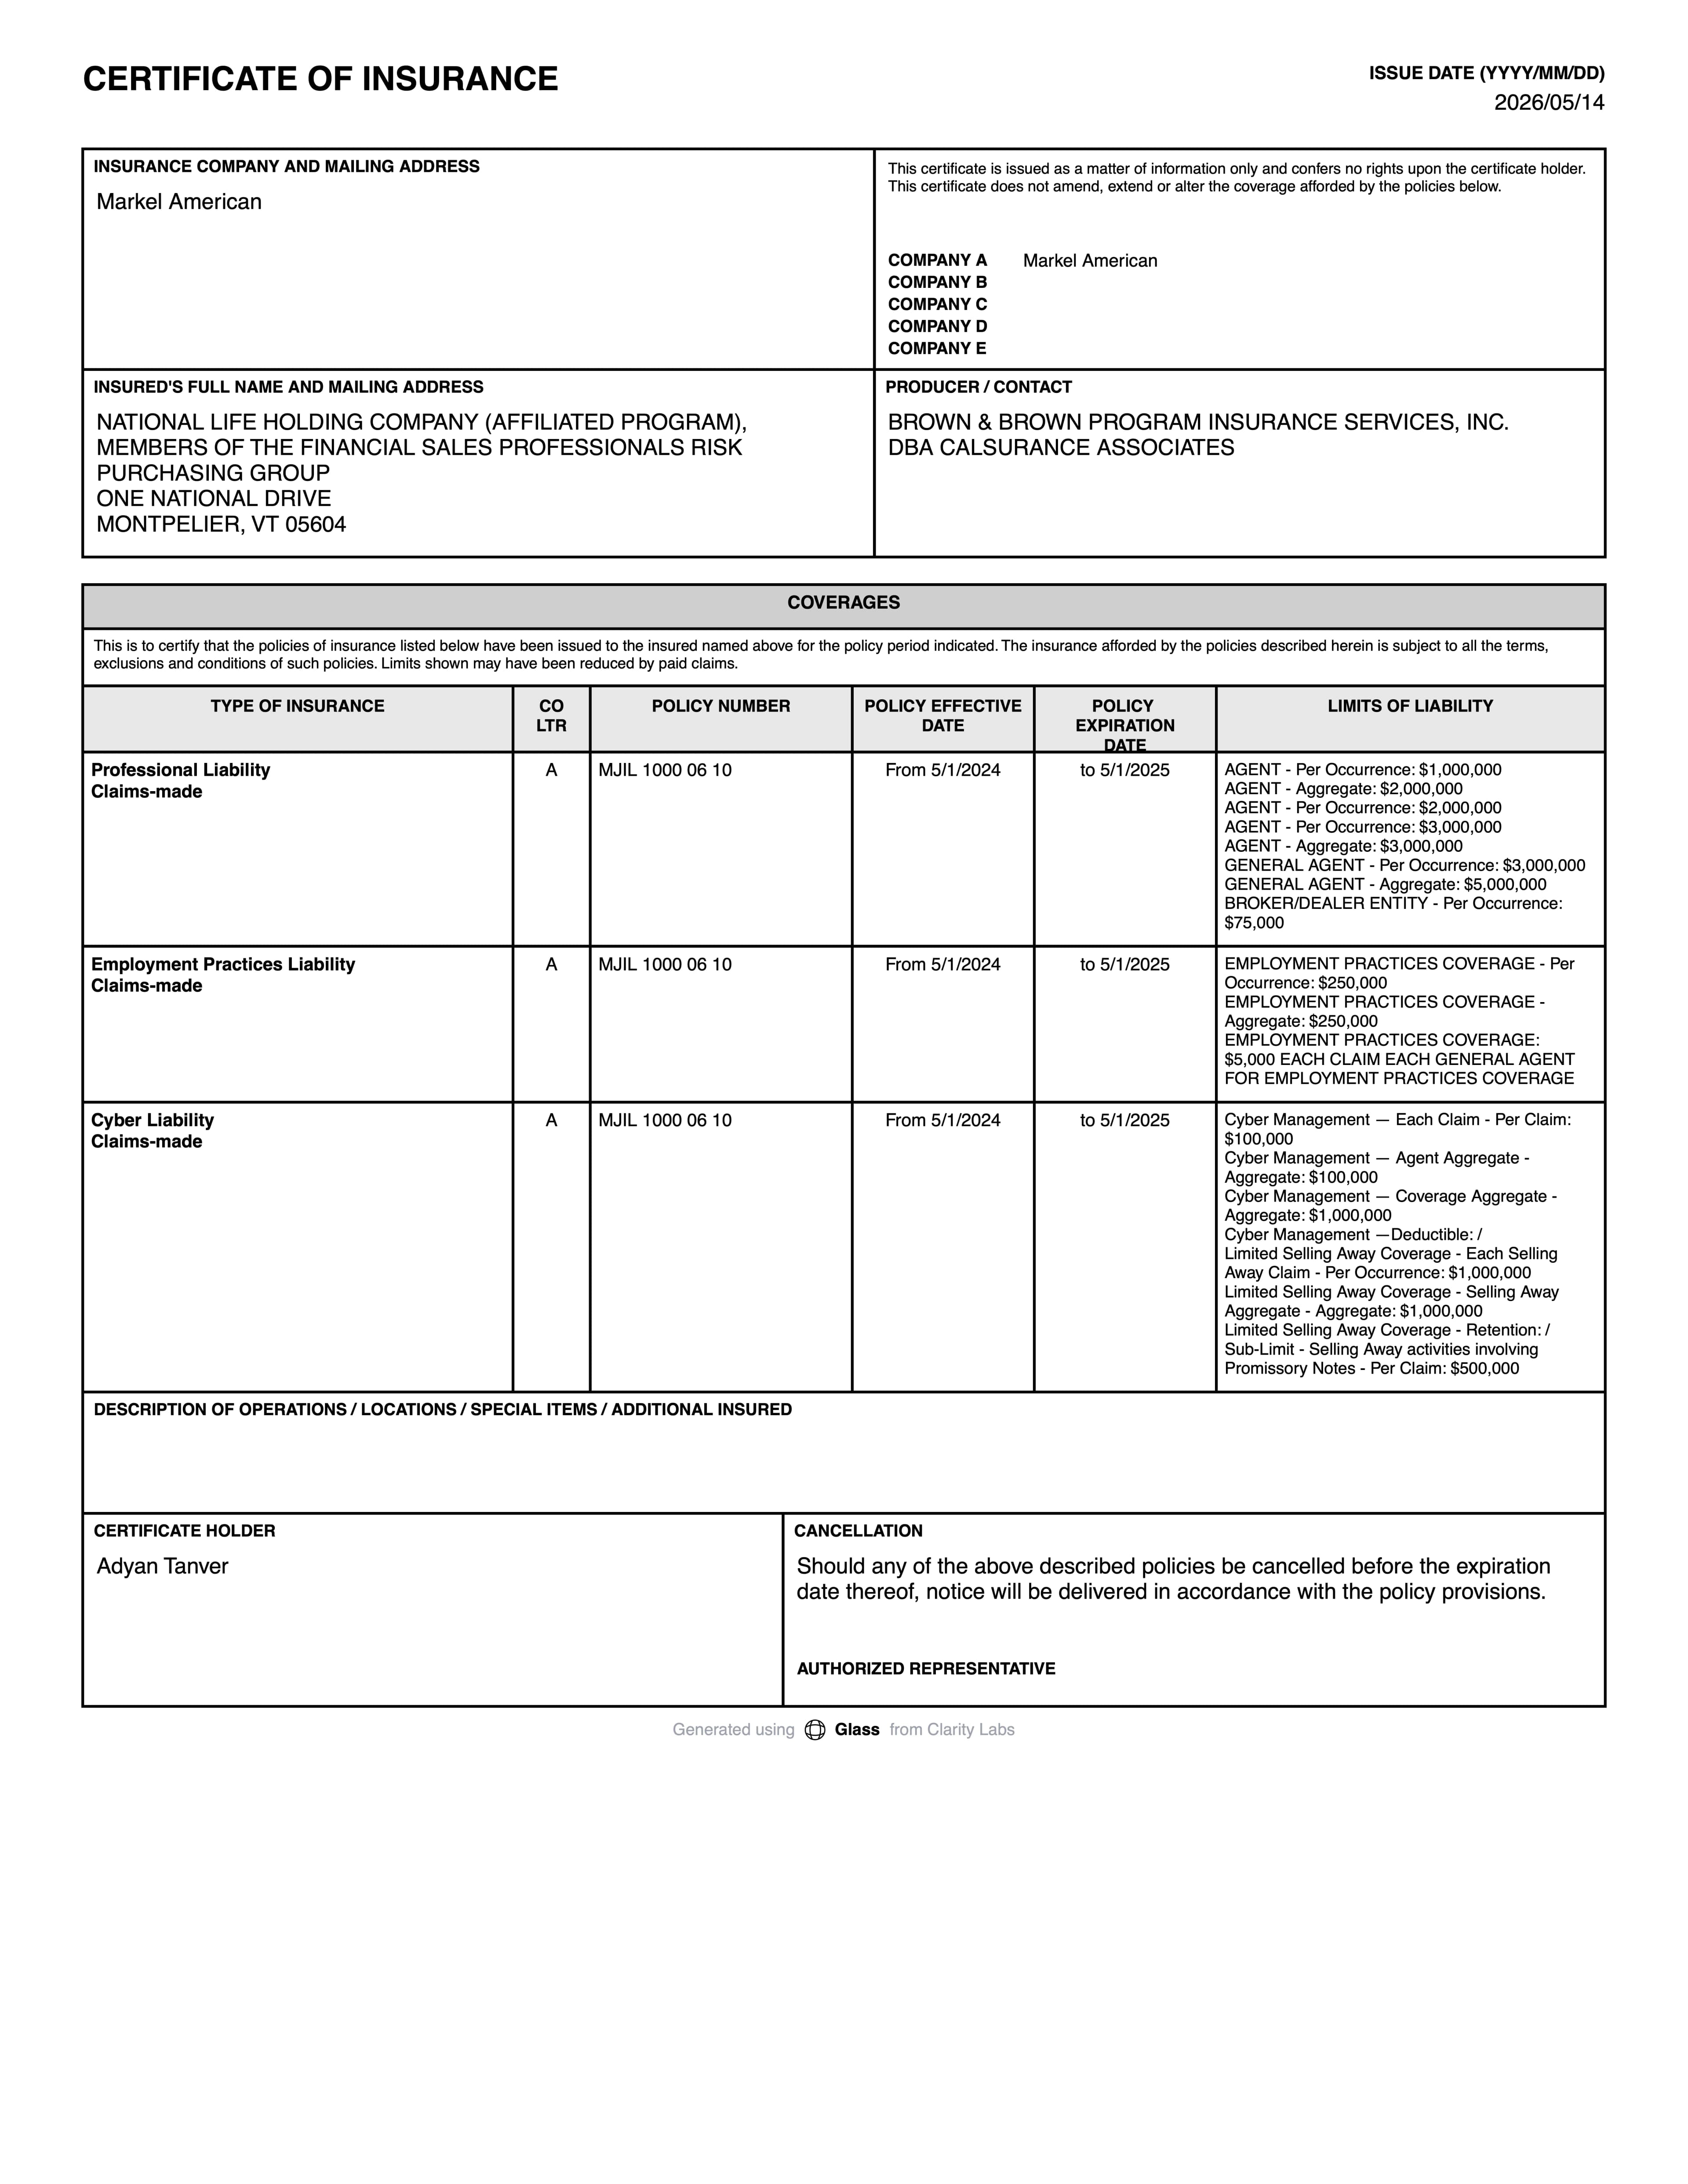
Send the certificate to your landlord

Once the policy is bound, you generate the certificate in the Spot app with the landlord as certificate holder and send it to their property manager.

JordanMaple Market

Can you help prepare proof of our general liability insurance?

Certificate of insurance

Maple Market

Ready for your review

When you need insurance

Your lease says you need insurance in place, and proof of it on file, before you get the keys.

Coverage to consider

  • General liability

    Landlords usually require it, because it responds when a visitor or customer says your business injured them or damaged their property.

    Get quotes
  • Commercial property

    The landlord’s policy is for the building. Your furniture, equipment and stock, and any improvements the lease makes yours to insure, need your own property coverage.

    Get quotes
  • Business owner’s policy

    An eligible small business can package property, liability and lost-income protection in one policy, which can cover most of a typical lease clause.

    Get quotes
  • Umbrella and excess liability

    When the lease sets liability limits above your primary policy, an umbrella or excess layer can sit on top, if your general liability is listed underneath it.

    Get quotes
  • Workers’ compensation

    If you have employees, your state’s rules decide whether you must carry it, and the lease may list it too.

    Get quotes

Documents to have ready

  • 01

    The lease’s insurance clause

    The article or exhibit that lists coverages, limits and endorsements. If you only have a letter of intent, send that and the landlord’s standard lease form.

  • 02

    The landlord’s exact legal name

    The owner entity, the property manager and any lender the lease names, spelled as the lease spells them. They often go on the certificate.

  • 03

    The space and your plans for it

    The address, square footage and what you’ll spend on build-out, so property quotes can value the improvements you’re paying for.

  • 04

    What you’ll keep inside

    A rough value of furniture, computers, equipment and stock you’ll move in.

  • 05

    Your current policies

    If you already have insurance at another location, send the policies so your Spot team can check whether adding this address is enough.

Common questions

Can I just add the new space to my current policy?

Often, yes. Your Spot team checks whether your current policies can add the location and the landlord’s endorsements, and only takes it to market if they can’t.

Does naming my landlord on the certificate make them an additional insured?

No. Listing the landlord as certificate holder changes nothing in the policy. Additional insured status needs an endorsement, which your Spot team requests through your broker and insurer.

My lease asks for a waiver of subrogation. What does that mean for me?

It means your insurer agrees not to pursue the landlord to recover what it pays on a claim. It has to be added to the policy by endorsement, and we ask for it before you bind.

Do I need to switch brokers to use Spot?

No. Spot works with your current broker if you have one, takes no commissions on premiums and can introduce you to a different broker if you’d rather.

Get insurance off your to-do list.

Send us the lease’s insurance section, and your Spot team turns it into coverage you can buy and a certificate your landlord will accept.

Get Started

Learn more before you find insurance

Read these before you choose a policy or an insurer.