Certificate of Insurance for a Lender

Give your lender the proof of insurance their loan requires

Generate the liability certificate your lender wants in the Spot app, and your Spot team gets the lender named on your property policy where the loan requires it.

  • The loan’s insurance terms checked before closing
  • Lender named on your property policy through your broker
  • Keep your broker or switch, with no commissions on premiums
A business owner and lending officer inspect a compact industrial lathe beside a plain document folder.

How it works

Send the loan’s insurance terms

Upload the commitment letter, loan agreement or closing checklist. Your Spot team lists the coverage and lender wording it requires.

Commercial property insurance

Juniper Properties · Policy review

Policy wording
Valuation clause
Compare with
Declared values

Confirm with your broker

Replacement cost or actual cash value?

Get the lender on your policies

We work with your broker and insurer to add the lender as mortgagee or loss payee on property and as additional insured on liability, as the loan asks.

# spot-support

TaylorJuniper Properties

Can you help prepare proof of our commercial property insurance?

RileySpot

Let’s check the valuation clause, declared property values, and deductible in your policy.

Generate proof for closing

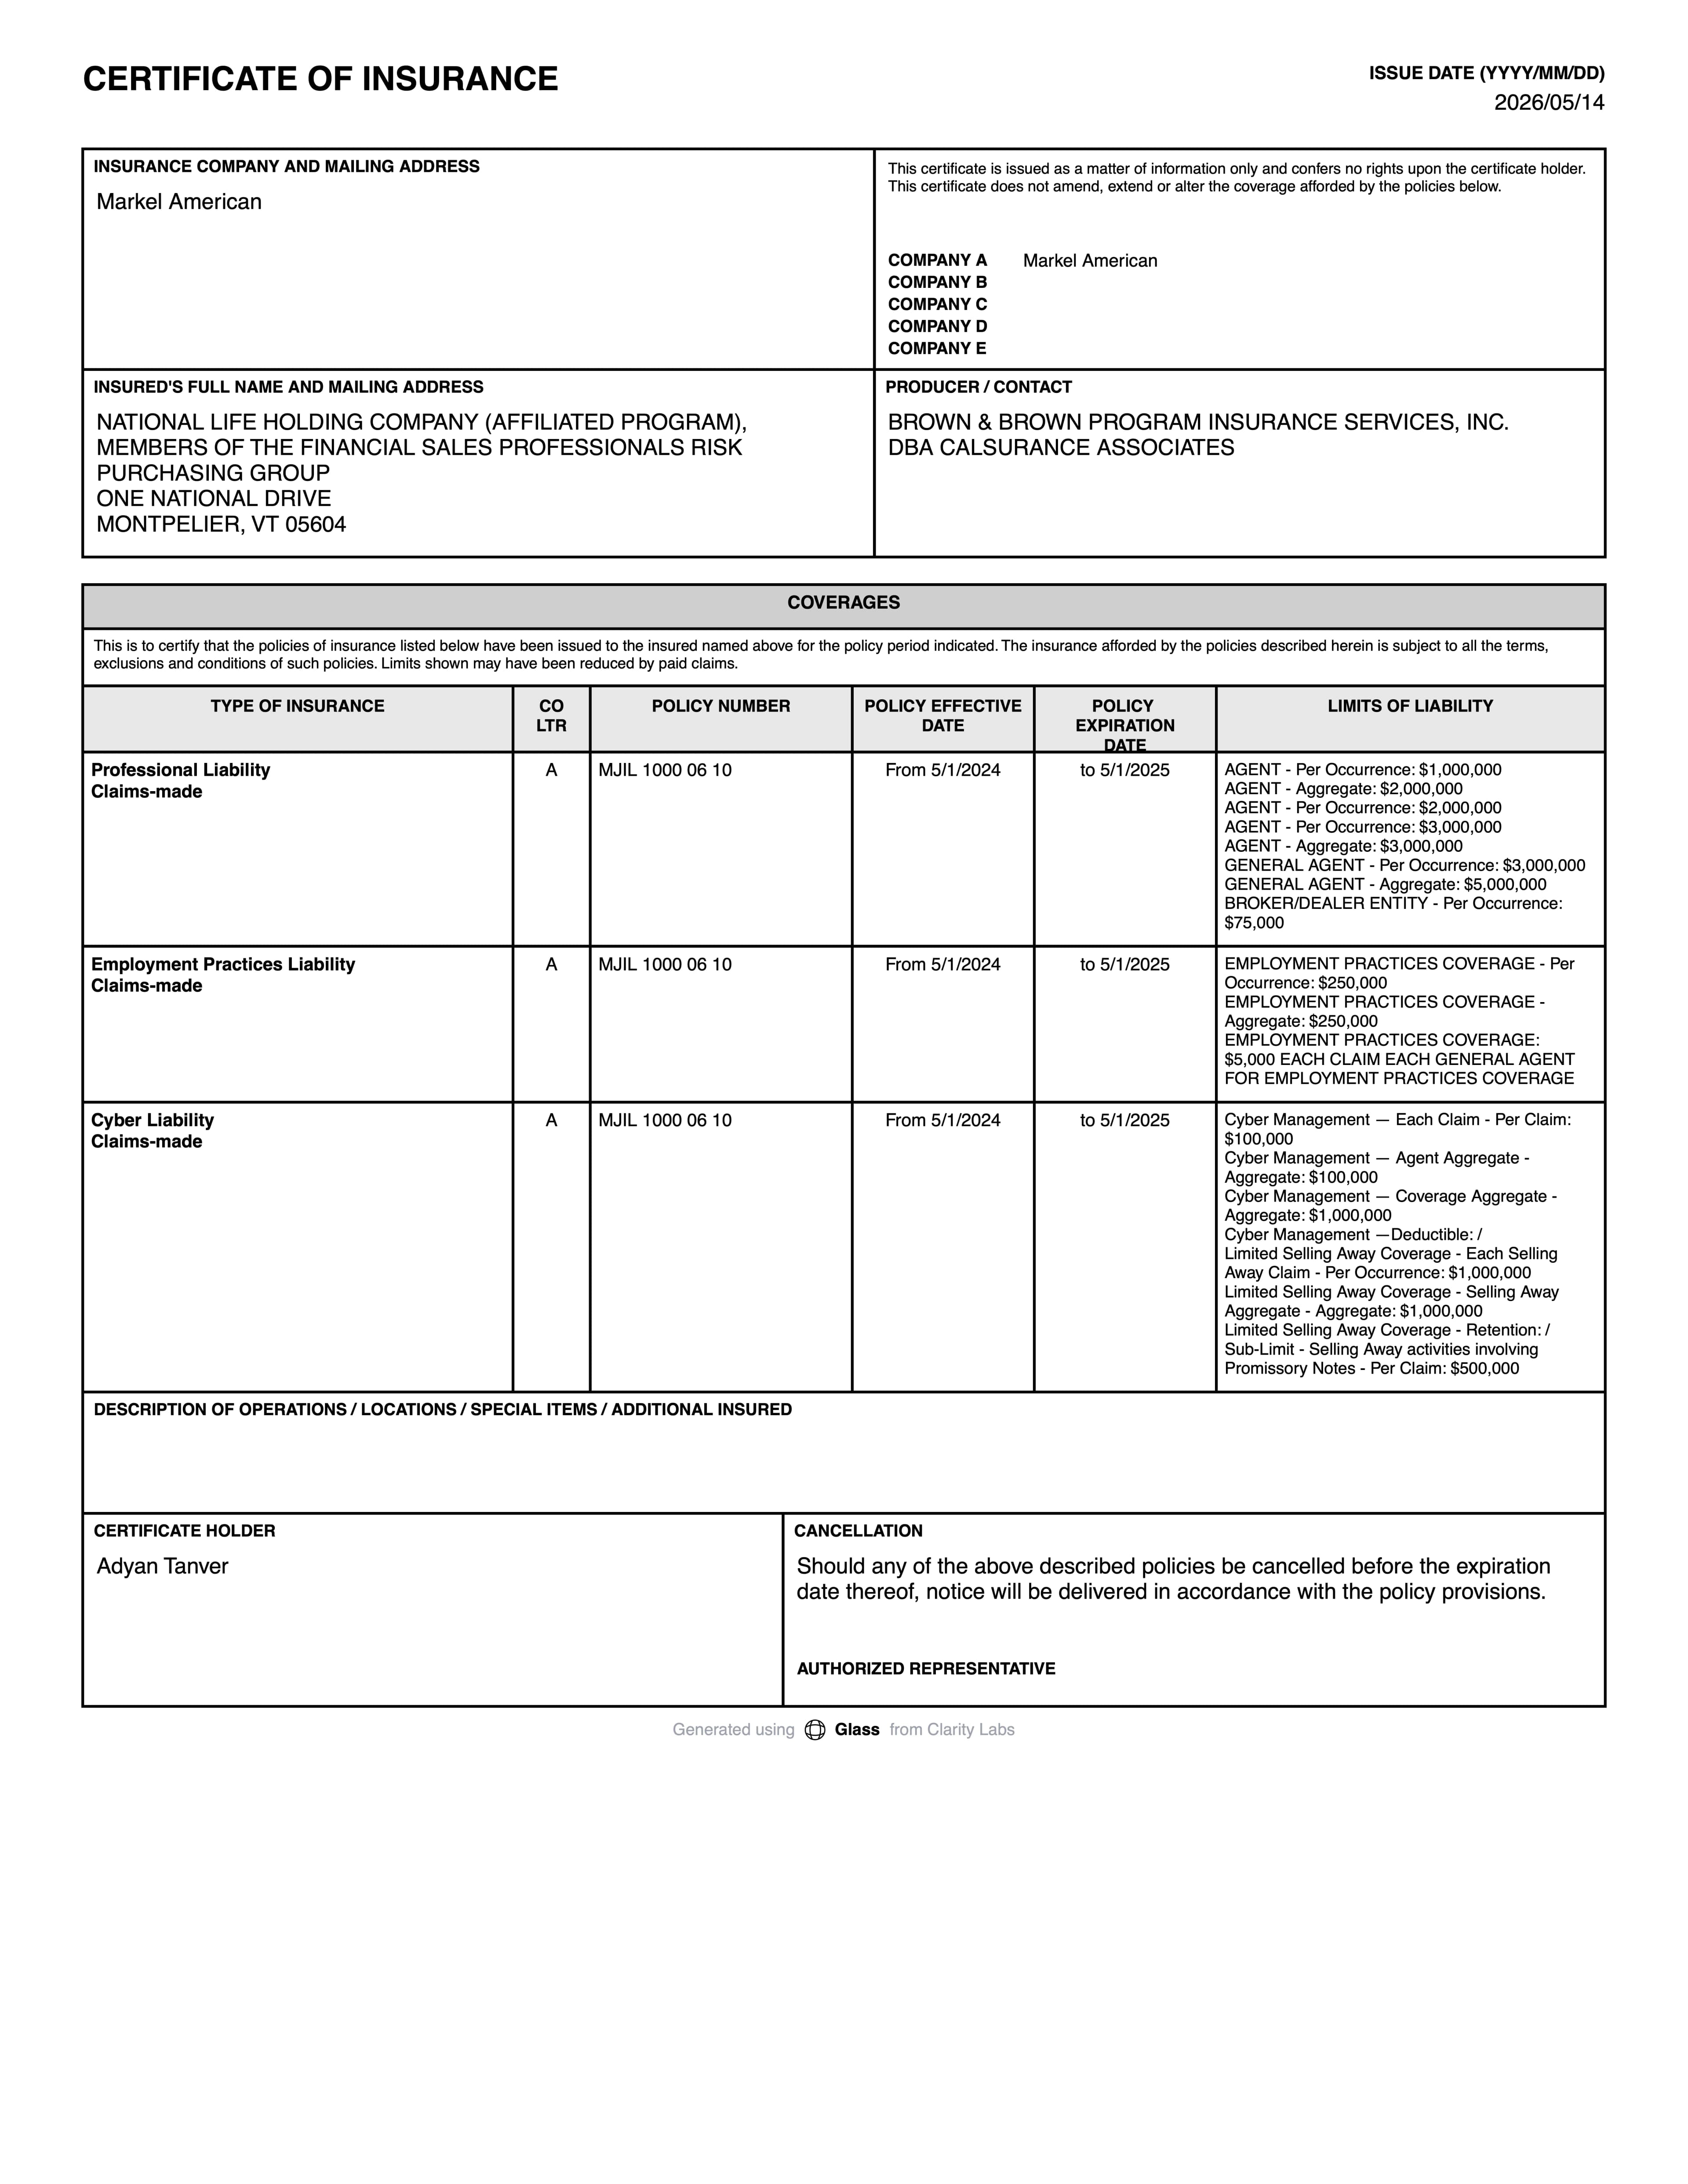
Create the liability certificate in the Spot app with the lender as certificate holder, and send it to their closing team.

TaylorJuniper Properties

Can you help prepare proof of our commercial property insurance?

Certificate of insurance

Juniper Properties

Ready for your review

Keep the lender current

Lenders track renewal dates. Your renewed policies sit in your Spot workspace, so you can send new proof when they ask.

TaylorJuniper Properties

Can you help prepare proof of our commercial property insurance?

Let’s check the valuation clause, declared property values, and deductible in your policy.

Commercial property insurance policy

Valuation · Deductibles

What your certificate needs to show

  • 01

    Property insurance on the collateral

    Cover for the building or equipment the loan finances, valued the way the loan agreement asks.

  • 02

    Lender as mortgagee or loss payee

    So the lender is paid on a covered property loss to the collateral, as the loan terms set out.

  • 03

    General liability

    With the lender often listed as an additional insured, especially on real estate loans.

  • 04

    Property evidence on the lender’s form

    Many lenders want property evidence on a separate property form, such as ACORD 28, as well as a liability certificate.

  • 05

    Notice of cancellation

    The lender wants to hear if the policy is cancelled. That’s set by policy provisions, not by the certificate’s wording.

Endorsements to check

  • 01

    Mortgagee or loss payee

    Names the lender on the property policy so it shares in payment for covered damage to the collateral. Your Spot team has your broker request it from the insurer.

  • 02

    Additional insured

    Extends your liability policy to the lender for claims tied to the property or your operations, as the endorsement words it.

  • 03

    Lender notice of cancellation

    Where available, an endorsement that commits the insurer to notify the lender. A certificate can’t promise notice on its own.

Generate your certificate in Spot

  • 01

    Choose the policies the lender wants

    Pick your liability policies, and the property policy that insures the collateral.

  • 02

    Add the lender

    Enter the lender’s legal name and the address its loan servicing team uses, with “its successors and assigns” if the loan asks.

  • 03

    Add the loan details

    Upload the closing checklist or list the requirements, including the loan number and property address for the description.

  • 04

    Review, then send

    Confirm the lender’s name, the collateral and the dates, then download the certificate or send it to the closing team.

Mistakes to avoid

  • 01

    Certificate holder without the endorsement

    Listing the lender as certificate holder doesn’t make it a mortgagee or loss payee. The policy has to say so.

  • 02

    Missing successors and assigns

    Many loans are sold or serviced by someone else. Use the exact lender clause the loan documents give.

  • 03

    Waiting until the week of closing

    Endorsements and property evidence take time. Send the lender’s requirements as soon as you have them.

Coverage to consider

  • Commercial property

    Commercial property insurance with Spot: every location prepared for the market and proposals compared on valuation, coinsurance, deductibles and exclusions.

    Explore coverage
  • General liability

    Buy general liability with Spot: we prepare your submission, compare broker proposals on limits and terms, and get certificates and endorsements ready.

    Explore coverage
  • Business owner’s policy

    Buy a business owner’s policy with Spot: a prepared submission, packages compared on property, liability and income terms, and certificates ready when asked.

    Explore coverage
  • Builders risk

    Builders risk insurance with Spot: your project prepared for the market and proposals compared on covered property, policy period and deductibles.

    Explore coverage
  • Tools, equipment and inland marine

    Buy inland marine with Spot: your equipment inventory prepared, proposals compared on scheduling, valuation and territory, and policy documents kept together.

    Explore coverage
  • Umbrella and excess liability

    Umbrella and excess liability with Spot: contract limits checked, the underlying schedule confirmed and attachment terms compared before you bind.

    Explore coverage

Common questions

Can I generate the lender’s certificate myself?

Yes. Spot customers create liability certificates in the Spot app from their own policies. If the lender wants property evidence on its own form, your Spot team gets it from your broker.

What’s the difference between a mortgagee and an additional insured?

A mortgagee or loss payee is paid on covered damage to the collateral under your property policy. An additional insured is covered for claims under your liability policy. Loans often ask for both.

Does naming the lender on the certificate protect their interest?

No. The certificate shows what the policies say. The lender has to be named on the policy by endorsement, which your Spot team requests through your broker and insurer.

Do I need to change brokers for my loan?

No. Your current broker can keep the account, and Spot takes no commissions on premiums. If they can’t meet the loan’s terms, we can introduce another.

Get insurance off your to-do list.

Generate the liability certificate your lender wants in the Spot app, and your Spot team gets the lender named on your property policy where the loan requires it.

Learn more about certificates of insurance

Read these before you choose a policy or an insurer.