Spot for Banking and Exchange Companies

Get quotes from 50+ banking and exchange insurance providers with Spot

We prepare your application for brokers who know markets and custody, compare the quotes with you and keep your bond requests on track.

  • Customer-asset duties and trading systems described clearly
  • Bond requests traced back to the exact rule or contract
  • Keep your broker or switch, with no commissions on premiums
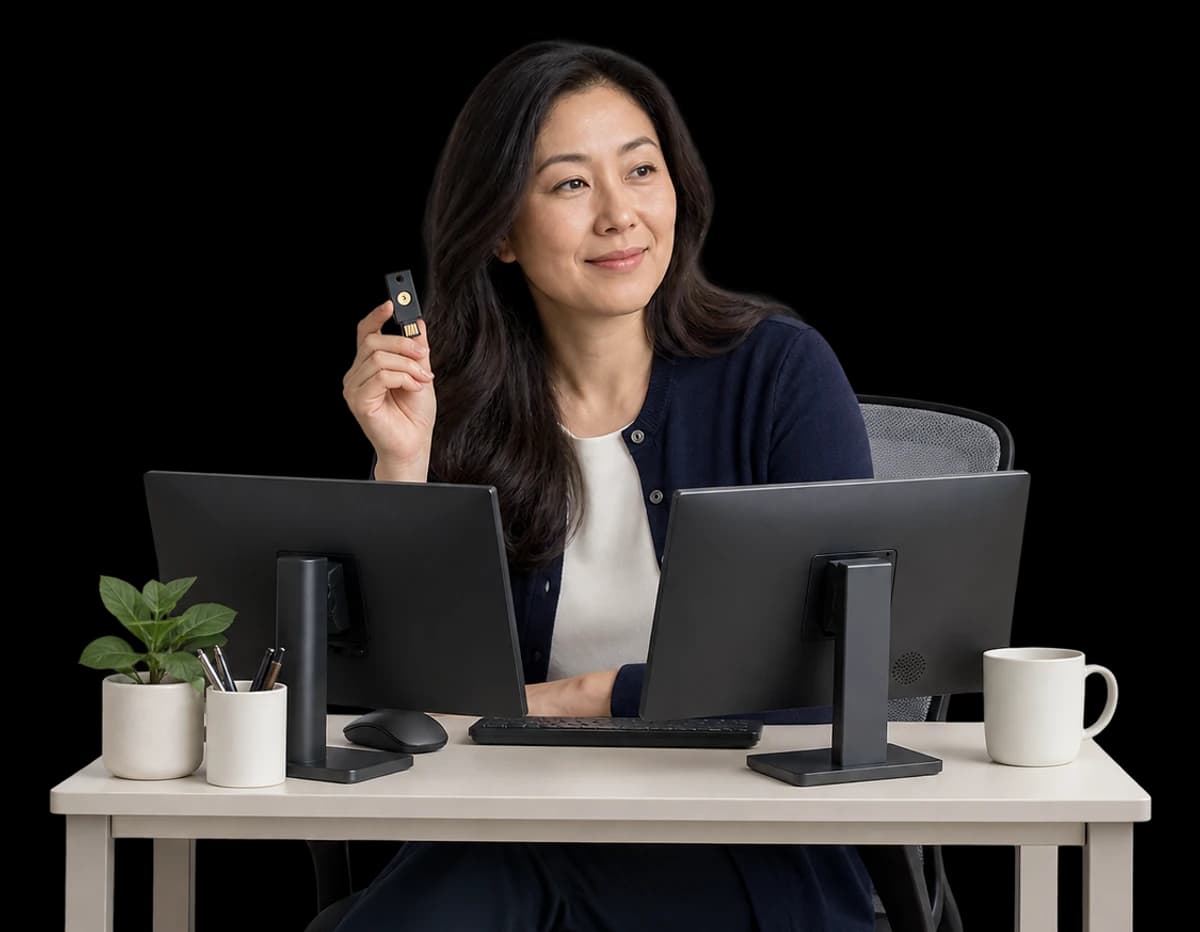
A custody operations lead at her desk holds up a hardware security key.

How Spot helps Banking and Exchange Companies

Describe each service and the systems behind it

Your Spot team describes each entity’s role, the customer assets it touches, the services it provides and the systems and vendors it depends on.

Cedar AdvisoryOrganized by Spot
Travelers
The Hartford
Chubb

Find the rule behind a bond request

When a regulator, clearing firm or counterparty raises a bond, Spot asks for the exact rule or contract, entity, covered people, form and limit, and applies it only to that scope.

Professional errors and omissions (E&O) insurance

Cedar Advisory · Policy review

Policy wording
Coverage limits
Compare with
Contract requirements

Confirm with your broker

Limits, exclusions, and endorsements

Compare quotes on trading errors and outages

We work with your broker to take the submission to market, then walk a trade or settlement error, an intrusion, a provider outage and employee theft through every proposal.

Chubb
The Hartford
TravelersQuote request

Professional errors and omissions (E&O) insurance

Professional services · Claims-made terms

Cedar Advisory

Prepare for the bank’s vendor review

Your policies, contracts and service description stay together, so the next due diligence request is answered from current documents.

JamieCedar Advisory

What do we need to request professional errors and omissions (e&o) insurance quotes?

Let’s prepare the information for your broker and compare the terms, not just the price.

Professional errors and omissions (E&O) insurance policy

Coverage terms · Limits

How buying insurance works for Banking and Exchange Companies

  1. 01

    Tell us about your business

    Share what you do, where you work, the policies you have and any contracts that ask for insurance.

  2. 02

    We write up your application

    Spot turns it into an application that describes your business the way insurers need to see it.

  3. 03

    We get quotes from insurers

    Spot handles the procurement, sending it to the insurers and markets that cover businesses like yours and chasing every quote.

  4. 04

    Compare your quotes

    We put the quotes side by side on limits, exclusions and terms as well as price.

  5. 05

    Buy your policy and get certificates

    You choose. Spot places the policy for you, and certificates are ready when a customer or landlord asks.

Banking and Exchange Companies we help

  • Broker-dealers

    Trade errors, customer losses and fidelity-bond questions all depend on which services and capacities your firm actually holds.

  • Exchanges and trading venues

    A trading system outage or intrusion can stop the market you run, so cyber and technology terms need to describe it.

  • Trading technology providers

    Other firms rely on your order routing, connectivity and market data, and a delay can become their financial loss.

  • Banking platforms

    A partner bank’s vendor review asks about your service, and the contract sets the terms you’ll be held to.

Insurance Banking and Exchange Companies usually carry

The policies companies like yours are usually asked for, and when each one comes up.

  • Professional errors and omissions (E&O)

    The firm provides brokerage, clearing, exchange, advisory, operational, or other professional services to customers.

  • Technology errors and omissions (E&O)

    You provide order handling, exchange connectivity, trading software, data feeds, or operational technology to another firm.

  • Crime

    Employees or systems can access customer property, change instructions, or move money or securities.

  • Fidelity bonds

    An applicable SRO rule, regulator, clearing relationship, or signed counterparty agreement raises a fidelity-bond question.

  • Cyber liability

    The firm holds customer or market information, operates a trading system, or relies on a material technology provider.

  • Directors and officers

    Governance changes, outside directors, investors, or management decisions prompt a liability review.

Insurers that quote Banking and Exchange Companies

Get quotes from 50+ banking and exchange insurance providers with Spot.

  • AIG
  • Alliance Risk
  • Amelia Risk
  • Aon
  • At-Bay
  • Beazley
  • Berkshire Hathaway Specialty Insurance
  • And many more

When Banking and Exchange Companies need insurance

  • 01

    A clearing firm or regulator asks for a bond

    Verify the current rule for your exact firm, then compare the bond form, covered persons and limits.

  • 02

    A bank partner starts its vendor review

    Send your service description and the relevant contract terms, then check how your policies treat the obligations it expects.

  • 03

    You’re adding outside directors or investors

    New governance brings directors and officers questions, including regulatory and financial-services exclusions.

  • 04

    You’re launching a new trading system

    New systems and providers change your cyber and technology exposure. Describe them before go-live.

Questions from Banking and Exchange Companies

Also known as broker-dealer insurance, brokerage firm insurance, crypto exchange insurance, trading platform insurance, neobank insurance and banking platform insurance.

Is broker-dealer insurance just the fidelity bond?

No. The bond answers a regulatory requirement; your firm usually also weighs professional and technology E&O, crime, cyber and D&O. Spot keeps the bond request separate and compares the rest together.

Do all broker-dealers need the same fidelity bond?

No. Requirements depend on the rules that apply to your firm. Spot asks the requester for the exact rule and checks the bond form against it.

Do customer-protection rules replace commercial insurance?

No. Financial-responsibility rules address safeguards for customer assets. Your firm’s own claims are a separate commercial insurance question.

Is a bond the same as a crime policy?

No. A bond request names its own form, covered persons and limit, and a crime proposal is a separate comparison. Spot checks each one against the losses and property in your operations.

Our broker already places our fidelity bond. Does Spot need to take that over?

No. Spot works with your broker on the bond request and the commercial program, and takes no commissions on premiums. If you want a broker with more financial-institution markets, Spot can help you switch.

Get insurance off your to-do list.

Get quotes from 50+ banking and exchange insurance providers with Spot. Keep your broker or switch, with no commissions on premiums.

Get Started