Get Help With Insurance Buying and Renewals.
Get help buying coverage and managing renewals, with less paperwork for your team. Create your account and submit an insurance request online.
Get help buying coverage and managing renewals, with less paperwork for your team. Create your account and submit an insurance request online.
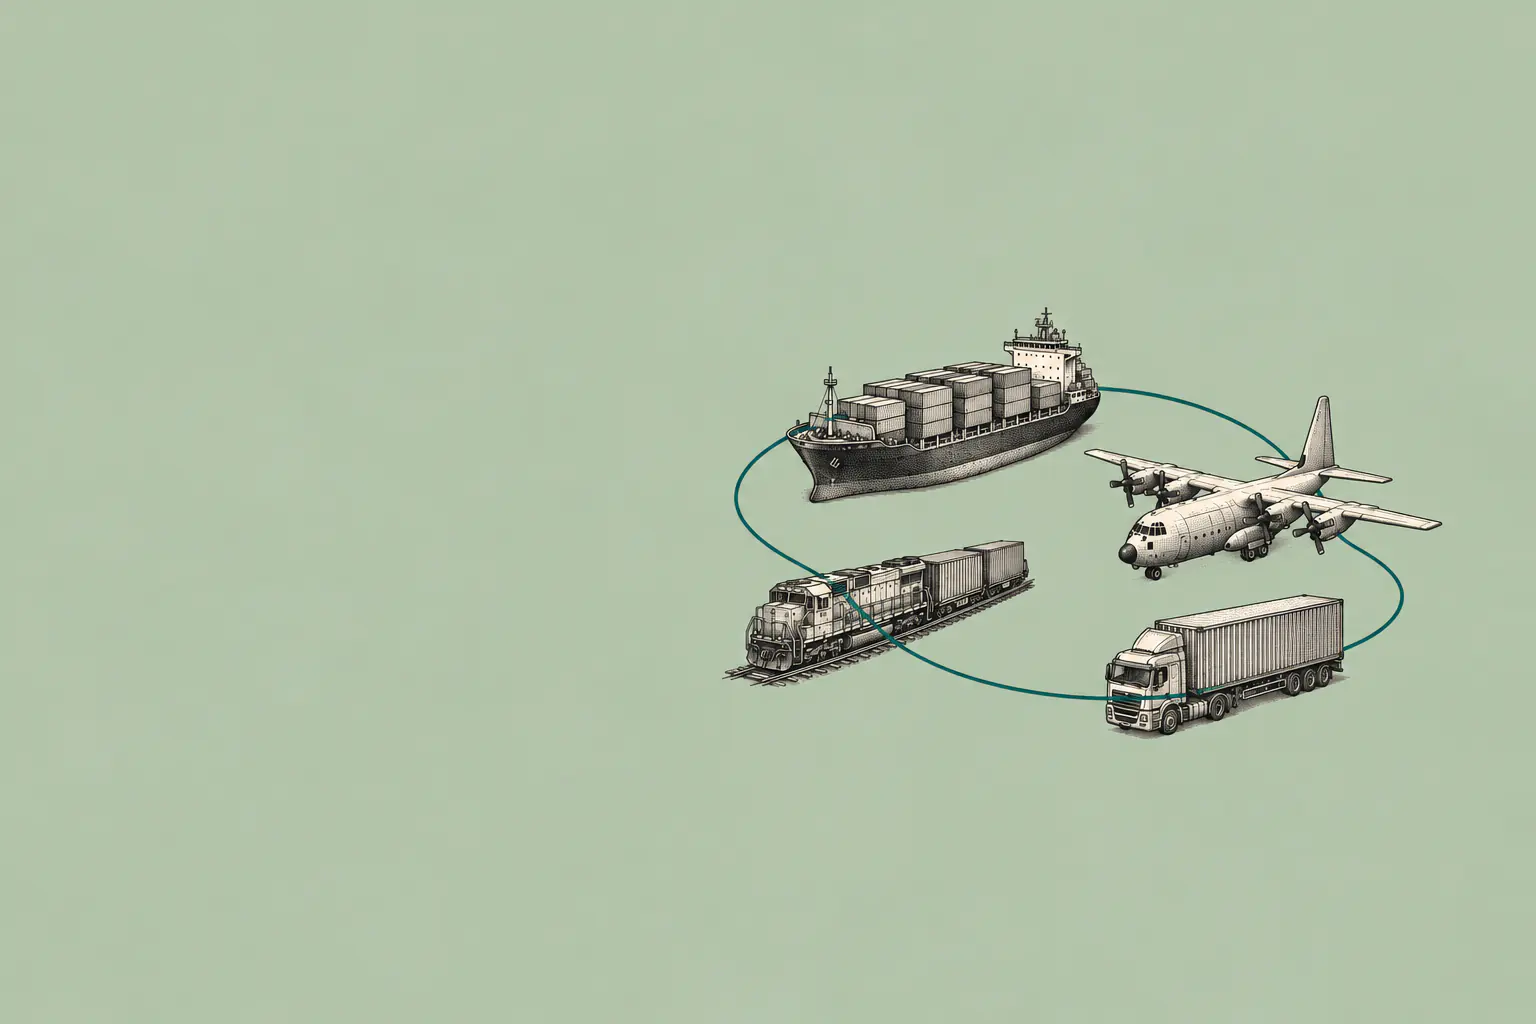
For each shipment or stored lot, record who owns and handles the goods, where the business has custody, which equipment moves them and which partners can interrupt delivery. Ask the insurer to identify applicable forms and triggers; cargo, auto and interruption response cannot be inferred from a line name.
Consider commercial property, tools, equipment and inland marine, cargo and transit, equipment breakdown, commercial auto, and workers’ compensation. Start with the coverages tied to your day-to-day operations, then use the situations and buying questions below to compare your options.
Inventory, packaging, forklifts or other equipment is stored at a company-controlled site.
List sites, property interests, values and causes of loss, then check the actual schedule and exclusions. Customer property in your custody may require separate clarification.2,1
Tools, samples or business property move between warehouse, customer and operating sites.
Ask whether inland-marine wording should schedule movable property and identify the covered items, routes and stages in the actual form.1
The company takes custody of customer goods or arranges shipment through carriers and warehouses.
Cargo-transit terms remain a question for the insurer. Describe the custody chain and obtain the applicable form before treating any goods or liability as insured.1
A conveyor, refrigeration unit, forklift or other machine is critical to fulfillment.
Ask about equipment-breakdown terms separately from commercial property, including the failure trigger and resulting-loss wording.1
The company owns vehicles or employees drive for delivery, pickup or facility operations.
Commercial auto is a separate quote question from personal auto. Ask which vehicles, drivers, routes, states and delivery uses the proposed terms include, and which filings apply to your operation.2,1
You hire warehouse, delivery, dispatch or operations employees or add another work state.
California generally requires employer workers’ compensation coverage even with one employee. Verify current requirements in every other state where staff work.5,6
Trace goods from supplier pickup through carrier, port, warehouse partner, repairer and customer delivery. At each handoff, record who owns and handles the goods and what the contract says about values, custody periods and delays. Give this information to the broker to identify forms to review; it does not show that contract liability is insured.1
Ask which form addresses the goods, when it starts and stops, valuation, loading and unloading, subcontractors and delay losses. Review that wording before describing any protection.1
Describe each facility, stored inventory, customer goods, machinery, chemicals and manual-handling tasks. OSHA identifies warehouse hazards such as powered industrial trucks and material handling; use the actual site and task list when preparing the account, not as a claim that a particular policy responds.4
Ask which locations and machines are scheduled, what breakdown causes apply and whether resulting income loss or extra expense is addressed.1
List suppliers, ports, warehouses, utilities, cloud systems and customer facilities that could interrupt delivery. Some contingent business-interruption forms require physical damage at a dependent property; ask whether each named dependency and trigger meets the proposed wording.3
For vehicles and employees, list routes, states, vehicle ownership and duties. Ask which proposed terms apply and which state or federal filings should be checked for this operation.2,1
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Reliability Score
Not necessarily. Contingent business interruption may require physical damage at a dependent business. A delay alone should not be assumed to meet the form’s trigger; check the actual wording.3
Read the Full AnswerA contract can allocate responsibility, but it does not by itself establish that an insurance policy covers the goods or the liability. Cargo-transit coverage terms depend on the applicable form.1
Read the Full AnswerGet help buying coverage and managing renewals, with less paperwork for your team. Create your account and submit an insurance request online.